WhiteHawk Minerals Misses GAAP Estimates, But Per-Share Cash Flow Rises As Acquisitions Offset Slowing Organic Growth
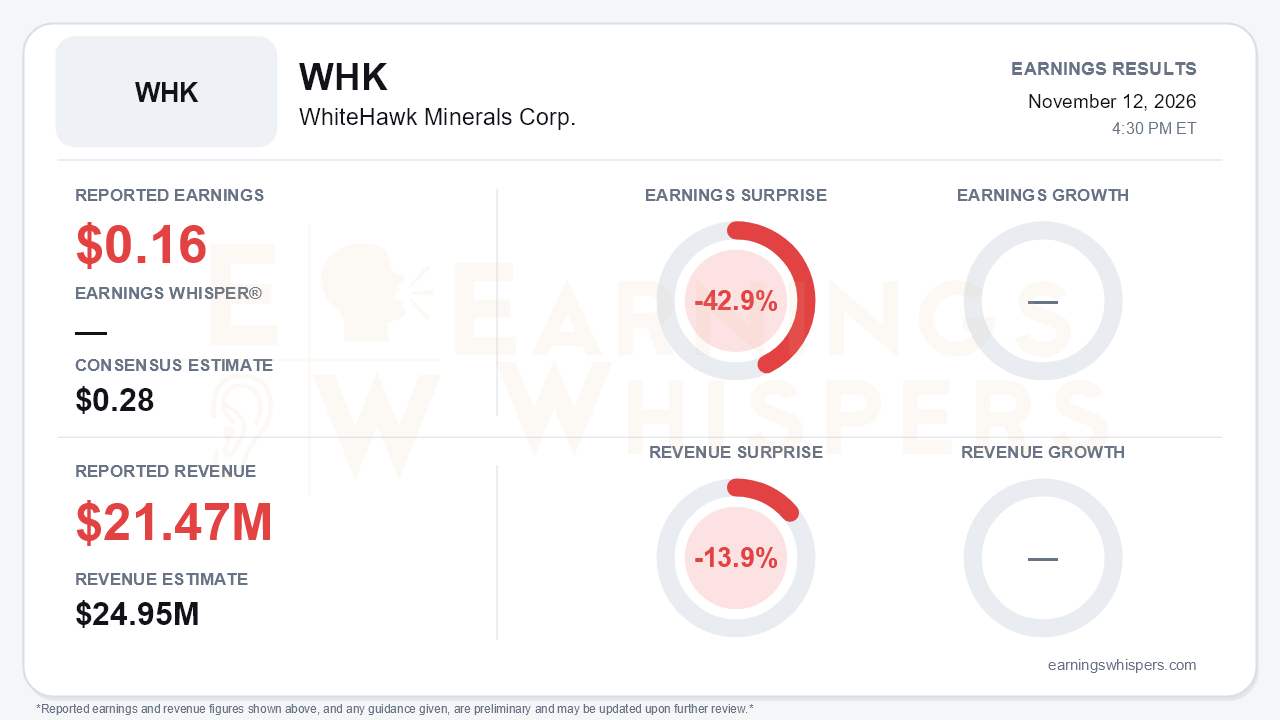
WhiteHawk Minerals (NYSE: WHK) posted a third-quarter result that looks considerably worse on the income statement than in the cash-flow metrics management actually runs the business on. The mineral and royalty company reported GAAP earnings of $0.16 per share, 42.9% below the $0.28 consensus. Revenue of $21.47 million missed the $24.95 million estimate by 13.9% and fell 11% from a year earlier. Yet reported Cash Available for Distribution (CAD) rose to $0.65 per share from $0.63 in the second quarter. Adjusted EBITDA climbed 26% year over year to $21.1 million. That gap between the headline and the cash flow is the central tension of the quarter, and it cuts both ways.
The quality of the miss deserves scrutiny, because most of it came from items that are not core operations. The revenue decline was driven primarily by derivative accounting. Gains on commodity derivatives fell to $3.2 million from $9.3 million, including a $1.4 million unrealized loss compared with a $6.7 million unrealized gain in Q2. Underlying royalty revenue actually grew to $17.0 million from $14.4 million, and lease bonus income more than doubled. GAAP earnings were further shaped by several other items:
- $1.7 million of IPO and acquisition costs;
- a $2.7 million non-cash gain on the earnout liability;
- $2.3 million of earnings allocated to participating securities.
The swing from a $39.2 million loss in Q2 to $6.9 million of net income in Q3 mostly reflects the absence of Q2's debt-extinguishment and management-fee charges, not an operating inflection. In short, GAAP EPS is a noisy gauge of this business, and the miss says little about royalty cash generation.
What the call did reveal is a sharp slowdown in organic momentum. Production reached a record 71.3 MMcfe/d, but that was only 2% above Q2 and 10% above the prior-year quarter. In Q2, the comparable growth rates were 9% sequentially and 57% year over year. Part of the slowdown is timing: the $105 million SJM II acquisition closed September 25 and contributed only five days of volume. On an acquisition-adjusted basis, management reported:
- EBITDA of $25.0 million, up 21% from Q2;
- CAD of $20.8 million, up 20%;
- CAD of $0.68 per share, or a $2.72 annualized run rate.
Pricing remains the vulnerability. Unhedged gas realized just $2.53 per Mcf against a $2.96 Henry Hub average, and management acknowledged a depressed strip. The hedge book is doing the heavy lifting. It lifted realized gas to $3.50 per Mcf, and about 90% of 2027 gas is hedged at roughly $3.80 per MMBtu.
The most consequential forward-looking development was management's first explicit CAD outlook: well over $2.80 per share in 2027 and well over $3.00 in 2028. That framework rests on the acquisition engine. Thirteen deals totaling $45.5 million were signed since August, bringing the post-IPO total to 22 deals and $157.3 million. Those deals are expected to add $5.6 million of cash flow in 2027 and $7.5 million in 2028 at current strip pricing. Management also cast EQT's pending acquisition of Range as a clear positive. It cited royalties on roughly 49% of both operators' production and potential basis tightening from in-basin power demand.
Bears have legitimate ammunition, however:
- **Operator concentration.** The combined EQT-Range would account for about 67% of WhiteHawk's Appalachia volumes.
- **Delayed contribution from new deals.** The new acquisitions lean toward undeveloped and in-process inventory, with some wells not expected online until 2028.
- **Haynesville headwinds.** Small-deal competition in the basin is intensifying, and some operators may defer completions until prices improve.
- **Dilutive funding.** Growth is being financed with a $75 million share placement at $26.10 and $50 million of 10% Series E preferred, with a continuous Series F preferred offering now underway.
The balance sheet, by contrast, strengthened. Leverage fell to about 0.4x, net debt dropped to $38.8 million, and the reserve-based credit facility was upsized to an undrawn $175 million. The $0.50 quarterly dividend was maintained with roughly 1.3x coverage.
Investor sentiment remains negative but improved meaningfully, rising from -0.48 to -0.28 since the prior report. That suggests expectations were low entering the quarter. The market has not rewarded the acquisition story. Shares at $25.61 are down 3.0% from the open after the August report and sit about 2.9% below the 200-day moving average of $26.37. Notably, the stock now trades below the $26.10 price at which the company sold equity in September. The Earnings Whispers AVWAP trend remains negative, consistent with that drift.
The bottom line is that WhiteHawk's headline miss is largely an artifact of hedge accounting and one-time items, while per-share cash flow, the balance sheet, and the multi-year CAD outlook all moved in the right direction. The harder question is durability. Organic growth has decelerated sharply, and unhedged prices are weak. The growth thesis now depends on continued accretive dealmaking funded partly by equity and costly preferred stock at a share price below the last raise. The Q4 print, with a full quarter of SJM II, should show whether the acquisition-adjusted run rate converts into reported results.
Read our earnings preview for WhiteHawk Minerals Corp.: https://www.earningswhispers.com/article/WHK/22973
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-13 | |
| Nov-12 | |
| Nov-05 | |
| Oct-13 | |
| Sep-25 | |
| Sep-25 | |
| Aug-14 | |
| Aug-12 | |
| Jul-31 | |
| Jul-23 | |
| Jul-22 | |
| Jul-14 | |
| Jul-08 | |
| Jul-06 | |
| Jun-11 |
