ImmuCell Swings To A Profit And Rebuilds Margins, But Slower Sell-Through Shows The 46% Revenue Jump Is Partly A Comparison Effect
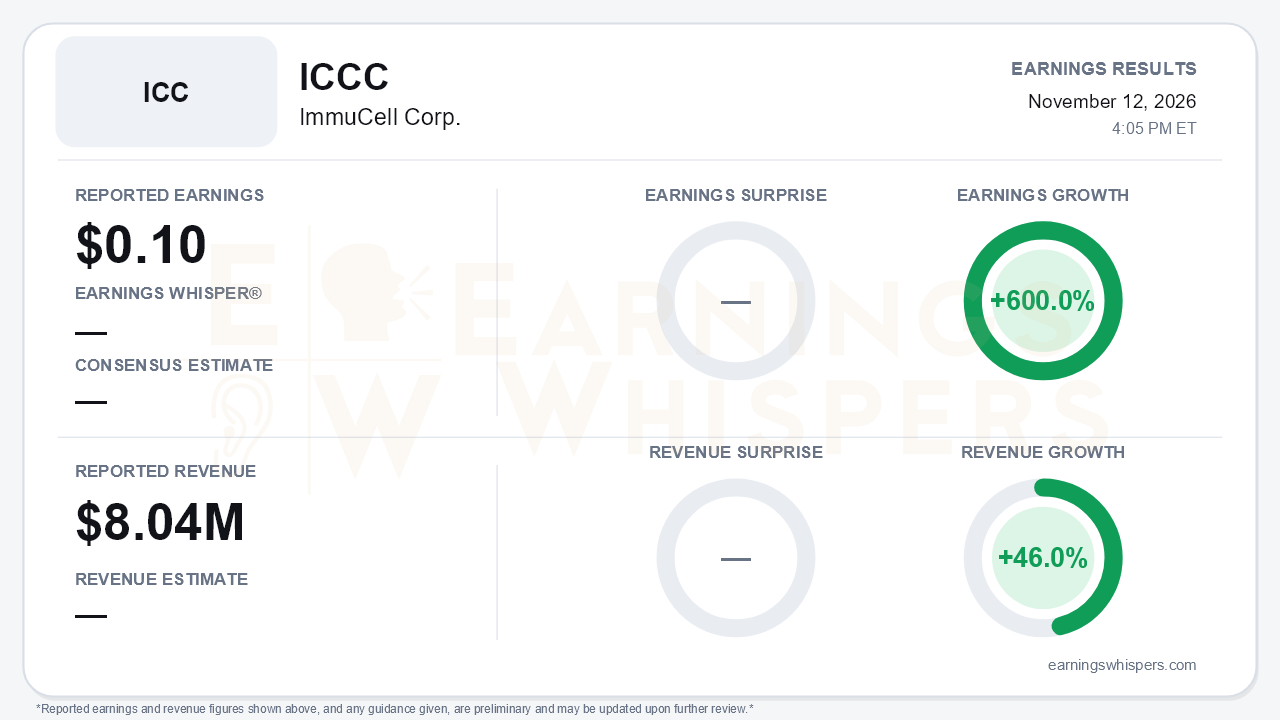
ImmuCell (NASDAQ: ICCC) earned $0.10 per diluted share in the third quarter, up from a $0.02 loss a year earlier. That swing to GAAP net income of $953,000 represents 600.0% earnings growth. Product sales rose 46.0% to $8.04 million, a sharp acceleration from the second quarter's 11.5% growth on $7.2 million in sales. No consensus estimate or whisper number was available, so the quarter has to be judged on its fundamentals. On that basis, the real story is the margin recovery, not the revenue spike. The headline growth rate overstates the momentum in end-market demand, and that is the central tension in the report.
Start with what is genuinely better. Gross margin reached 44.2%, up 130 basis points from a year ago and a dramatic rebound from 33.9% in the second quarter, nearly back to the first quarter's roughly 45%. Management credited higher output, lower scrap and an August price increase. The improvement came despite a roughly 480-basis-point headwind from shifting former Re-Tain development costs into cost of goods sold. Adjusted EBITDA more than doubled to $1.9 million from $0.8 million.
The quality of the operating line still deserves scrutiny. Part of the year-over-year drop in operating expenses is that same reclassification: product development expense fell to $177,000 from $694,000. Meanwhile, sales, marketing and administrative costs climbed to $2.4 million from $1.6 million as the sales team grew from 9 to 13 people. Stock-based compensation jumped to $397,000 from $73,000. Unlike the nine-month results, the third quarter did not benefit from the $2 million settlement booked in May, so this profit was earned operationally.
The call made clear that the 46% headline was flattered. Year-ago sales were depressed by distributor destocking, and international sales surged 573% as the company cleared 2025 Canadian back orders, a benefit management's own framing suggests will not recur. The cleaner demand gauge, distributor out-the-door volume, grew 18%. That is respectable, but it slowed from 28% in the second quarter and 21% in the first. Management's broader commentary was constructive:
- Growth was described as broad-based across territories and product lines.
- New customers drove 46% of net growth.
- TriShield grew 32.1% over nine months.
- The Functional Feed line has already hit its full-year targets.
- Finished-goods inventory of roughly $3 million positions the company for the cow-calf peak season.
Still, investors should not extrapolate the reported growth rate. No formal guidance was offered.
The balance sheet changed the investment setup more than any single income-statement line. Cash rose to $7.9 million from $3.8 million at year-end, and nine-month operating cash flow was $7.3 million, though that figure includes the settlement payment. Management has negotiated a $3 million, three-year credit line to replace the expired $1 million facility and expects to sign it in the fourth quarter. It also terminated the at-the-market equity program. That last move removes a dilution overhang that had been a concern earlier in the year and signals confidence that the $8 million capacity expansion can be funded internally. The project is reported on time and on budget, with $1.7 million spent so far.
Bears have legitimate ammunition, however:
- **Production constraint.** Drying remains a bottleneck until the new freeze dryer arrives in the first half of 2027. Average monthly output of about 435,000 units is up 14% year over year but below the first quarter's record above 450,000.
- **Input costs.** Colostrum prices are rising amid increased competition, which could pressure the margin gains just recaptured.
- **Re-Tain.** The investigational trial failed to support new claims, leaving only a minor aquaculture licensing deal and effectively closing off meaningful partnering value.
Market and sentiment context is thin for this report. Shares opened at $10.72 after the August release, above a 200-day moving average now at $9.02, so the stock entered the quarter trading above its longer-term trend. With no current price or sentiment reading available, the post-report reaction cannot be assessed here.
The bottom line is that ImmuCell delivered a genuinely improved quarter in the places that matter most for a small manufacturer. Gross margin recovered, profitability is now operational rather than settlement-driven, and the balance sheet is strong enough to drop the ATM and fund expansion. The 46% revenue growth figure, though, is partly a product of easy comparisons and one-time back-order clearing, and underlying distributor sell-through decelerated for the second straight quarter. The investment case now hinges on whether peak-season demand, pricing and the 2027 capacity additions can sustain margins against rising colostrum costs and a slowing volume trend.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Nov-12 | |
| Nov-06 | |
| Oct-12 | |
| Sep-28 | |
| Aug-14 | |
| Aug-13 | |
| Aug-06 | |
| Jul-09 | |
| May-15 | |
| May-14 | |
| May-07 | |
| Apr-13 | |
| Apr-08 | |
| Mar-18 |
