PAVmed Beats On A Narrower Loss, But Lucid's Medicare Win Collides With A Strained Parent Balance Sheet
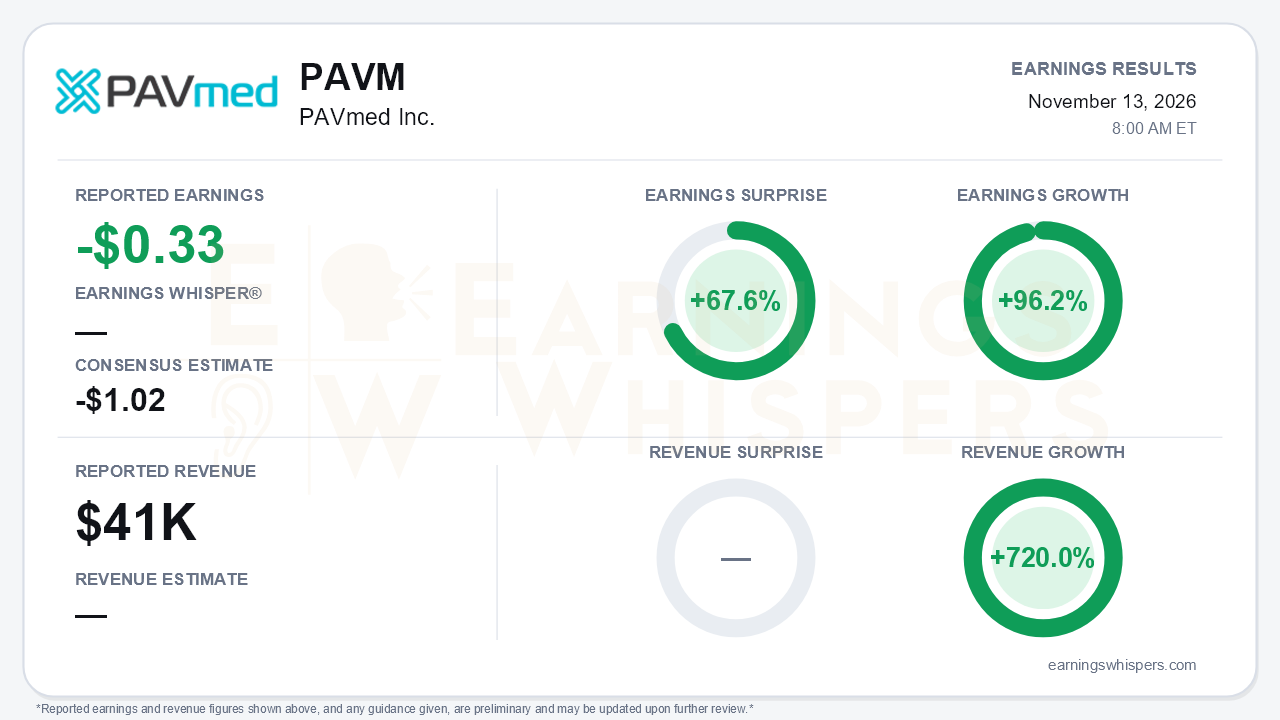
PAVmed reported a third-quarter loss of $0.33 per share, well ahead of the $1.02 consensus loss. That is a 67.6% positive surprise and a 96.2% year-over-year improvement in earnings. Revenue of $0.04 million rose 720.0%, but the growth comes off a $5,000 base and says little about the business. The more important development sits one level down. Lucid Diagnostics, in which PAVmed is the largest common shareholder, is now being paid by Medicare for EsoGuard at the full fee-schedule rate. That is the milestone management had called "impending" on three consecutive calls. The central tension is that the parent company's own financial footing weakened even as the subsidiary hit its breakthrough.
The quality of the beat deserves scrutiny. The release's non-GAAP adjusted net loss was $1.2 million, or $0.19 per share. That is narrower than both Q2's $1.7 million and the $0.62 per share of a year ago, although the share base has expanded roughly ninefold. Non-GAAP operating expenses fell sequentially to $5.6 million from $6.1 million, partly on R&D timing. GAAP results moved the other way. The net loss widened to roughly $13 million from $6.6 million in Q2, driven by a roughly $10 million non-cash markdown of the Lucid stake. Lucid's share price fell from $1.07 to $0.75 during the quarter. As a result, the equity-method investment has shrunk to $23.5 million from $33 million in Q2 and $36 million in Q1. PAVmed's largest asset is losing value even as its commercial prospects improve.
Operationally, the call was the most constructive in several quarters, and management's tone improved accordingly:
- **Lucid:** performed 2,871 EsoGuard tests and recognized $1.2 million of revenue in Q3. October set a volume record above 1,800 tests.
- **Veris enrollment:** monthly enrollment at Ohio State's James Cancer Center nearly doubled from July to September, and the rollout is now live across most departments.
- **Veris implantable:** the monitor reached design freeze in August and began its 90-day GLP animal study in October.
- **PortIO:** advanced from a planned meeting request to an actual FDA call, with a January pre-submission meeting. Management raised the possibility of a 510(k) rather than a de novo pathway.
- **Octeris:** the next-generation probe is complete, a pre-submission package is due this month, and University of North Carolina study enrollment is expected in January.
The timelines nonetheless keep drifting. The Veris 510(k) has slipped from "latter part of 2026" to early 2027, and Octeris moved from expected October IRB approval to January enrollment.
The balance sheet is where bears have legitimate ammunition. PAVmed failed the collateral coverage covenant on its $15 million, 15% senior note at September 30 because Lucid's stock had fallen. The waiver runs only through the 10-Q filing date. The company also had to post $5 million of restricted cash. Of the $8.9 million reported cash balance, only about $3.6 million is unrestricted, down slightly from $3.8 million at Q2. Underlying burn of roughly $2.8 million was funded almost entirely by at-the-market stock sales, and the share count rose to about 8.0 million from 7.3 million. A new ATM facility of up to $9.4 million points to more dilution.
The funding outlook has one further gap. The $30 million Series D warrants were designed around publication of an EsoGuard local coverage determination. Medicare payment instead arrived through claim-by-claim adjudication, and the warrants are now out of the money. Management also acknowledged that capital constraints have curtailed business development, a retreat from Q1's talk of pursuing new assets, including therapeutics.
The market has treated the stock harshly. Shares closed at $1.34 the day before the report, down 71.5% from the $4.70 open after the August release. They sit about 79% below the 200-day moving average of $6.25. The stock hit a 52-week low of $1.17 on November 11 and entered earnings only about 14% above it. The Earnings Whispers trend signals lean negative, with price, sequential growth, and AVWAP readings all pointing lower. Investor sentiment did improve from -0.27 to -0.15, a meaningful shift but one that still leaves expectations net negative. Investors appear more willing to credit the Medicare progress, but not yet persuaded that PAVmed's equity holders will capture it.
The bottom line is that PAVmed's quarter splits cleanly in two. Medicare reimbursement for EsoGuard, rising volumes, and steady device milestones gave the portfolio its most credible operating story in some time. However, the parent's value and financing capacity remain tethered to Lucid's share price, which moved sharply the wrong way. The near-term questions are whether EsoGuard's Medicare ramp can lift Lucid's valuation enough to ease collateral pressure and slow dilution. Until that happens, the headline beat matters less than the covenant waiver and the $3.6 million of unrestricted cash.
Read our earnings preview for PAVmed Inc.: https://www.earningswhispers.com/article/PAVM/22979
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 8 hours | |
| Nov-12 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Nov-03 | |
| Oct-30 | |
| Oct-29 | |
| Oct-22 | |
| Sep-22 | |
| Aug-14 | |
| Aug-14 | |
| Aug-13 | |
| Aug-05 |
