Park Dental Partners Clears A Low EPS Bar, But A Tax Benefit Props Up Earnings As Margins Slide And Acquisitions Carry The Guidance Raise
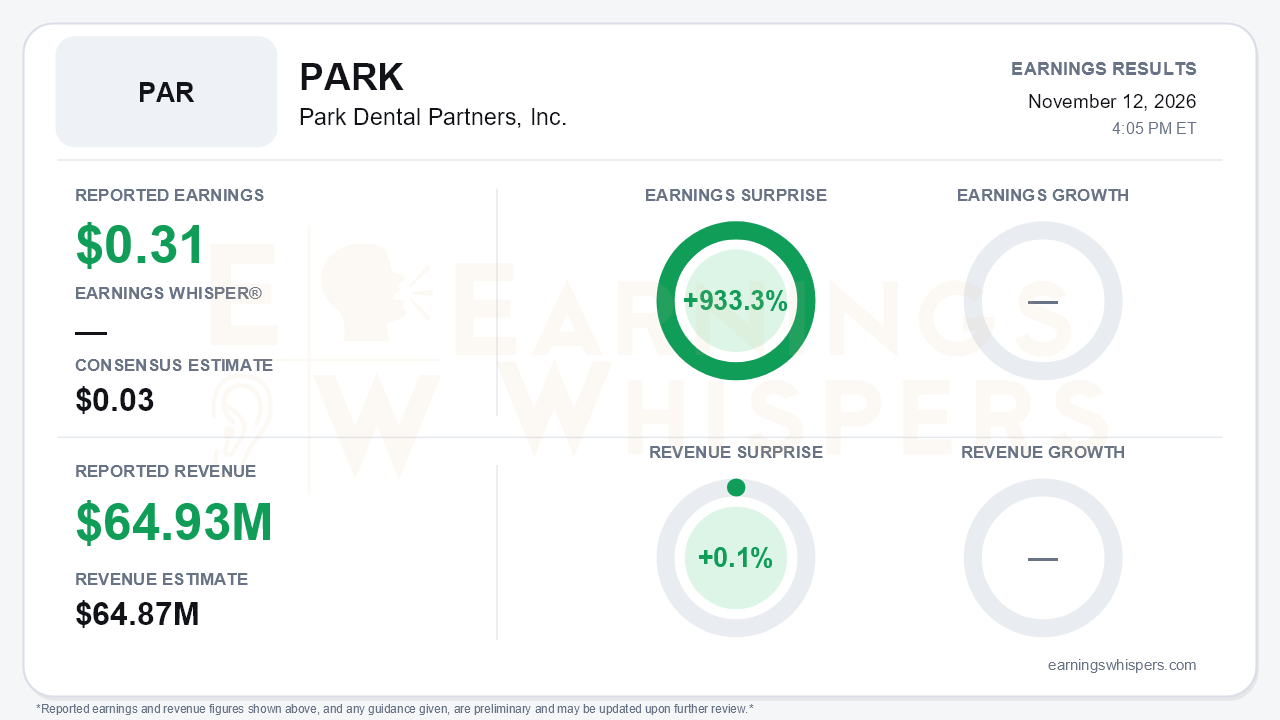
Park Dental Partners (NASDAQ: PARK) posted third-quarter earnings of $0.31 per share, far above the $0.03 consensus estimate, a 933.3% surprise. Revenue of $64.93 million was essentially in line, edging past the $64.87 million consensus by 0.1%. Revenue grew 6.0% from the prior year. The headline beat is real against a very low bar, but its quality deserves scrutiny. Park actually posted an operating loss of $114,000 and a pretax loss of $203,000. Net income of $1.7 million came entirely from a $1.9 million income-tax benefit. Company-reported GAAP diluted EPS was $0.27 and adjusted EPS was $0.57, so the normalized figure sits between the two. Neither company metric suggests that operating profitability improved.
The pressure is visible across the cost structure. Salaries and benefits rose to $41.9 million from $37.8 million, outpacing revenue growth. That increase includes $1.8 million of doctor share-based compensation tied to the public-company transition, which pulled GAAP gross margin down to 12.6% from 15.4%. Even on management's preferred basis, adjusted gross margin slipped 80 basis points to 18.6%. Adjusted EBITDA fell to $5.0 million from $5.3 million, and adjusted EBITDA margin dropped to 7.7%. That compares with 8.7% a year ago and a much stronger 11.2% in the second quarter, so the sequential compression is the more telling figure. Year-over-year EPS comparisons are largely meaningless: the diluted share count jumped to 6.4 million from 1.7 million after the IPO.
The operating story from the call is more nuanced than the margin line suggests. Same-practice revenue growth re-accelerated to 3.2% from 2.3% in the second quarter, though it remains well below the 9.9% posted a year earlier and the 4.1% in the first quarter. Patient retention held steady at 90.2%, and patient visits edged up to 180,955. Management attributed much of the margin squeeze to two factors:
- Hiring: hygienist headcount rose more than 8% sequentially, with onboarding costs loaded into the second half.
- A cybersecurity event: management put the cost at roughly $0.5 million, from about 1.5 days of lost production plus professional fees.
Management framed the hygienist hiring as capacity that should lift 2027 production. That is a credible argument, but for now it remains a promise rather than a result. One more point of slippage: first-quarter guidance called for second-half growth at or above the first quarter's 6.2% pace, and the third quarter printed 6%.
The guidance is where the central tension sits. Park raised its full-year revenue outlook to $262-$265 million from $256-$260 million, but the increase reflects the Village Family Dental acquisition, which closed November 6. Village is expected to contribute roughly $7 million over about eight weeks, based on its roughly $50 million in annual revenue. Stripping that out leaves the organic revenue outlook roughly unchanged to slightly lower. On profit, the adjusted EBITDA range narrowed to $21.2-$22.2 million from $21-$23 million. The midpoint slipped about $0.3 million even though Village is now included, which implies a trimmed core outlook. That midpoint is also essentially flat against 2025's $22.0 million of adjusted EBITDA, despite mid-single-digit revenue growth.
The forward catalysts are substantive. Village is Park's largest deal to date and its first step into a fourth state, North Carolina. It brings:
- 47 doctors and 12 practices, lifting the network to 272 doctors across 100 practices;
- a roughly 10% adjusted EBITDA margin, above Park's current run rate;
- a $39.1 million base price plus $6.9 million in contingent consideration;
- its own acquisition history, which management expects to open further North Carolina deals.
Park also added Sapphire Dental in Arizona in September and expanded its revolver to $25 million from $15 million. The balance sheet can support that strategy, with $23.2 million in cash and $10.6 million of debt at quarter end. Still, bears have legitimate ammunition:
- integration risk on a deal of this scale;
- operating cash flow down to $12.0 million from $16.8 million over nine months, which management attributed to working-capital timing;
- ongoing reliance on below-the-line items to produce GAAP profit.
Investors appear to have recognized these issues. Earnings Whispers sentiment swung from modestly positive (0.15) at the prior report to modestly negative (-0.17), a meaningful shift for this scale. The stock has drifted rather than collapsed: shares are down 3.3% since the opening after the August report, at $21.19 versus $21.92. The market has been treating Park as a growth-by-acquisition story whose organic earnings power has yet to show up.
The bottom line is that Park beat a minimal EPS estimate largely through a tax benefit, while the underlying quarter showed margin compression, a softer core EBITDA outlook, and a revenue raise bought rather than earned organically. Village Family and the hygienist build-out give Park a credible path to stronger 2027 results. Until margins recover and acquisitions convert into higher profit rather than just higher revenue, the souring sentiment looks justified rather than excessive.
Read our earnings preview for Park Dental Partners, Inc.: https://www.earningswhispers.com/article/PARK/22940
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-13 | |
| Nov-13 | |
| Nov-12 | |
| Nov-09 | |
| Nov-04 | |
| Oct-26 | |
| Sep-23 | |
| Aug-12 | |
| Aug-12 | |
| Aug-11 | |
| Aug-10 | |
| Jul-20 | |
| Jun-04 | |
| May-13 | |
| Apr-24 |
