Suncrete Misses And Cuts Full-Year Guidance Below Prior Floors As Acquisition Growth Outruns Execution
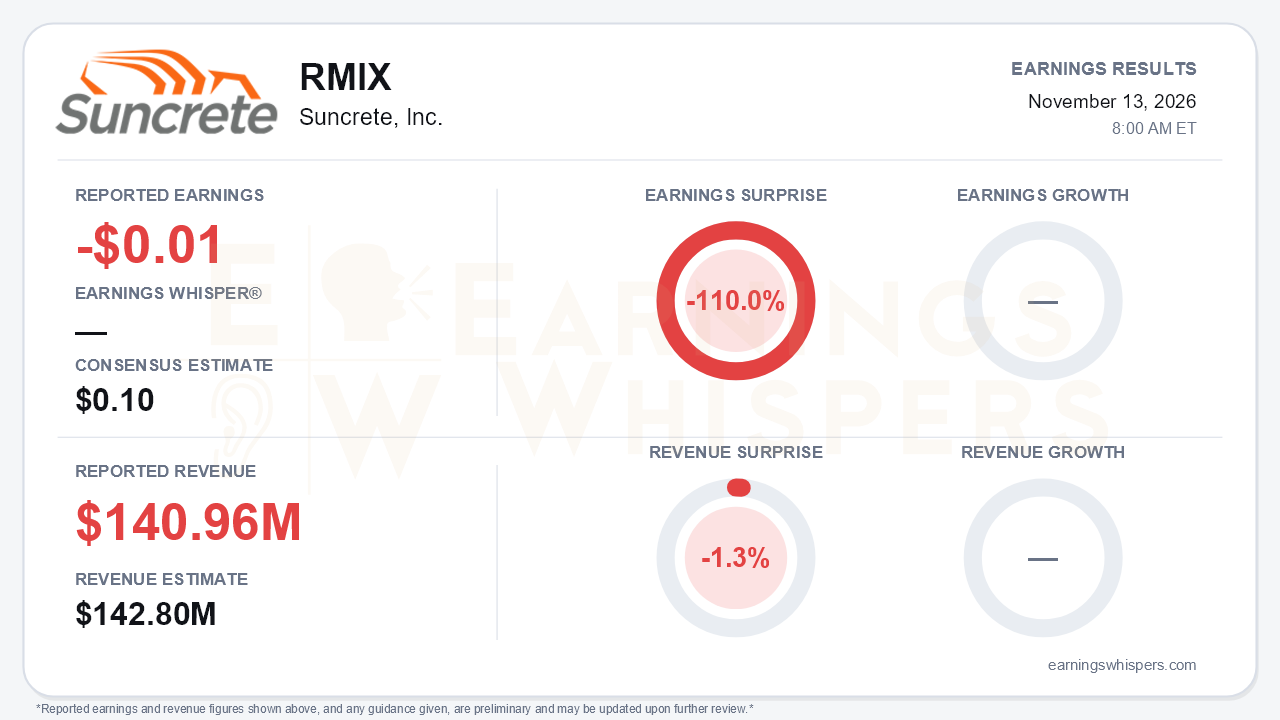
Suncrete (NASDAQ: RMIX) reported a third-quarter loss of $0.01 per share, missing the $0.10 consensus estimate by 110.0%. Revenue of $140.96 million fell 1.3% short of the $142.8 million consensus, even though it rose 45% from the second quarter and 163% from a year ago. The headline growth is real, but it is largely acquired. The more important development was the guidance cut. Full-year revenue, adjusted EBITDA, and net income targets all came down, and the tops of the new EBITDA ranges sit below the floors of the ranges management held as recently as August. For a young public roll-up that asks investors to trust a repeatable integration playbook, missing your own floor is the central problem of the quarter.
The quality of the quarter deserves scrutiny. Net income was a nominal $78 thousand, a swing from the $37.1 million second-quarter loss that included a $26.9 million non-cash charge tied to the SPAC business combination. Preferred dividends of $582 thousand pushed results attributable to common holders to a $504 thousand loss. Adjusted EBITDA rose 66% sequentially to $22.4 million, and the 15.9% margin improved from 13.9% in Q2. Year over year, however, that margin compares with 25.6%, reflecting dilution from lower-margin acquired businesses that have yet to reach target levels. Other pressures also showed up in the numbers:
- Quarterly SG&A reached $31.1 million.
- Interest expense doubled to $5.2 million.
- Operating cash flow for the first nine months was an $8.2 million outflow, versus a $17.8 million inflow a year earlier.
The release also contained inconsistencies. The CEO quote attributes 163% revenue growth to the sequential comparison, while the reported figures show 45%. Net loss guidance in the release had to be corrected on the call to $43.7 million to $39.7 million from $48.7 million to $44.7 million. Neither changes the economics, but both are unwelcome sloppiness from a company asking for patience.
The operating detail on the call was mixed:
- **Organic growth:** about 10%, up from roughly 9% in Q2, split roughly two-thirds volume and one-third price.
- **North Texas:** margins improved through the quarter.
- **ABC Block:** running above expectations.
- **Full-year revenue guidance:** cut to $408-434 million from $420-480 million.
- **Adjusted EBITDA guidance:** cut to $60-64 million from $68-93 million.
The full-year revenue range, set against $300.0 million through nine months, implies a fourth quarter of roughly $108-134 million, a step down from Q3's $141 million. Management blamed several factors:
- residential weakness that may not have troughed;
- commercial projects slipping on election and geopolitical uncertainty;
- rain-delayed site work pushed into 2027.
The execution story also softened. The integration window, once framed as 9-18 months, now skews to 18 months. The SG&A run-rate was raised to about $31 million per quarter from the roughly $25 million guided in Q2. The tone moved from Q2's confidence in maintaining guidance to a defensive acknowledgment that progress is "not a straight line."
The call did preserve a credible 2027 story, which is why the setup is not purely negative. Management quantified a $200-250 million revenue contribution next year from the 2026 acquisitions. It cited a data center backlog of more than two years across Texas, Oklahoma, and Louisiana, and sizable projects starting in Q4 and after Q1 2027. It also indicated a Q4 acquisition is likely and said supplier cost increases should pass through in the 2027 pricing cycle. Liquidity rose to $206.5 million from $51.1 million. Bears still have legitimate ammunition:
- No deals closed in Q3 despite earlier hints, and several slipped to 1H 2027.
- Pro forma leverage of about 3.4x sits above the 2.5-3.2x target range.
- Texas data center moratoriums add a new risk to the most promising demand driver.
- Leaning on further acquisitions to drive growth while integration timelines stretch compounds execution risk.
The market had largely anticipated trouble. Shares fell 52.4% from the $17.05 open after the August report to $8.12 in the pre-report snapshot. That leaves the stock 48.5% below its 200-day moving average of $15.78 and just 1.2% above an inter-earnings and 52-week low of $8.02 set on November 12, far from the $18.81 high reached in late August. Investor sentiment swung sharply from modestly positive (0.24) to clearly negative (-0.40), and the AVWAP trend remains negative. Much of the disappointment was arguably priced in before the release, but the guidance cut gives sellers a concrete justification rather than a reason to reverse course.
The bottom line is that Suncrete's scale is growing quickly while its credibility is shrinking. The company has acquired revenue, capital, and a plausible 2027 pipeline. Yet it missed estimates, cut guidance below prior floors, stretched integration timelines, raised overhead, and lifted leverage above target in the same quarter. Until management shows that acquired businesses can reach target margins on schedule and that 2027 project starts actually materialize, the stock's position near its lows looks like a fair reflection of a story that now has to be re-earned.
Read our earnings preview for Suncrete, Inc.: https://www.earningswhispers.com/article/RMIX/23046
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-13 | |
| Nov-13 | |
| Nov-08 | |
| Oct-16 | |
| Aug-14 | |
| Jul-20 | |
| Jun-15 | |
| May-26 | |
| May-15 | |
| May-07 | |
| Apr-29 | |
| Apr-21 |
