Eagle Point Income Doubles Its EPS Estimate On A One-Time Prepayment As The Payout Loses Cash-Flow Cover And NAV Keeps Falling
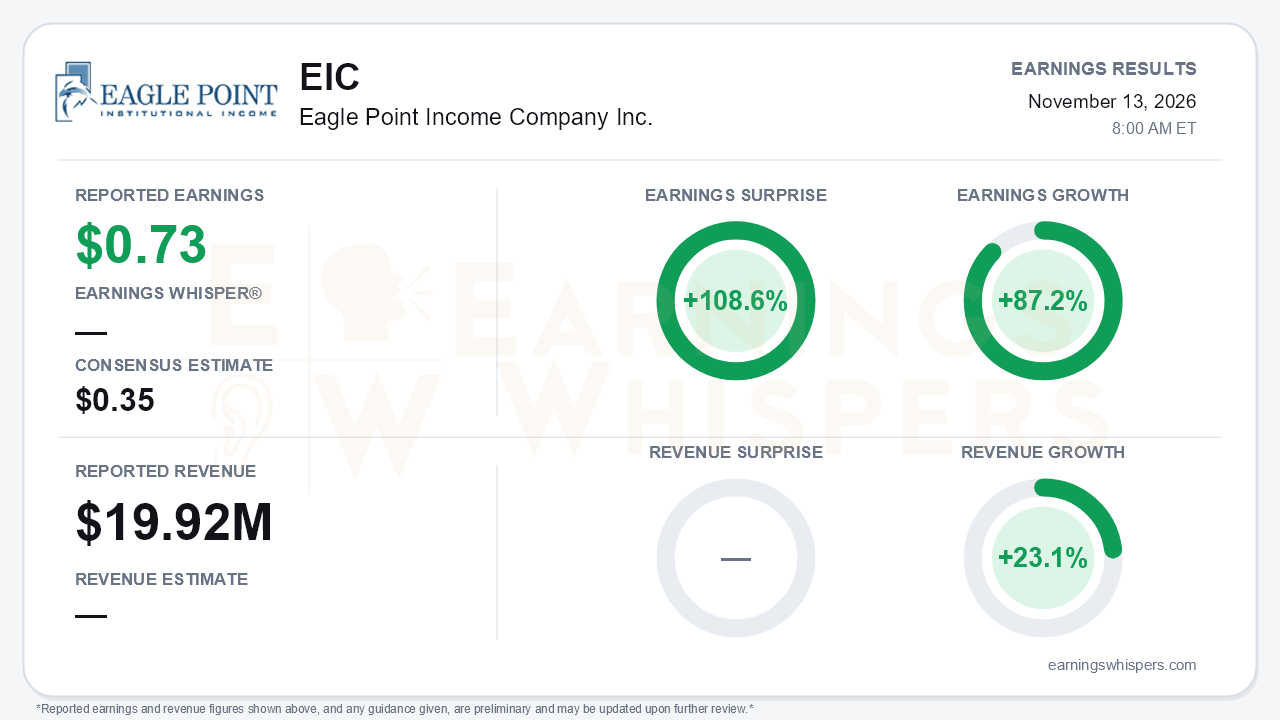
Eagle Point Income Company (NYSE: EIC) reported third-quarter net investment income of $0.73 per share. That more than doubled the $0.35 consensus estimate, a 108.6% surprise, and was up 87.2% from a year ago. Total investment income rose 23.1% to $19.92 million. NII less realized losses swung to $0.67 per share from negative $0.29 in the second quarter. The quality of the beat, however, deserves scrutiny. About $0.30 per share came from the early prepayment of a single private infrastructure credit. Excluding that item, NII less realized losses was roughly $0.37, essentially unchanged from the $0.36-$0.37 run rate of the prior two quarters. The headline shows sharp acceleration. The underlying earnings engine shows a flat line.
The flat earnings line is not the main concern. Cash generation is. Recurring portfolio cash flows fell to $9.3 million, or $0.40 per share. That was below the roughly $0.44 per share needed to cover distributions plus expenses, the first such shortfall across the past four calls. The decline has been steady: $0.79 in the fourth quarter of fiscal 2025, then $0.62, $0.52 and now $0.40. GAAP net income tells a similar story. It fell to $0.20 per share from $0.84 in the second quarter after $10.4 million of unrealized losses. NAV slipped to $12.39 from $12.52. Management's October estimate of $11.92-$12.02 implies a further decline of about 3%, driven by pressure on CLO equity marks. That is the central tension: income statement earnings look strong, while the cash and book-value figures that ultimately support the $0.11 monthly distribution are eroding.
The balance sheet has also tightened. Paying off the $38 million Series A term preferred left roughly $9.5 million of cash and revolver capacity at the end of October. That compares with $53 million in July and $85 million in January. Leverage rose to 17.3% from 12%, still well below management's 25%-35% long-term target, so there is room to borrow. The trade-off is less flexibility at a time when deployment is already slowing. New investments totaled $31 million, down from $39 million in the second quarter and $56 million in the first. Yields on new investments also fell, to 15.6% from 17.9%. Preferred issuance remains small at about $1 million per quarter. Share buybacks, which management emphasized earlier in the year, were no longer discussed.
The call did preserve a credible defensive story. Credit is improving:
- The trailing 12-month loan default rate fell to 0.6% from 1.0% in the second quarter and 1.4% in the first.
- EIC's look-through default exposure dropped to 22 basis points from 36.
- Software loan prices are up 2.3% since the first quarter, which management described as signs of stabilization.
- The book remains highly diversified across 1,377 obligors, with the largest at 0.7% of the underlying loan portfolio.
Management leaned heavily on a rising-rate thesis for the floating-rate portfolio. CLO debt is 53% of the book, down from 59%, and coupons reset around the 10th of each quarter, which could lift first-quarter 2027 income if rates move higher. Infrastructure credit, now about 10% of the portfolio with a pipeline from the broader Eagle Point platform, is the main diversification lever. It also produced this quarter's windfall. The weighted average effective yield on CLO holdings rose to 10.7% from 9.7%. Bears can still point out that the distribution, now declared through the first quarter of 2027, currently depends more on accrued income and rate hopes than on cash received.
The market had been skeptical heading into the report. Shares closed at $8.88 the day before the release. That is 10.5% below the opening price after the August report and about 10% below the 200-day moving average of $9.86. The stock sat only 4.5% above the 52-week low of $8.50 set on November 6, near the bottom of an inter-earnings range that topped at $10.16 on the day after the prior report. At current levels the stock trades at roughly a 25% discount to even the October NAV estimate, a sign of how little credit investors are giving reported earnings. Investor sentiment remained negative but improved modestly, moving to -0.49 from -0.58. That suggests expectations were low rather than collapsing. The Earnings Whispers trend signals for price and AVWAP remain negative, consistent with the weak tape.
The bottom line is that EIC's large EPS beat is mostly a one-time event layered on a flat earnings base. Meanwhile, recurring cash flow, NAV, deployment and liquidity all moved in the wrong direction. Better credit metrics and potential support from rising rates give management a real argument. Still, the stock's slide toward its lows and its wide NAV discount show that investors are focused on distribution coverage. The next few quarters of cash flows will matter far more than this quarter's headline surprise.
Read our earnings preview for Eagle Point Income Company Inc.: https://www.earningswhispers.com/article/EIC/23044
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-13 | |
| Nov-13 | |
| Nov-08 | |
| Oct-29 | |
| Oct-14 | |
| Sep-21 | |
| Aug-12 | |
| Jul-30 | |
| May-19 | |
| May-18 | |
| May-12 | |
| May-05 | |
| Mar-16 | |
| Feb-26 | |
| Feb-25 |
