Moving IMage Swings To A Profit On Pulled-Forward Projects, But Margin Erosion And Working-Capital Cash Temper The Quarter
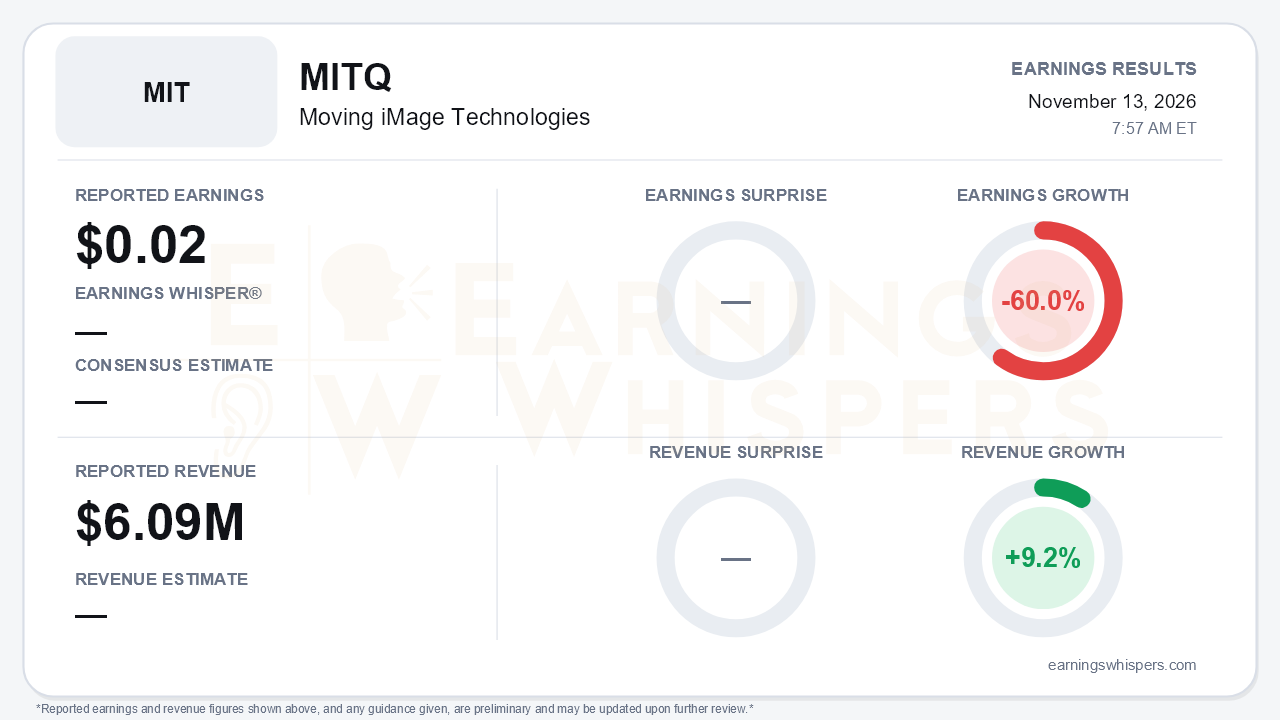
Moving iMage Technologies (NYSE American: MITQ) reported fiscal first-quarter earnings of $0.02 per share on revenue of $6.09 million. Earnings fell 60.0% from a year ago while revenue grew 9.2%. No consensus estimate was available, so the useful benchmark is management's own outlook. The company had guided to roughly $4.5 million on its prior call and cleared that comfortably. Net income of $181,000 was MiT's first profitable quarter after losses of $388,000, $122,000 and $296,000 in fiscal Q2 through Q4 2026. That sequential swing is the headline management wants investors to see. The central tension is that much of the upside came from timing rather than a structural change in earnings power.
The quality of the beat deserves scrutiny. Management attributed the revenue strength to customers accelerating delivery ahead of the holiday film window. The release cites one customer advancing a project, while the call described two projects pulled forward by a quarter. Either way, part of Q1's revenue was borrowed from later periods. Profitability also moved the wrong way beneath the top line:
- Gross margin fell to 24.1% from 30.0% a year earlier and from 34.8% in fiscal Q3, a level that had been flattered by acquired DCS inventory.
- Gross profit dollars declined to $1.47 million from $1.67 million, even on higher sales.
- Management blamed weaker sales of high-margin cinema accessories, higher costs on other accessories and rising freight, particularly internationally. The freight and input-cost pressure is a newly cited headwind.
- Operating income slipped to $217,000 from $350,000.
- The year-ago bottom line included a $128,000 gain on extinguished payables, which inflates the reported 60.0% earnings decline.
- The current quarter also absorbed a $221,000 inventory reserve and benefited from an $84,000 credit-loss reversal.
Cost discipline is real but uneven. Total operating expenses held essentially flat at $1.31 million. General and administrative expense fell to $691,000 from $890,000, while selling and marketing rose to $569,000 from $386,000 as the company shifted spending toward growth. Management said much of the restructuring is complete and the focus now turns to revenue initiatives.
The balance sheet improvement also needs context. Cash rose to $5.69 million from $3.19 million in a single quarter, and operating cash flow was $2.49 million. The drivers were mostly working capital, not earnings:
- About $1 million in customer deposits collected against future work.
- A $2.45 million increase in accounts payable, which management openly described as managing payment timing.
- These inflows more than offset a $1.35 million build in inventory.
The deposits are an encouraging demand signal. The payables stretch, however, will likely reverse. Working capital improved only modestly, to $4.24 million from $4.0 million.
The forward-looking story is more constructive than the margin picture. Management guided fiscal Q2 revenue to about $5.4 million despite the seasonal November–December pause in exhibitor capital spending. That figure compares with just $3.3 million in the year-ago quarter and rests largely on a turnkey 16-screen theater upgrade. The DCS loudspeaker line contributed $429,000, up from about $400,000 in Q4, and cumulative DCS sales of $1.3 million across 20-plus countries are nearing the $1.5 million purchase price. Management also described activity as more robust, pointed to potential calendar-2027 projects including meaningful LEA amplifier opportunities, and renewed its mention of evaluating business combinations or strategic transactions.
Bears still have legitimate ammunition:
- DCS backlog was flat at about $459,000, and integration, manufacturing and logistics challenges persist.
- Fiscal 2027 customer budgets have not yet been released.
- The pull-forward could create a softer patch after Q2.
- The call drew no analyst questions, leaving the outlook largely untested.
Market context is thin. The stock opened at $0.61 after the prior report in late September, just above a 200-day moving average of $0.59. That placement suggests shares entered this quarter roughly at their longer-term trend rather than pricing in either a recovery or a breakdown. Current price and sentiment readings were not available to gauge how investors have repositioned since.
The bottom line is that MiT delivered a cleaner headline than it has in a year, with revenue above plan, a return to profitability and a fuller cash balance. The underlying drivers were timing, working capital and cost cuts rather than better unit economics. Management itself conceded that one profitable quarter is not a trend. For that to change, MiT needs to stop the gross-margin erosion, convert DCS and LEA conversations into backlog growth, and show that the stronger Q2 outlook is not simply the last of the pulled-forward revenue.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-13 | |
| Nov-13 | |
| Nov-10 | |
| Oct-28 | |
| Oct-14 | |
| Sep-29 | |
| Sep-28 | |
| Sep-23 | |
| Sep-17 | |
| May-14 | |
| May-13 | |
| Apr-30 | |
| Apr-06 | |
| Mar-25 | |
| Feb-26 |
