U.S. Global Investors' Core Business Turns A Slim Operating Profit, But Fading Investment Gains Push EPS Down 91.7% As AUM Stalls Near $1.6 Billion
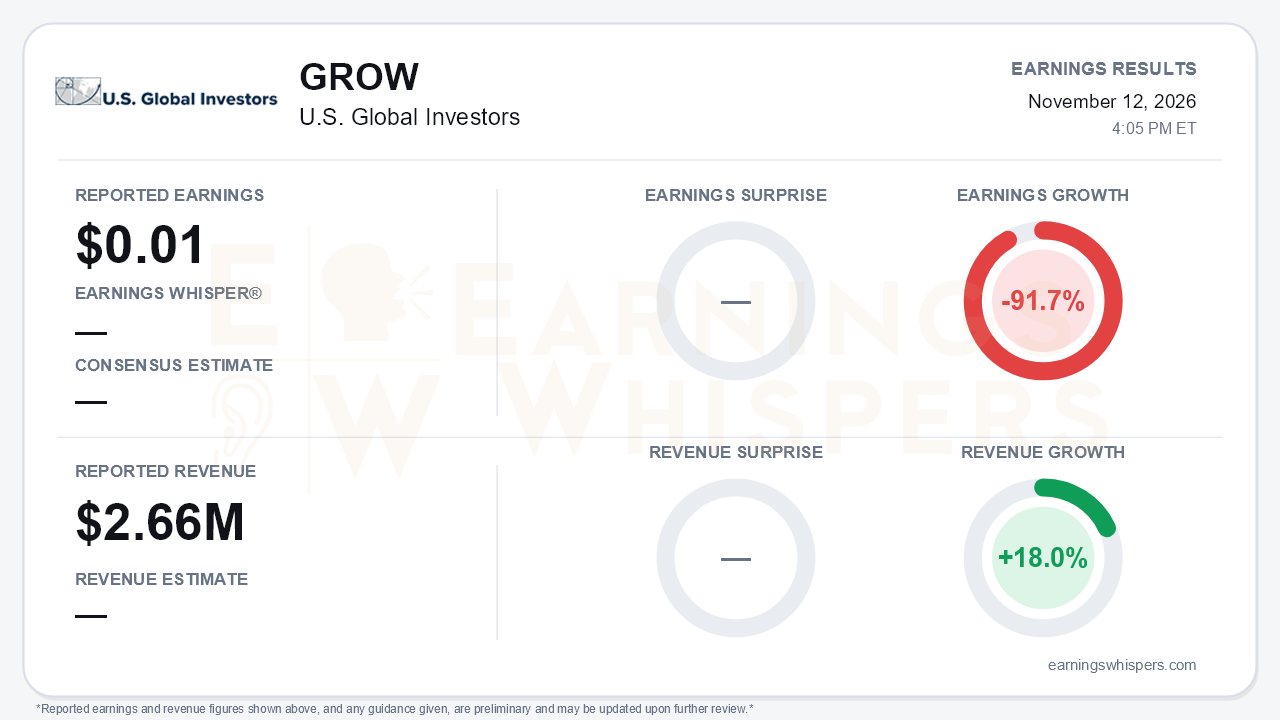
U.S. Global Investors (NASDAQ: GROW) reported fiscal first-quarter earnings of $0.01 per share on revenue of $2.66 million for the quarter ended September 2026. Earnings fell 91.7% from a year earlier, while revenue grew 18.0%. There was no consensus estimate to measure against. The real story is the gap between those two growth rates. The core advisory business improved year over year and swung to a small operating profit. But the earnings that investors had grown used to were never really coming from operations. They came from investment gains, and this quarter those gains largely disappeared.
The quality of the quarter deserves scrutiny from both directions. On the positive side, operating expenses fell 6% to $2.6 million, with G&A down 8% and advertising down 23%. That turned a $515,000 operating loss a year ago into operating income of $55,000. On the negative side, total other income collapsed to $193,000 from $2.36 million, which included $185,000 of unrealized losses on securities. Net income fell to $171,000 from $1.5 million. Sequentially the drop is starker: the June-quarter-ending Q3 of fiscal 2026 produced $2.7 million, or $0.23 per share, helped by a $1.9 million unrealized gain on InvestX. Operating income was also lower than the $88,000 posted in that period. In short, GROW is a roughly break-even operating business with a volatile investment portfolio attached, and this quarter showed what the base looks like without the portfolio's help.
The 18% year-over-year revenue gain also flatters the trajectory. Revenue has hovered between $2.5 million and $2.8 million for four straight quarters, and this quarter's roughly $2.7 million was essentially flat sequentially. Average assets under management were $1.6 billion, up 14% from a year ago. However, they were down slightly from $1.63 billion in the prior comparable sequential period, and Frank Holmes acknowledged that assets "went sideways" amid turmoil from the yen carry-trade unwind. Gold remains the engine: combined average assets in USERX, UNWPX and GOAU rose 45% to $547.6 million. That deepens the firm's dependence on a single, notoriously volatile theme. The share of revenue from ETFs was cited at 59%, down from 63% and roughly 70% in earlier quarters.
The growth pockets are real but small. Average assets in the WAR defense-and-technology ETF rose 17% sequentially to $37.4 million, nearly five times the year-ago level, and WAR gained a dual listing on the Lima Stock Exchange. SEA averaged $16.2 million, up 81% year over year. Management highlighted year-to-date returns of roughly 35% for WAR and 40% for SEA against a market gain of about 12%, along with strong PMI and container-import data. Even so, these funds together hold barely $54 million, too little to move the revenue line meaningfully yet. The seasonal case for JETS in the fourth quarter is a talking point, not a forecast, and management said as much. GROW provides no formal guidance. The tone remained promotional on gold, defense AI and macro themes. It was noticeably less focused on near-term asset growth than earlier calls, which featured "wind is at our sail" language and a $10 billion GOAU ambition.
Capital return is where bears have legitimate ammunition. Buyback spending has declined for three consecutive reported quarters: $664,000, then $534,000, then $319,000 for 105,457 shares this quarter. Net working capital has drifted down from $36.7 million to $35.4 million. Liquidity is not a concern, with a 23.1-to-1 current ratio and $24.3 million in cash. The release describes that cash as essentially unchanged from June, while it is down from $25.2 million at the end of 2025. The monthly dividend of $0.0075 is intact. The cited dividend yield rose to 3.36% from 2.83%, which reflects a lower share price rather than a bigger payout. The 8.33% shareholder yield headline is similarly helped by a weaker stock.
That weaker stock frames the market setup. Shares opened at $3.38 after the September report, and the rising dividend yield indicates they have lost ground since. The 200-day moving average sits at $2.92, a reference point for whether the recent slide is a pullback within a longer recovery or something more persistent. No updated sentiment reading was available to gauge how investor expectations shifted.
The bottom line is that GROW's operating business is modestly healthier than a year ago, with leaner costs, a small operating profit and gold-driven fee growth. The quarter nonetheless exposed how much reported earnings had leaned on investment gains, while assets, revenue and buybacks have all flattened. Until AUM breaks decisively above $1.6 billion or the thematic ETFs scale meaningfully, earnings will likely continue to swing with gold prices and portfolio marks rather than with the core business.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-13 | |
| Nov-13 | |
| Nov-13 | |
| Nov-12 | |
| Nov-06 | |
| Oct-30 | |
| Oct-30 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-16 | |
| Oct-09 | |
| Oct-09 | |
| Oct-02 | |
| Oct-02 |
