High Roller's Q3 Loss Deepens As Casino Revenue Shrinks And Burn Rises, But The ROLR Prediction-Markets Launch Is Now Live
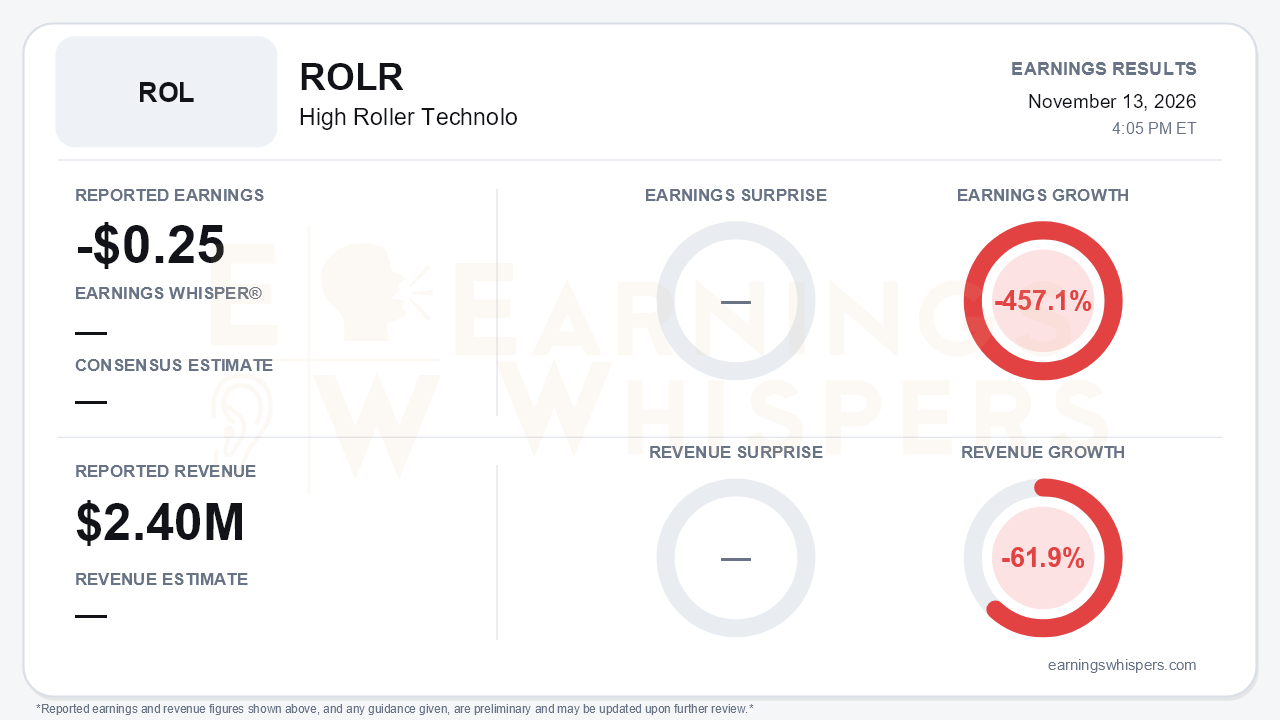
High Roller Technologies (NYSE American: ROLR) reported a third-quarter loss of $0.25 per share on revenue of $2.4 million. There was no consensus estimate or Earnings Whisper, so the quarter has to be judged on execution rather than on a beat or miss. By that standard, the numbers were poor, and that was expected. Earnings fell 457.1% year over year, a swing from a GAAP profit to a loss. Revenue fell 61.9% on Earnings Whispers' normalized basis. The company's own comparison, against $4.9 million of prior-year continuing-operations revenue, shows a 51% decline. The central tension is plain. The legacy online casino is being deliberately shrunk while the ROLR prediction-markets platform consumes cash, and Q3 was the last quarter in which ROLR showed up only as an expense.
The headline earnings swing overstates the operating deterioration, but only somewhat. The year-ago profit was flattered by a $3.6 million income tax benefit from releasing a valuation allowance at a Maltese subsidiary. The cleaner comparison is pretax loss, which widened from $0.8 million to $2.6 million. Adjusted EBITDA went from negative $0.2 million to negative $2.1 million. Total operating expenses actually fell 8% to $5.1 million, because direct operating costs collapsed alongside revenue. Advertising, however, roughly doubled to about $1.0 million, and more than half of that went to related-party affiliate Spike Up Media. That relationship deserves monitoring as spending scales. The company also restated its Q1 and Q2 filings to correct about $1.0 million of non-cash warrant costs. The fix was immaterial to cash, but it is not a confidence-builder on internal controls.
Sequentially, the trend is still heading the wrong way. Revenue slipped from $2.8 million in Q2 to $2.4 million. Adjusted EBITDA losses widened from $1.8 million to $2.1 million, and the operating loss grew from $2.5 million to $2.7 million. The one genuine bright spot in the casino business is quality over quantity. Revenue per unique depositing customer more than doubled to $507 from $242, and management said it earns roughly 35% more per dollar wagered. That will not offset the volume loss, though. The December 1 exit from New Zealand sets up another step-down that will be fully felt in Q1 2027.
The call's most important shift was tone. In Q2, management talked about staged, milestone-based spending. In Q3, it described itself as 'in growth mode... looking to get out there and spend,' and framed 2027 as the first full year with prediction markets as the major growth driver. Management delivered what it promised on timing:
- an invitation-only beta on September 15;
- a public launch on October 21;
- an iOS app on November 9, with Android targeted before year-end.
Optionality also expanded. A source-code license with DeepEther Labs (mrkts.com) gives the company ownership of its customer-facing app. NFA registration as a commodity trading advisor precedes a new product due before the end of November. The newly formed ROLR FCM LLC could eventually take the company outside the 24-month Crypto.com introducing-broker exclusivity that began in April 2026. The ProphetX agreement would broaden event contracts, but it only becomes effective six months after an FCM registration the company has not yet applied for. Those are options, not revenue.
Bears have legitimate ammunition. Management disclosed no launch KPIs: no customer counts, trading volume, or acquisition costs. Investors are being asked to underwrite a spending ramp without evidence of unit economics. Competition is intensifying, including a reported Meta entry, and state litigation over event contracts remains an open risk. Cash fell from $18.0 million to $13.4 million in a single quarter, and nine-month operating burn reached $8.9 million versus $5.9 million at midyear. Management still says it has more than 12 months of runway. Reconciling that claim with a roughly $4.6 million quarterly decline, just as marketing accelerates, will require either fast ROLR revenue or spending restraint the new tone does not signal. The year-to-date cash build came from equity issuance, with shares outstanding rising from 8.5 million to 11.0 million. Further dilution is a realistic possibility if adoption is slow.
Market context is thin. No current sentiment or price data was supplied. For reference, shares opened at $5.61 after the August report, essentially on top of the current 200-day moving average of $5.60. Without a current price, the market's verdict on this quarter cannot yet be read from the available data.
The bottom line is that High Roller has completed the hardest pre-revenue milestone by getting ROLR live on schedule. Every other financial metric, however, is moving the wrong way: revenue, losses, and cash. The next report will be the first real test, because Q4 must show prediction-market revenue and some disclosure of customer traction to justify the shift into growth mode. Until then, this is a funded-but-shrinking casino business carrying an unproven, cash-hungry option on prediction markets.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-13 | |
| Nov-13 | |
| Nov-12 | |
| Nov-12 | |
| Nov-11 | |
| Nov-10 | |
| Nov-09 | |
| Nov-06 | |
| Nov-02 | |
| Oct-21 | |
| Oct-19 | |
| Oct-13 | |
| Oct-09 | |
| Sep-21 | |
| Sep-15 |
