SBC Medical's Growth Snaps Back To 35% On Fee Revisions, But Below-The-Line Leakage And Non-Organic Drivers Complicate The Beat
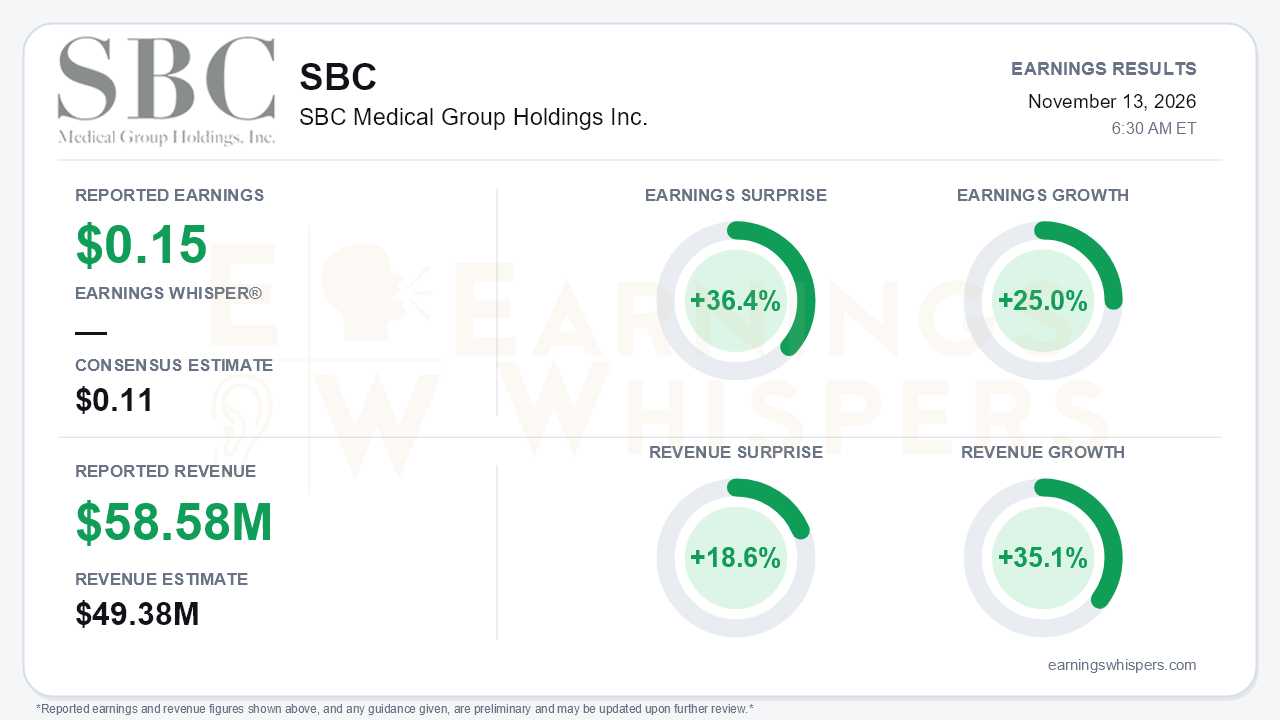
SBC Medical Group Holdings delivered a decisive third-quarter beat. It earned $0.15 per share against a $0.11 consensus, a 36.4% surprise, on revenue of $58.58 million that topped the $49.38 million estimate by 18.6%. Earnings grew 25.0% year over year, and revenue rose 35.1%. The quarter caps a sharp turn in the revenue trajectory: reported growth went from a 9% decline in the first quarter, to a 13% gain in the second, to 35% now. Management called it a 'strong reacceleration,' and the operating numbers support that description. The central tension is how much of the reacceleration is durable organic momentum and how much reflects fee-structure changes, a consolidation and favorable one-off items.
The operating line is where the quarter was strongest. Income from operations rose 66% to $26.4 million, and operating margin widened to 45% from 37% a year earlier. Adjusted EBITDA also jumped 66% to $27.6 million, with margin expanding nine points to 47%. Gross profit grew about $11.6 million, while SG&A rose only about $1 million, which shows the operating leverage in the MSO model.
The gains thinned out below the operating line:
- Net income attributable to SBC rose just 22%, and net margin slipped three points to 27%.
- A $0.9 million foreign-exchange loss replaced a $0.9 million gain in the prior-year quarter.
- Other income fell by roughly $0.9 million.
- Income tax expense climbed to $9.4 million from $5.7 million.
- New equity-method losses, tied to the OrangeTwist stake, and a larger minority-interest share took further bites.
The quality of the beat therefore deserves some scrutiny, even if the core engine clearly improved. The nine-month picture is also more modest, with revenue up 13% and EPS up only 3%.
The call explained the sources of the acceleration more candidly than the release did. Management services revenue rose 73%, reflecting the roughly $15 million annual service-fee uplift flagged last quarter for call-center and Gorilla/Rize clinic support. The newly consolidated Waqoo business contributed $5.6 million, a meaningful share of the roughly $15 million year-over-year revenue increase. Management also acknowledged that lower points-promotion costs and particularly strong rental revenue helped, and warned that growth 'may fluctuate in the short term.'
The underlying network trends are healthy but steadier than the headline suggests:
- Locations reached 293, up 36 year over year.
- Trailing-twelve-month visits rose 9% to 7.06 million, a touch slower than the second quarter's 10%.
- Average spend per visit rose 4%.
- Same-clinic revenue improved from slightly negative in 2025 to +7% through nine months, though part of that comes from strategic price increases.
Related-party revenue from the supported medical corporations still makes up about $53.5 million of the $58.6 million total. That concentration is worth keeping in view.
The forward story is now more concrete, though largely longer-dated. Management outlined several initiatives:
- **AI:** a NeuroBrain Dynamics alliance to build a local LLM foundation, six named AI tools such as auto-charting and shift scheduling, and the Atomic Software partnership for clinic systems.
- **Longevity:** a dated roadmap running from biomarker testing in November 2026, to a longevity center in 2027, with meaningful revenue not expected until 2028.
- **United States:** SBC-branded U.S. clinics are possible within six to 12 months, and OrangeTwist is targeting eight to 10 new sites.
Management also cited competitor exits in Japan and said there is 'big room' for further margin expansion. No formal numeric guidance was issued, however.
Capital allocation remains a source of frustration. Cash stood at $198 million at quarter-end, which management described as now above $200 million, and nine-month operating cash flow swung to $50 million from a $27 million outflow. Even so, management explicitly ruled out additional buybacks, preferring M&A and de novo clinics. Governance concerns persist as well: the CEO holds roughly 80% of shares, and independent director appointments are still pending.
The market had already moved ahead of the report. Shares rose 63.8% from the $3.26 open after the August release to $5.34 heading into this report. That leaves the stock about 35% above its 200-day moving average and only 7.8% below the 52-week high of $5.79 set on October 23. Investor sentiment improved substantially over the period, from clearly negative (-0.44) to roughly neutral (+0.01). Price, momentum and AVWAP trend readings are positive, while sequential growth still reads negative. The setup is therefore more complicated than the surprise implies: the stock entered earnings near the top of its range, and expectations had reset upward.
The bottom line is that SBC Medical produced a genuine operating inflection, with surging margins, recovering same-clinic sales and a credible expansion agenda. But a meaningful part of the 35% growth came from fee revisions, the Waqoo consolidation and favorable one-off items, and net income lagged operating income. With shares up sharply and sentiment already repaired, the next test is whether organic growth and margins hold once these one-time tailwinds lap, while governance and the refusal to return cash give bears legitimate ammunition.
Read our earnings preview for SBC Medical Group Holdings Inc.: https://www.earningswhispers.com/article/SBC/23047
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 13 hours | |
| 14 hours | |
| 16 hours | |
| 16 hours | |
| Nov-08 | |
| Nov-05 | |
| Nov-03 | |
| Nov-02 | |
| Oct-22 | |
| Oct-12 | |
| Sep-25 | |
| Sep-10 | |
| Sep-01 | |
| Aug-27 |
