Beasley Misses On EPS As Revenue Recovery Stalls; Deleveraging And Digital Margins Are The Only Bright Spots
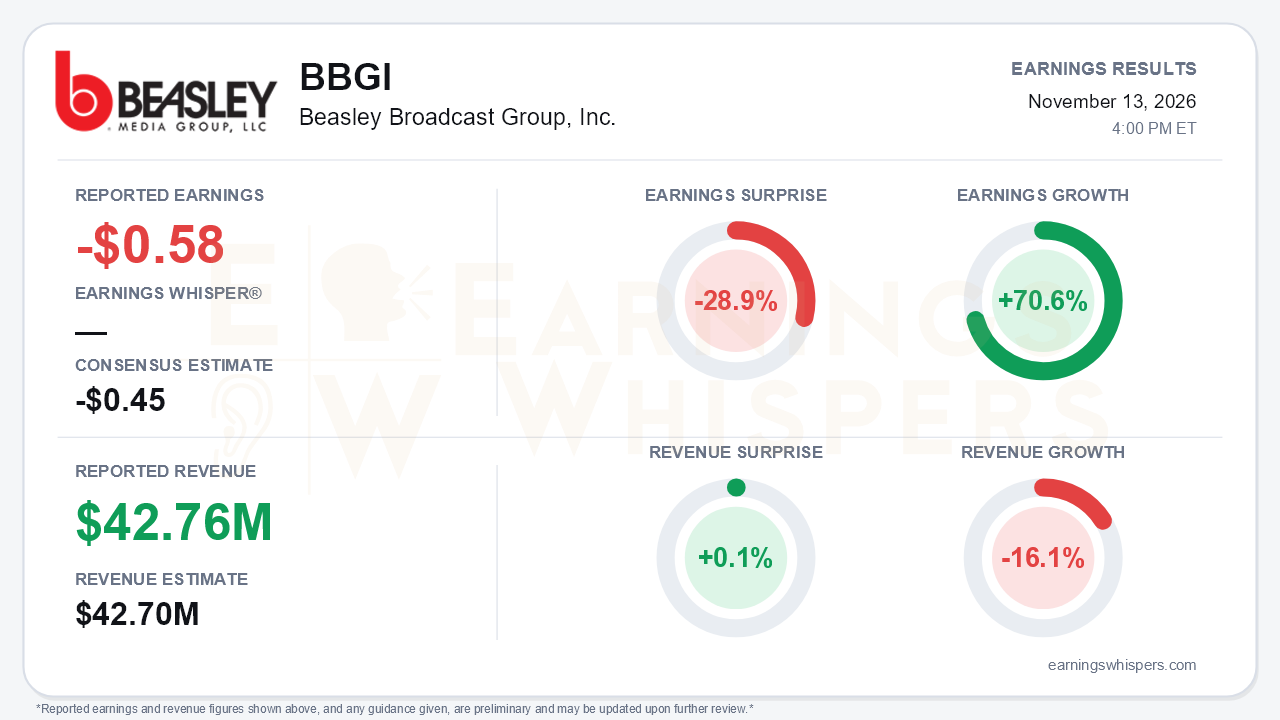
Beasley Broadcast Group reported a third-quarter loss of $0.58 per share, missing the consensus estimate of -$0.45 by 28.9%. Revenue of $42.76 million essentially matched the $42.7 million consensus, a 0.1% beat, but fell 16.1% from a year ago. On the normalized basis, the loss narrowed, and earnings improved 70.6% year over year. That improvement owes more to a smaller debt load than to the operating business. The central tension is that Beasley has largely fixed its balance sheet while its revenue base kept eroding faster than management said it would. Interest expense fell to $1.3 million from $3.3 million after the May restructuring, yet the radio and digital franchise that has to service the remaining capital structure lost ground.
The quality of the quarter deserves scrutiny. On a GAAP basis, Beasley lost $6.51 per share, or $12.1 million, versus $1.97 a year ago. The GAAP figure includes a $13.1 million FCC license impairment, partly offset by a $2.0 million gain on dispositions. The call analysis cites a $6.4 million impairment, which does not match the $13.1 million in the release's income statement. Investors should rely on the filed figure until the gap is explained.
Adjusted EBITDA was $1.3 million. That compares with $3.9 million a year earlier and $5.3 million in the second quarter, even though station operating expenses fell about $7 million, or 15%. Corporate expense rose to $3.9 million on restructuring and transaction costs. Nine-month operating cash burn widened to $15.4 million from $5.3 million. The nine-month GAAP profit of $75.4 million is almost entirely the $91.8 million gain on debt restructuring and says nothing about operating health.
The call made the deterioration explicit. On the second-quarter call, management guided third-quarter same-station revenue down mid-single digits. The actual decline was 10%. The weakness showed up across the business:
- **Digital revenue:** Same-station digital revenue fell 12%. That reverses a growth streak of +33% in Q4 2025, +18% in Q1 and +7% in Q2, so the segment pitched as the growth engine is now shrinking.
- **Agency channels:** Local agency revenue fell 22%, worse than the 12% decline in Q2. National revenue excluding political fell 18%. Management expects both to keep declining into 2027.
- **Local direct:** This was the healthiest channel at +7% same-station, but it slowed from +9%.
- **Political advertising:** Management had touted presidential-cycle booking cadence. The cycle now totals only about $4.2 to $4.5 million, with Michigan the only target market that delivered meaningfully.
The tone shifted accordingly. In Q2, management said the machine was built and now producing. This quarter, it acknowledged it is not satisfied with the pace of revenue recovery.
The positives are real but narrower. Digital operating margin reached a record 32%, versus 21% reported (26% same-station) a year ago, and digital operating income rose to $3.1 million despite lower digital revenue. That is cost discipline rather than demand, however. Other operating bright spots were limited:
- Gaming revenue grew 17% to about $3 million.
- Import auto dealers rose 13%.
- Ratings share improved 3% after a 5% sequential decline in Q2.
The financing and asset actions were more consequential. A $4.6 million equity raise in September and more than $10 million from selling two stations and two real-estate parcels cut first-lien principal to about $3.6 million. Long-term debt on the balance sheet fell to $32 million from $235 million at year-end. New initiatives include a multi-year Vegas Golden Knights audio partnership, with early ad response above expectations, and the Futuri AI sales platform.
Bears have legitimate ammunition on several fronts:
- The equity raise adds dilution on top of the at-the-market program.
- Working capital stands at a $95 million deficit.
- The release's risk factors include going-concern and Nasdaq listing-compliance language.
- The outlook is soft. Fourth-quarter same-station revenue is guided up only low-to-mid single digits including $2.8 million of political, slightly down excluding it, and full-year 2026 is pacing down mid-single digits. On the Q2 call, management had described Q4 pacing as "very strong."
The market had already priced in much of this damage. Shares closed at $5.63 the day before the report. That is 75% below the $22.49 open following the August release and 79.7% below the inter-earnings high of $27.70, set that same day. The stock sits 59.6% under its 200-day moving average and just 7.2% above the inter-earnings low of $5.25, set November 10.
Investor sentiment improved to -0.79 from -1.0, the most negative possible reading. That leaves sentiment deeply negative but slightly less uniformly bearish, consistent with a stock that has already absorbed severe losses. Price and AVWAP trends remain negative, while sequential growth and momentum readings are neutral.
The bottom line is that Beasley has bought time, not a turnaround. The debt restructuring, asset sales and cost cuts have shrunk interest expense and made digital meaningfully more profitable. However, the quarter showed revenue falling twice as fast as guided, digital growth reversing, political underdelivering and EBITDA collapsing sequentially. Until local direct gains and new sales tools can offset accelerating agency and national declines, the improved balance sheet is a cushion rather than a catalyst.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-13 | |
| Nov-13 | |
| Nov-12 | |
| Sep-29 | |
| Sep-28 | |
| Sep-14 | |
| Aug-13 | |
| Aug-12 | |
| Aug-11 | |
| Aug-09 | |
| Aug-03 | |
| May-13 | |
| May-07 | |
| May-01 | |
| Apr-29 |
Beasley Broadcast Group Announces Expiration of Exchange Offer, Tender Offer and Consent Solicitations and Receipt of Valid Consents from 100% of Outstanding Existing First Lien Noteholders to Proposed Amendments to Existing First Lien Notes Indenture and Acceptance of 99.53% of Outstanding Existing Second Lien Notes
BBGI -13.71%
PR Newswire
|
