Presidio Misses Estimates As Canyon Creek Volume Growth And A Dividend Hike Run Into Shrinking EBITDA
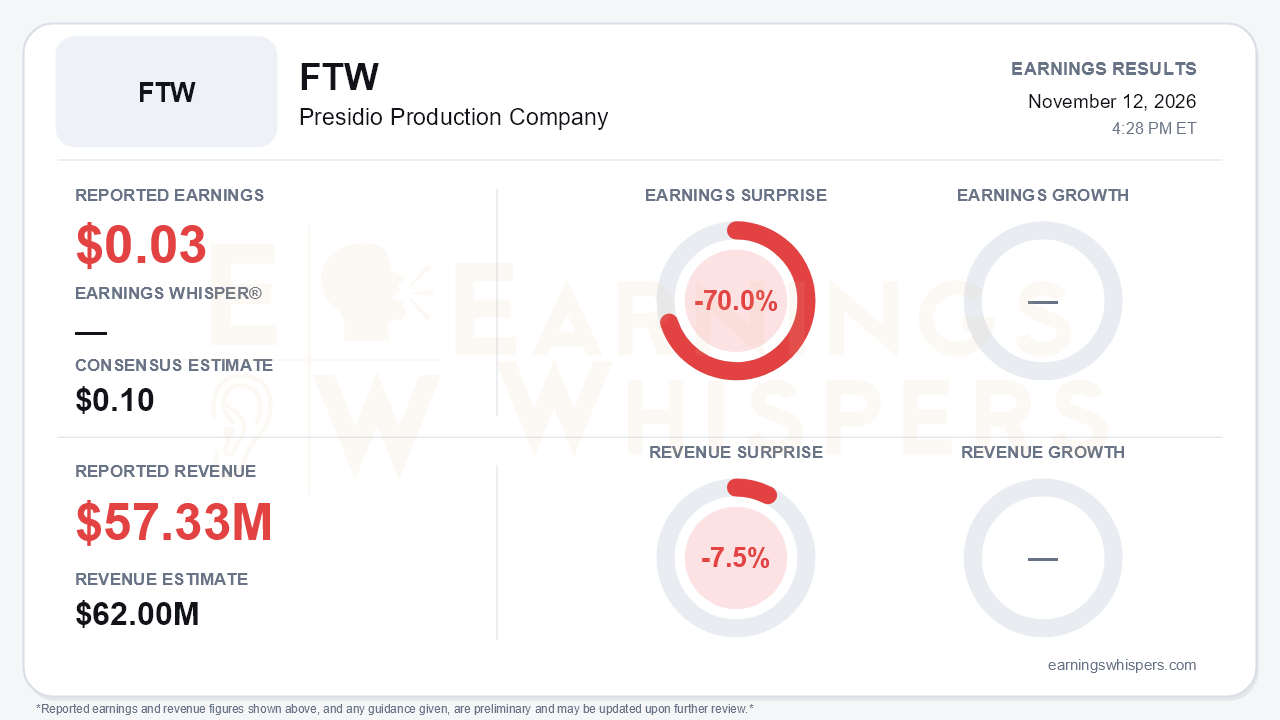
Presidio Production Company (NYSE: FTW) missed on both earnings and revenue in its third quarter, the first full quarter to include the Canyon Creek acquisition. Earnings of $0.03 per share fell 70.0% short of the $0.10 consensus. Revenue of $57.33 million missed the $62.0 million estimate by 7.5%. Year-over-year growth comparisons are not meaningful because the company's March business combination split its reporting into predecessor and successor periods. The quarter-over-quarter story is clear, though. Presidio bought volume and raised its dividend, but cash earnings moved the wrong way. That is the central tension: the acquisition-and-optimization machine is visibly working at the operating level, yet the financial output per barrel is shrinking.
The quality of the quarter deserves scrutiny. Production rose 15% sequentially to 26.1 MBoe/d, with Canyon Creek driving most of the increase. Revenue, however, grew only 6%, to $57.3 million from $54.0 million, which implies meaningfully weaker per-unit realizations. Natural gas makes up 58% of the production mix, and it realized just $1.46 per Mcf before hedges. Derivatives lifted that to $3.51, and the total realized price rose from $23.72 per Boe to $25.49 including hedges. The hedge book also cut the other way: oil realizations fell from $82.60 to $60.02 per barrel after settlements.
Adjusted EBITDA declined to $29.1 million from $33.2 million in the second quarter. Adjusted unhedged EBITDA slipped to $24.8 million from $26.3 million. Management had guided to slightly under $30 million in August, so the drop was telegraphed, but a 15% production gain still produced lower EBITDA.
The GAAP picture is far uglier. Presidio posted a net loss attributable to the company of $46.4 million, or $1.80 per Class A share. The loss was driven by a $66.5 million non-cash, unrealized derivative loss as commodity prices rose. That mark did not consume cash, but it is a reminder that heavy hedging caps upside when prices move higher.
Beneath the headline, operations improved on nearly every axis management controls:
- **Operating costs:** Lease operating expense fell to $9.10 per Boe from $9.39 in Q2 and $9.47 in Q1. Management projects Canyon Creek LOE down roughly 32%.
- **AI production uplift:** Contribution from the Asset Intelligence programs climbed to 3.2%, from 2.3% in Q2 and about 1% in Q1. Management cited roughly 4% exit-rate potential and called its 3-5% 2026 target "very conservative."
- **Workovers:** Completed wedge workovers rose to 37 from 25, delivering 8% more barrels at 13% less cost.
- **Well reactivations:** AI-identified shut-in wells are coming back online, with the first restarted in October and ten more expected by year-end.
The call preserved a credible operational story. It did not, however, raise the financial framework: the $90 million nine-month EBITDA figure was reaffirmed rather than lifted.
Catalysts are real but incremental. The dividend increase to $1.50 annualized from $1.35 delivers on a promise from the prior two calls and represents a yield near 15% at the current price. Leasehold sales have reached $17.0 million year-to-date, including $7.1 million already booked in the fourth quarter. These sales sit outside guidance, and Arkoma acreage monetization is just beginning. A $4.3 million working-interest bolt-on in Arkoma signals the land-and-expand strategy is active. Management also noted that debt is effectively fixed at a blended rate of about 6.6%.
Bears have legitimate ammunition on the balance sheet, however:
- **Leverage:** Leverage edged up to 2.8x from about 2.7x pro forma, on net debt of $349.4 million.
- **Credit line:** The RBL borrowing base is expected to fall to roughly $45 million from $60 million at the winter redetermination.
- **Liquidity:** Total liquidity sits at about $97.4 million.
- **Deal flow:** Despite second-quarter language suggesting a deal could come in "short order," no new large acquisition was announced, even as management still describes a pipeline of roughly $17 billion.
For a yield vehicle whose growth depends on consolidation, a stalled deal cadence combined with a richer dividend and declining EBITDA narrows the margin for error.
Investors appear to have been leaning in that direction. Earnings Whispers sentiment moved from essentially neutral at 0.03 to a clearly negative -0.19 heading into the report. Shares at $10.22 are down 10.3% from the $11.39 open after the August report and sit 8.2% below the 200-day moving average of $11.14. The AVWAP trend reading is also negative. The market has been discounting the dividend story rather than rewarding it, and this report offered little in the financials to reverse that.
The bottom line is that Presidio executed operationally but missed financially. Production, unit costs and AI-driven uplift all improved, and the dividend went up as promised. But earnings and revenue fell short, EBITDA declined sequentially, leverage ticked higher and credit capacity is set to shrink. Until EBITDA growth catches up with volume growth, or the next sizable acquisition materializes, the higher payout will be judged against a thinner cushion.
Read our earnings preview for Presidio Production Company: https://www.earningswhispers.com/article/FTW/23016
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-13 | |
| Nov-12 | |
| Nov-07 | |
| Nov-04 | |
| Oct-27 | |
| Aug-11 | |
| Jul-31 | |
| Jul-23 | |
| Jul-22 | |
| Jul-08 | |
| Jul-02 | |
| Jun-18 | |
| Jun-09 | |
| May-14 | |
| May-08 |
