Arrive AI's First Revenue Step-Up Is Overshadowed By Thin Cash, A Forced Reverse Split, And Open-Ended Dilution
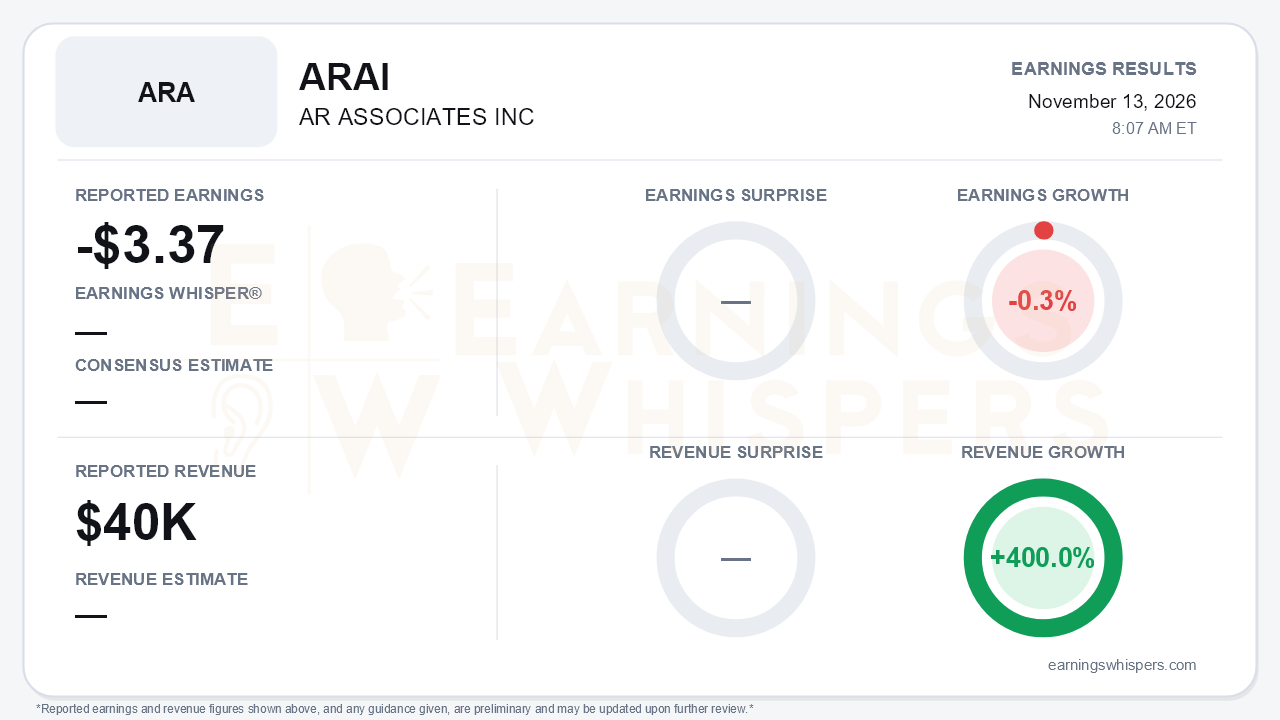
Arrive AI (NASDAQ: ARAI) reported a third-quarter loss of $3.37 per share on revenue of $0.04 million. There was no consensus estimate or Earnings Whisper, so the quarter cannot be judged as a beat or a miss. On Earnings Whispers' normalized basis, earnings fell 0.3% year over year, which is essentially flat. Revenue grew 400.0%.
The company's own per-share comparison looks better: the loss narrowed from $6.39 to $3.37 after restating for the 1-for-48 reverse split. That improvement owes as much to a larger weighted share count as to operating progress. The headline revenue growth is real but tiny in absolute terms. The central tension is that Arrive AI finally showed a measurable revenue step while its balance sheet moved closer to the edge.
The quality of the quarter deserves scrutiny.
- **Revenue mix.** Revenue of $39,700 compared with $7,450 a year ago and $14,700 in the second quarter. Per the call, however, $25,000 of that was installation fees tied to Hancock Regional Hospital's expansion to its Parkway Building. Subscription revenue was $14,700, the same as the prior quarter and in line with roughly $15,000 in each of the three quarters before that. The recurring base, which is what the CEO says the company must now build, did not grow.
- **Operating costs.** Total operating expenses nearly doubled to $3.3 million from $1.7 million, driven by general and administrative expense rising to $3.0 million from $1.4 million. That happened despite an August reduction in force.
- **Net loss.** The net loss improved to $3.7 million from $4.4 million only because the loss on convertible-note conversions shrank to $0.3 million from $3.3 million. Operationally, the loss widened.
Liquidity is the dominant issue. Cash and equivalents ended September at $1.05 million, plus $0.97 million of investments. Management cited about $5.1 million at the end of June and $8.5 million at the end of March. Nine-month operating cash burn was $9.7 million, almost exactly offset by $9.7 million of financing inflows. Since quarter-end the company raised $250,000 privately and $1.3 million through its at-the-market program. Management is targeting monthly burn of about $1 million or less in the fourth quarter, an improvement from the $1.1 million cited last quarter.
Even so, the runway language has shortened. It is now 'through end of year and into 2027', versus 'into 2027 and beyond' in the first quarter. About $4 million remains outstanding under the Streeterville convertible agreement. The CEO told investors to 'embrace the dilution', which is a candid acknowledgment that equity issuance is the operating plan, not a contingency.
Credibility also took a hit.
- The reverse split came after management said late last year that one was not expected soon. It also followed second-quarter assurances that the company was not at risk of running out of funds.
- Nasdaq's bid-price deficiency remains open pending ten trading days above $1.
- The tone has shifted from scaling to survival discipline.
The call did preserve a credible narrative about pipeline breadth, though nearly all of it is pre-revenue. Positives included:
- AP3 Plus began shipping October 7, and the fleet stands at 16 units, versus the 'more than a dozen' guided last quarter.
- The company completed its first commercial office and first residential installations.
- Arrive AI made a strategic investment in Ottonomy alongside an agreement contemplating up to 50 ground robots at Arrive Point locations.
- It hired a first Chief Revenue Officer and formed a Defense Division, with talks involving more than 12 countries and potential non-dilutive funding.
- Management set a 2027 target of about 105 Arrive Points.
Bears have legitimate ammunition on conversion, however:
- The LifeSpan Pharmacy, DXC Technology, Modovolo, and Purdue initiatives carry no revenue commitments, as the release itself states.
- AvRide pilots and Fortune 500 pharma discussions flagged last quarter have not become firm deals.
- SOC 2 security reviews are lengthening enterprise sales cycles.
- The pricing model is still being tested across subscription, revenue-share, and pay-per-delivery structures.
A 105-unit target is ambitious against a 16-unit fleet and a cash balance that must be replenished through stock sales.
Market context is limited. No sentiment readings or current price were available. The supplied price data straddle the reverse split: the $0.23 open after the August report is a pre-split quote, while the $26.80 200-day moving average reflects split-adjusted history. Neither offers a clean read on how investors are treating the stock today. What is clear is that the reverse split was needed to defend the listing, which says enough about how the market treated the shares during the quarter.
The bottom line is that Arrive AI delivered its best revenue quarter to date, a wider partner funnel, and a tighter cost posture. However, the revenue jump was driven by one-time installation fees, recurring subscriptions were flat, and operating losses widened. The company's survival now depends on continuous dilutive financing while unproven partnerships try to become contracts. Until subscription revenue grows and cash burn visibly falls toward management's target, the balance sheet rather than the pipeline is likely to set the terms of the investment debate.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 15 hours | |
| Nov-11 | |
| Nov-11 | |
| Nov-10 | |
| Nov-09 | |
| Oct-30 | |
| Oct-29 | |
| Oct-27 | |
| Oct-22 | |
| Oct-20 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-07 |
