Bending Spoons Must Bridge A Full-Year Gap The Street Hasn't Yet Closed
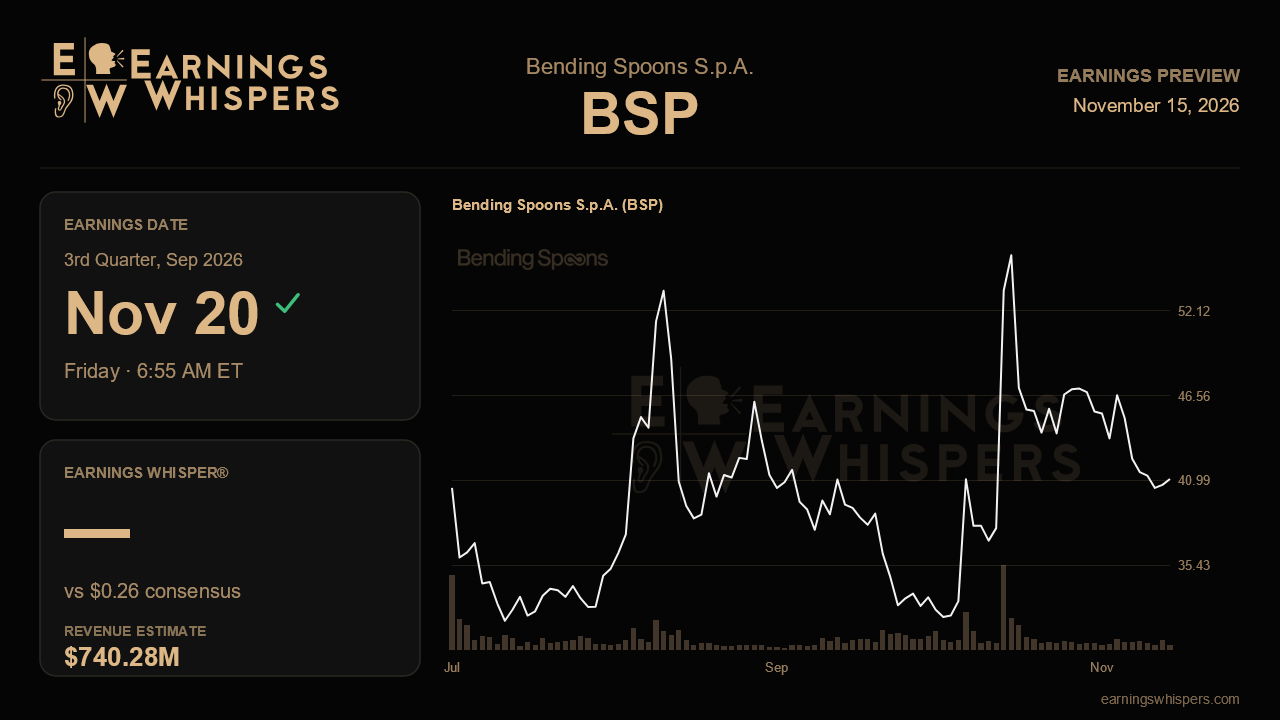
Bending Spoons heads into its third-quarter report with an awkward mismatch hanging over it. Management's own full-year revenue outlook of $2.78 billion to $2.82 billion sits well below the roughly $2.88 billion analysts were penciling in when the guidance was issued. When a company guides below the Street and the Street does not fully adjust, the next report becomes a referendum on who is right. That is the setup going into the November 20 release before the opening bell.
For the quarter itself, the bar looks reasonable. Consensus calls for revenue of about $740.3 million, just above the $739 million midpoint of management's $733 million to $745 million range. Analysts are not betting on an aggressive beat, and the company would need only a modest overshoot to clear expectations. Revenue at that level would be roughly 5% above the $704.2 million posted last quarter, a healthy sequential step that suggests the top line is still moving in the right direction even if the annual target came in lighter than hoped.
Earnings are where the picture gets more complicated. Consensus calls for $0.26 per share, down sharply from the $0.46 reported last quarter despite higher expected revenue. A drop of that size on a rising top line implies analysts expect meaningfully heavier costs, lower margins, or some combination of the two. The report needs to explain that gap. If the decline reflects deliberate spending that management can tie to future revenue, the market may look past it. If it instead points to margin erosion that the company did not clearly flag, it will raise harder questions about the quality of the growth. A result closer to the prior quarter's profitability would be a genuine upside surprise, while a figure at or below consensus without a clear explanation would reinforce the cautious tone of the guidance.
The more consequential number may be the full-year outlook. Because the Street's annual estimate ran about $60 million to $100 million above management's range, whatever the company says about the fourth quarter will determine whether analysts finally fall in line or keep pushing for more. Reaffirming the range would effectively ask the Street to cut its numbers. Nudging the range higher would vindicate the more optimistic estimates. Narrowing toward the low end would confirm that the negative guidance was not mere conservatism. With little in the way of detailed commentary from the prior call to anchor expectations, the guidance language this time carries unusual weight.
The stock has already absorbed some of that disappointment. Shares have fallen 12.3% since the last report, trailing the S&P 500 by nearly 10 percentage points. At $41.08, the stock sits in the lower half of its post-earnings range of $31.43 to $59.50, having bounced well off the low but still far from the high. It also remains well above its 200-day moving average of $23.45, a reminder that the longer-term trend has been strongly favorable even as the recent tape has turned against it. Sentiment has edged from slightly bearish before the last report to slightly bullish now, though both readings sit close to neutral. That suggests investors are less defensive than they were, but hardly enthusiastic.
The central issue is credibility of the annual trajectory. Hitting the quarterly revenue range is the minimum requirement. What will determine whether the story holds together is whether management can show that profitability is dipping for reasons it controls and whether the fourth-quarter outlook closes the distance between its own forecast and the Street's. A clean quarter paired with a firmer full-year view would give the recent selloff room to reverse; another cautious outlook would likely force estimates, and perhaps the stock, lower.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-16 | |
| Nov-16 | |
| Nov-16 | |
| Nov-16 | |
| Nov-16 | |
| Nov-16 | |
| Nov-15 | |
| Nov-12 | |
| Nov-06 | |
| Nov-06 | |
| Nov-06 | |
| Nov-05 | |
| Oct-28 | |
| Oct-27 |
