NTIC Must Prove Raw-Material Squeeze Was Temporary As Record Sales Meet A Profit Test
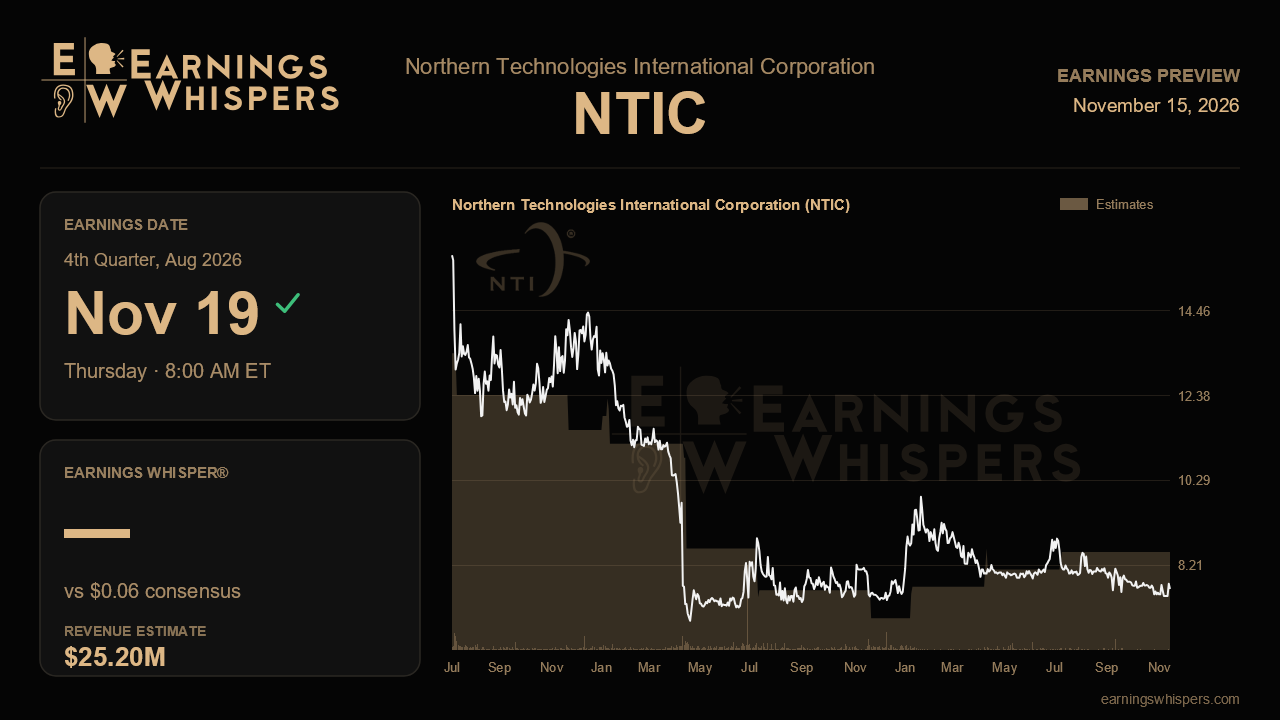
Northern Technologies has spent most of fiscal 2026 proving it can grow again. Now it has to prove it can make money doing it. The specialty chemicals company posted a record $24.2 million in sales last quarter, its second straight double-digit gain, yet still slid back into a loss after a spike in polyethylene prices tied to shipping disruption near the Strait of Hormuz cut roughly $1 million from gross profit. Management described that hit as temporary and external, and promised that the fiscal fourth quarter would be the strongest of the year with margins recovering. This report is where that promise either holds or falls apart.
The Street is taking management at its word. Consensus calls for earnings of $0.06 per share on revenue of $25.2 million. That compares with a loss of $0.06 a year ago and implies revenue growth of about 12.9%, which would extend the run of double-digit gains rather than mark an acceleration. On the top line, the bar looks reachable, since it requires only a modest sequential step up from last quarter's record. The bottom line is the harder ask. Moving from a loss of a few cents to a solid profit in one quarter leaves little room for another round of input cost pressure, so the earnings estimate is effectively a bet on margin repair.
Gross margin is the number that matters most. It slid from 36.0% in the first quarter to 35.7% in the second and then to 33.6% last quarter, well below the 38.4% posted a year earlier. A rebound back toward the mid-30s would support the view that the polyethylene shock was a passing event rather than a new cost baseline. A margin stuck near last quarter's level would suggest either that resin costs have stayed elevated or that NatureTech's commodity lines, such as bag liners and cutlery, are facing price competition severe enough to erode profitability no matter what happens to raw materials. Operating expenses, which management held to 42.0% of sales last quarter, give the company some leverage if gross profit cooperates.
The oil and gas business is the other key piece. Xeros oil and gas sales rose 72% from a year earlier last quarter and passed $10 million on a trailing twelve-month basis for the first time, helped by the Brazil FPSO contract. Yet sales fell sequentially to $2.2 million from $2.7 million because of shipping delays, a result management called disappointing. Management also said large projects had already been invoiced in June, which falls in the current quarter. That makes oil and gas the most visible test of management's credibility. A strong number would confirm that last quarter's dip was only a matter of timing. A soft one would raise doubts about how lumpy this growth engine really is. The joint ventures, where sales rose 15% last quarter and Europe showed early signs of stabilizing, need to keep contributing as well. The balance sheet deserves a look too. Revolver borrowings rose to $11.8 million despite the company's stated priority of paying down debt, so better cash generation in a seasonally strong quarter would help ease that concern.
Sentiment has warmed noticeably, rising to about 22% bullish from close to neutral heading into the last report. The stock has not followed. Shares have fallen 6.3% since the last release while the S&P 500 gained 1.3%, and at $7.75 they sit near the bottom of their post-earnings range of $7.40 to $8.74, below last quarter's low. The market appears to be withholding credit until margins actually recover.
That is the central question. Demand has largely done its part. If gross margin rebounds and the June oil and gas invoices produce a clean profit, the narrative of growth followed by operating leverage is back on track. If margins stay stuck, the record sales will look less like a turning point and more like a company running harder just to stay in place.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-12 | |
| Sep-08 | |
| Jul-09 | |
| Jul-09 | |
| Jul-09 | |
| Jul-08 | |
| Jul-02 | |
| Jun-16 | |
| Apr-28 | |
| Apr-09 | |
| Apr-09 | |
| Apr-02 | |
| Mar-06 | |
| Jan-20 |
