Moog's Fiscal 2027 Outlook Must Prove Its Raises Aren't Built On One-Time Gains
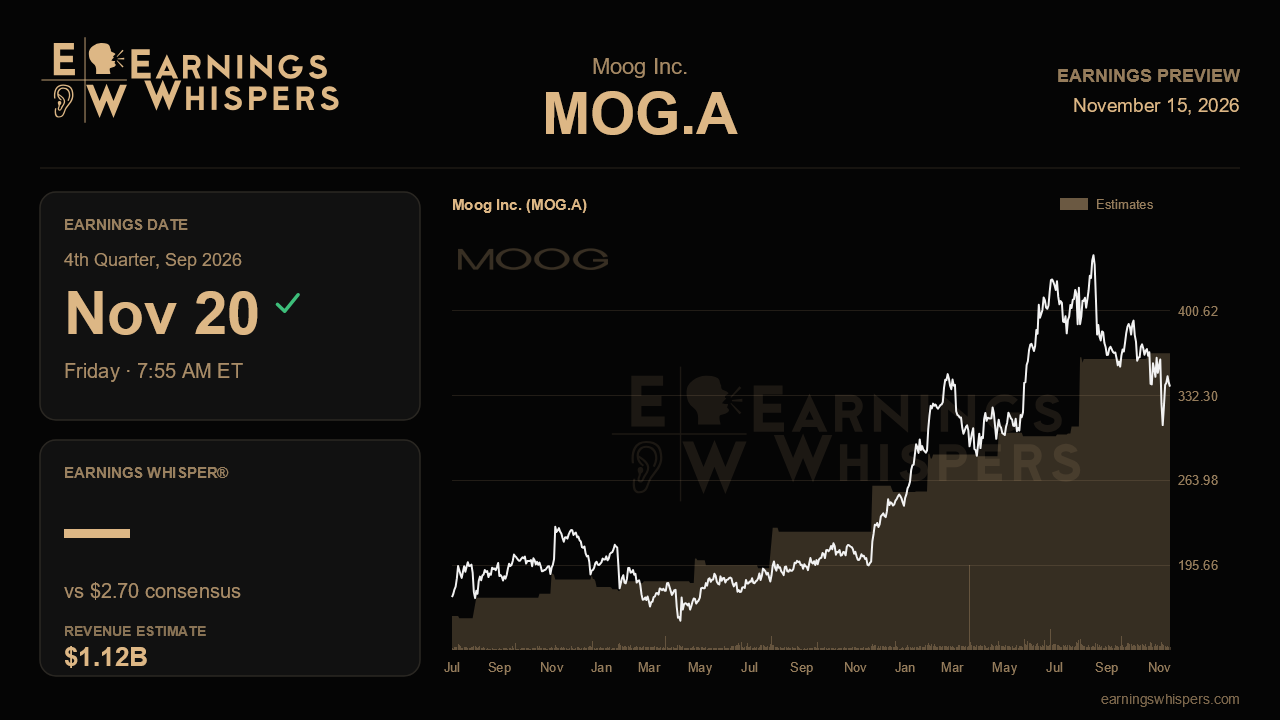
Moog arrives at its fiscal fourth-quarter report with a strange disconnect. Management has raised its full-year outlook four straight times, most recently lifting adjusted EPS guidance to a range of $11.55 to $11.75, yet the stock has fallen 16.1% since the last report while the S&P 500 edged up 1.3%. The market seems to be asking a pointed question: how much of the recent momentum is durable operating improvement, and how much came from a one-time tariff refund and tax credit that will not repeat?
For the September quarter, analysts expect EPS of $2.70 on revenue of $1.12 billion, which would be growth of 5.5% and 6.8%, respectively. That is a noticeable slowdown from the 15% sales growth Moog posted in its record third quarter, and revenue would be flat sequentially. The bar looks modest, but context matters. The prior quarter's $3.72 included roughly $0.70 from a $30 million IEPA tariff refund, plus a $35 million R&D tax credit, so a big step down in EPS is expected rather than alarming. The full-year consensus of $10.68 sits well below management's range. That gap suggests some analysts either have not updated their models or are deliberately stripping out the nonrecurring benefits. Either way, the reported figure for the year will likely land near guidance, and the cleaner test is what underlying margins look like without the refund.
This report also kicks off fiscal 2027. A year ago, Moog's initial outlook called for $10.00 in EPS and was raised steadily from there, so the starting point for next year will show how much confidence management really has. Three operating stories will shape it. The first is data center cooling, where guidance climbed from about $50 million early in the year to roughly $100 million, nearly four times fiscal 2025. Capacity now runs around 1,300 pumps a week across three lines, and a next-generation in-row pump is being qualified for fiscal 2027 production. Evidence that the business is adding customers beyond its single hyperscaler, reached through two CDU makers, would ease the most obvious concentration risk. The second is missiles, guided to about $275 million this year. Lockheed's seven-year framework agreements, worth roughly $100 billion, have not yet flowed into Moog's backlog. Any sign that the step-up is being booked would turn a talking point into hard numbers.
The third story is backlog. Growth in 12-month backlog slowed to 23% in the third quarter from 33% the quarter before. That is still robust, but another sharp deceleration would sit awkwardly beside management's description of a generational inflection in defense demand. Beyond that, investors will want an update on the MV75 program, where Textron is self-funding under not-to-exceed caps and Moog has limited visibility into the early part of calendar 2027. A clearer read on the commercial aircraft inventory timing that trimmed this year's outlook would also help. Steady cash generation that supports the lifted 70% free cash flow conversion target, along with leverage holding near 1.5 times, would reinforce management's newfound readiness for larger bolt-on deals.
Sentiment has warmed considerably, with the bullish reading jumping to 67.8% from 24.6% ahead of the prior report, even as the share price slid. At $339.51, the stock trades below its 200-day moving average of $355.38. It sits much closer to its post-earnings low of $305.81 than its high of $448.85. That leaves room for relief if the outlook impresses, but also signals lingering skepticism.
Ultimately, the quarter itself matters less than the fiscal 2027 framework. If Moog can guide to earnings growth on a base that excludes this year's one-time gains, while showing data center diversification and early missile bookings, the case for durable momentum stays intact. A cautious starting point that leans on this year's inflated base would confirm the market's doubts.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-15 | |
| Nov-13 | |
| Nov-03 | |
| Oct-02 | |
| Sep-02 | |
| Aug-14 | |
| Jul-31 | |
| Jul-31 | |
| Jul-15 | |
| Jul-06 | |
| Apr-25 | |
| Apr-24 | |
| Apr-24 | |
| Apr-24 | |
| Apr-16 |
