Semtech's Data Center Surge Faces A Bar Set Above Its Own Raised Guidance
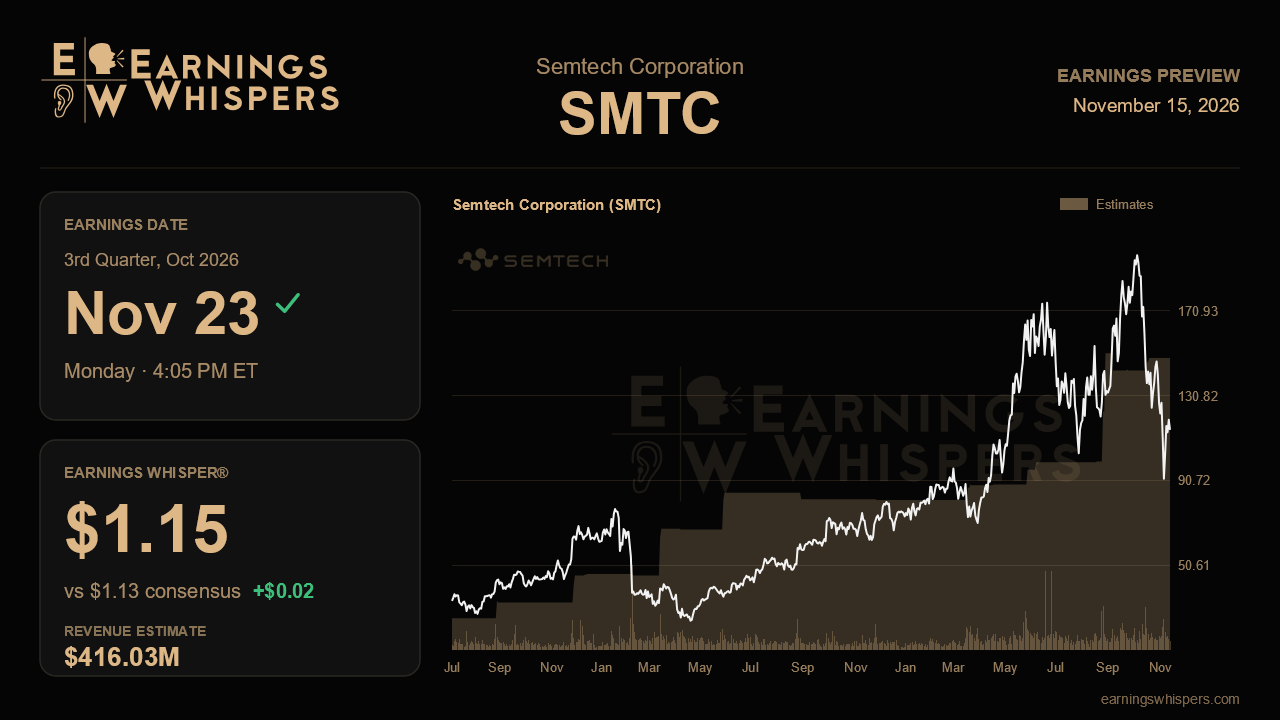
Semtech enters its fiscal third-quarter report with an unusual mismatch. Management's last call was easily its most confident in a year, with data center sales inflecting, margins stepping up and next year's revenue largely booked. Yet the stock has fallen 12.5% since that report, trailing the S&P 500 by about 11 percentage points. The results due after the close on November 23 will show whether the business is keeping pace with the story, and whether the market's skepticism is about execution or about something the numbers cannot fix.
The Street is asking for a lot. Consensus calls for non-GAAP earnings of $1.13 a share on revenue of $416.0 million, which would be growth of nearly 56% from the $267.0 million reported a year ago. Both figures sit above management's guidance of $1.02 to $1.08 a share on revenue of $405 million to $415 million. In other words, analysts are not just expecting Semtech to hit the top of its range. They expect it to clear the range. The Earnings Whisper of $1.15 is only slightly above consensus, but it points the same way. A result at the midpoint of guidance, which would normally count as solid, could be read as a letdown.
That bar follows a run of upward revisions. Each of the past several quarterly guides came in higher than the one before. The company went from targeting $283 million in its fiscal first quarter to $328 million in the second and now about $410 million, well above last quarter's $341.9 million. The engine is data center. Sales there reached a record $100 million last quarter, and management guided for roughly 45% sequential growth this quarter, a faster pace than the 35% it had projected a quarter earlier. The most important thing to confirm is that this acceleration showed up as promised, especially in 1.6T fiber edge products. Management said that business was ramping earlier than it had modeled and is aiming for more than half of that market by fiscal year-end.
Margins are the second test. Semtech guided consolidated gross margin to about 58.3%, up from 54.5% last quarter, and adjusted operating margin to around 31%, up from 24.4%. That margin expansion explains most of the gap between modest revenue upside and a much larger jump in earnings. The pending sale of the cellular module business, expected to close in the fiscal fourth quarter, should lift gross margin further, since the remaining business ran near 64%. Results that fall short on margin would raise doubts about how much of the improvement comes from mix and how much from the divestiture.
Other threads matter too. LoRa, the wireless IoT franchise, posted a record $58 million last quarter, and management walked away from its earlier expectation of roughly 20% growth. Another strong quarter would support that more ambitious view. High-end consumer, the one soft spot, is unlikely to change the picture. Capacity may be the real swing factor. Management warned that the supply it has secured may not cover the second half of fiscal 2028, and that capital spending could rise, possibly including wafer prepayments. Comments on foundry and packaging capacity, and on how spending will be paced, will shape how investors value the claim that more than 70% of next year is already booked.
Sentiment has barely moved from last quarter and remains moderately bullish. The stock tells a cooler story. At $114.59, shares sit below their 200-day moving average of $126.30 and in the lower part of a wide post-earnings range of $90 to $202. The question is not whether demand exists, since management said supply is now the main constraint. It is whether Semtech can deliver above-guidance revenue and the promised margin step-up while showing it can secure enough capacity to keep the ramp going into next year.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-15 | |
| Nov-09 | |
| Nov-09 | |
| Oct-24 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 |
