PennantPark Investment Needs JV Savings To Show Up As Dividend Gap And NAV Slide Persist
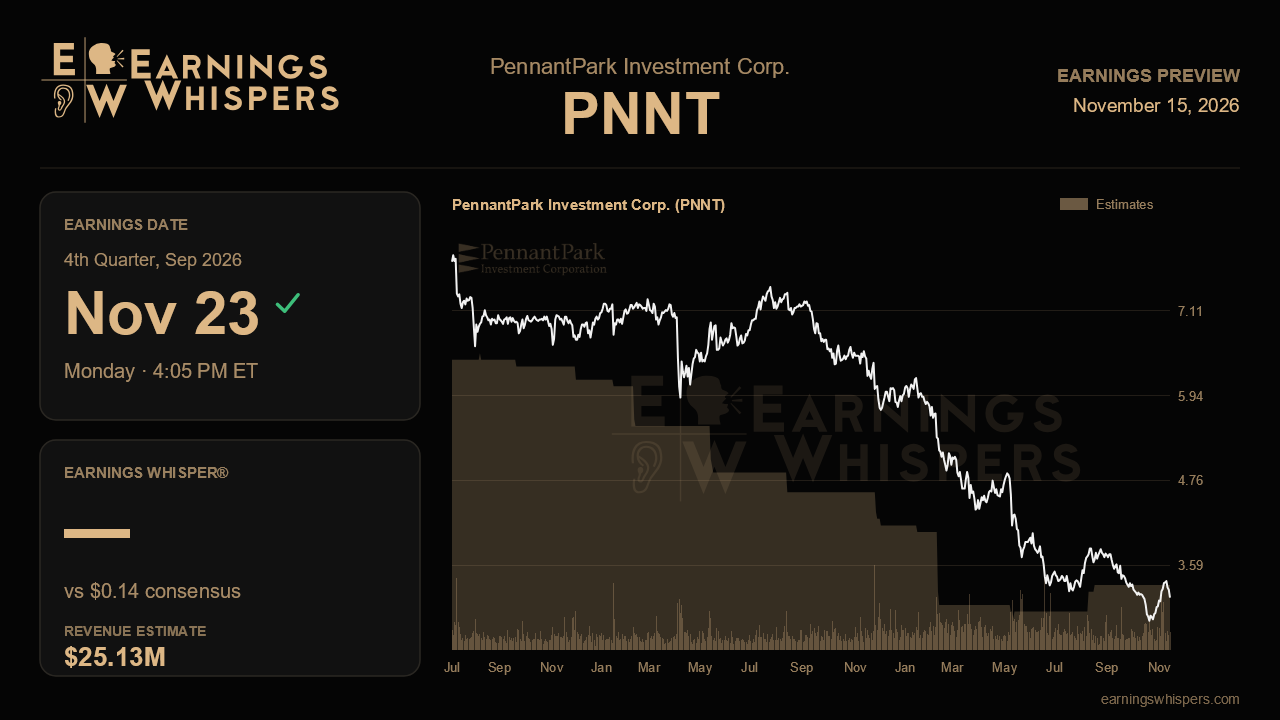
PennantPark Investment heads into its fiscal fourth-quarter report with a story that sounds better on the conference call than it looks on the balance sheet. Last quarter management pointed to cheaper funding at its joint venture, a lucrative defense equity exit and a warming deal market as signs that earnings momentum was turning. The stock has fallen 16.7% since then, trailing the S&P 500 by about 14 percentage points, because the numbers investors care about most, net asset value and dividend coverage, kept drifting the wrong way. This report is a test of whether the improvement management described can finally show up in core earnings.
The Street is not asking for much. Consensus calls for net investment income of $0.14 a share on revenue of $25.1 million. That EPS figure would match each of the past three quarters and sit 6.7% below the $0.15 earned a year ago, while revenue would be down about 10% from $28.0 million. Revenue is expected to tick up slightly from the prior quarter's $24.8 million, which would be consistent with leverage settling back into its target range rather than continuing to shrink. The company has not offered formal guidance, so the bar is set by management's own narrative more than by any explicit range.
That narrative rests heavily on the PSLF joint venture. Over the summer the JV cut its revolver spread to SOFR plus 2.1% and refinanced its securitization AAA tranche 97 basis points tighter, moves management estimated are worth about two cents a share annually. Because the securitization repricing landed in July, this is the first quarter that should carry most of the benefit. A meaningful lift in income from the JV, or at least a halt in the steady slide of its yield on invested capital from 17.0% to 15.1% over four quarters, would validate the claim. Another flat $0.14 with no visible contribution would suggest lower asset yields are absorbing the savings. Progress on the plan to grow the JV portfolio by roughly $200 million over 12 to 18 months matters here too, since that is where the incremental income is supposed to come from.
The dividend math is the pressure point. Total distributions continue to outrun core NII, and the gap has been filled by spillover income that has shrunk from $0.73 to $0.56 a share. Each quarter that pattern repeats, NAV erodes; it has already fallen from $7.11 to $6.56 over the past year. Investors should look for whether NAV stabilizes and how much spillover remains, because a further steep drawdown raises the question of how long the current payout can last without core earnings improving. Credit is the other swing factor. Non-accruals improved slightly to 2.5% of cost last quarter but remain well above the 1.3% level of a year earlier, and the new markdown at tariff-hit Kinetic Systems showed that consumer exposure can still surprise.
Management also argued that a better M&A backdrop would let it rotate equity stakes into income-producing loans, citing the roughly 14x return on the defense co-investment. New originations, however, came in at an 8.9% yield against an 11.0% portfolio debt yield, so redeployment dilutes income at first. With the two largest control positions, AKW and Flock, still one to two years from monetization, evidence of additional smaller exits and stronger deal flow would help keep that thesis credible.
Sentiment remains bearish, edging only slightly less negative than before the last report, and the stock at $3.14 sits well below its 200-day average of $3.97, nearer the low of its post-earnings range than the high. Expectations are clearly subdued. The question that matters is simple: does core NII begin to climb toward the dividend, with NAV holding steady, or does the gap keep being bridged by a shrinking cushion? The answer will decide whether last quarter's improving tone was a turning point or just better framing.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-15 | |
| Nov-03 | |
| Oct-06 | |
| Oct-02 | |
| Sep-02 | |
| Aug-10 | |
| Aug-10 | |
| Aug-04 | |
| Jul-06 | |
| Jul-02 | |
| Jun-02 | |
| May-07 | |
| May-07 | |
| May-04 | |
| Apr-06 |
