Fluence Faces A Credibility Test After Second Revenue Cut Sends Shares Toward Lows
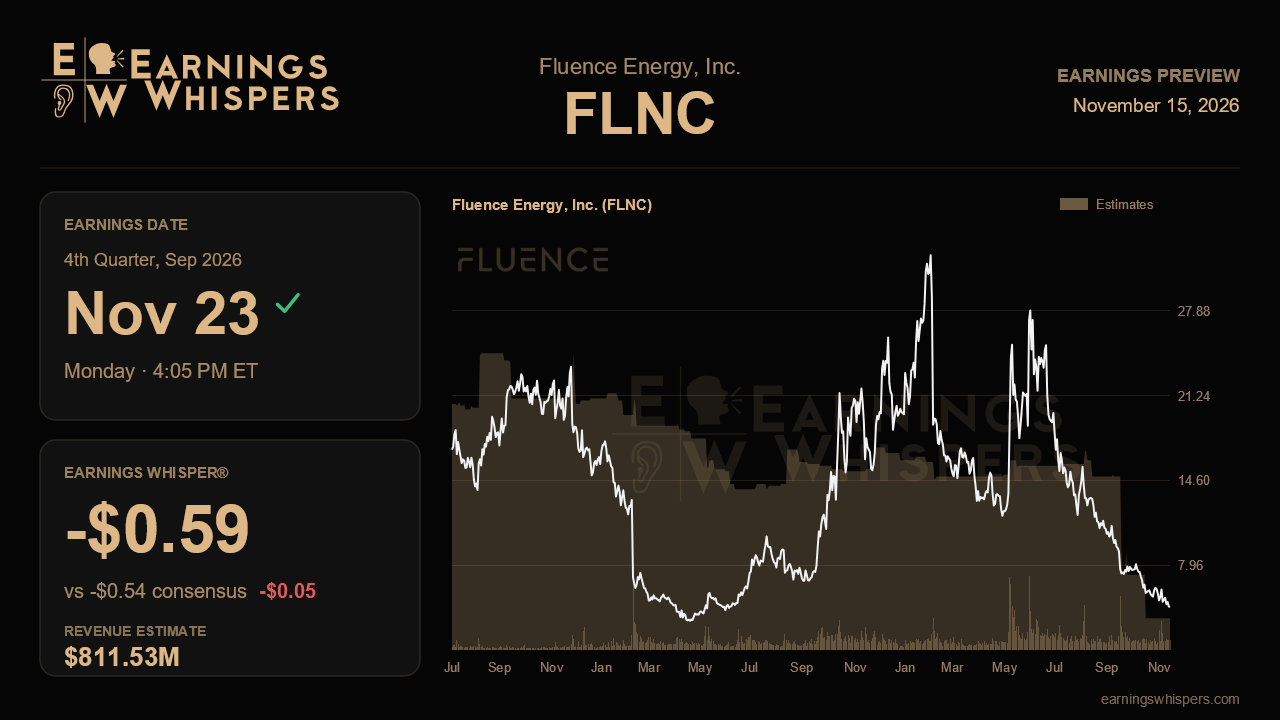
Fluence Energy heads into its fiscal fourth-quarter report with a striking split between what customers are ordering and what the company can actually deliver. Order intake and backlog hit records last quarter, and the energy storage specialist landed its first data center business. Since then, management has cut its fiscal 2026 revenue outlook for a second time, and the stock has lost nearly two-thirds of its value. The report due after the close on November 23 needs to show whether the manufacturing problems behind those cuts are being fixed or are still spreading.
Wall Street expects a loss of $0.54 per share on revenue of about $811.5 million. That compares with a profit of $0.13 and revenue of $1.04 billion a year ago, which works out to a revenue decline of roughly 22% and a sharp swing into the red. The whisper number of a $0.59 loss sits meaningfully below consensus. That suggests the more skeptical part of the market is bracing for a deeper loss than published estimates show.
Guidance is where the story turned. Management had reaffirmed a $3.4 billion revenue midpoint twice before lowering it to $3.0 billion with third-quarter results. At that point it blamed ramp delays at a new Houston contract-manufacturing plant and quality rework at a China component facility, which pushed roughly $400 million of revenue into fiscal 2027. The company has since cut again, to about $2.4 billion from a $2.9 billion to $3.1 billion range. The published full-year consensus of $4.41 billion is far out of line with that outlook, so the quarterly estimates are the more useful yardstick.
The second cut makes this report mainly about execution. Investors need a clear explanation of what went wrong after the August reset and whether the cause was the same Houston and China bottlenecks or something new. Evidence that the Houston automation is running at volume and that the China rework is behind the company would support management's view that the revenue was delayed rather than lost. Gross margin is the other swing factor. Last quarter's outlook implied roughly 11% for the fourth quarter, the bottom of the company's target framing, after about $44 million of lost margin and a $15 million charge on a battery supply agreement. Any further slippage would suggest the delays are costing more than missed shipments.
The demand story still has to hold up. Backlog reached a record $6.4 billion, and $2.2 billion of it was earmarked for fiscal 2027 revenue. The most important follow-up is whether the $550 million in hyperscaler awards has turned into firm purchase orders. Steady orders, conversion of those awards, and further growth in the 16 GWh data center pipeline would show customers are not walking away despite the delivery problems. The company also flagged a possible need for $300 million to $500 million of extra working capital. Any detail on how it plans to fund that, and what it means for liquidity, matters a great deal for a stock at these levels.
Sentiment has soured badly. About two-thirds of respondents are bearish, compared with less than a third before the last report. At $4.68, the shares sit just above their post-earnings low of $4.48 and far below the 200-day moving average near $14.44, after trading between roughly $12 and $30 the prior quarter. Expectations are clearly depressed, but that alone does not make a beat likely. The central question is whether new operations chief Roman Loosen's reorganization has stabilized production enough for management to stand behind the fiscal 2027 backlog conversion. If it has, the record order book still supports a recovery case. If it has not, the strong bookings will count for little until the company can ship them.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-15 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-27 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-05 | |
| Oct-02 |
