Agilent Faces A Higher Bar As China Rebound And Pharma Reshoring Orders Get Their Second Test
Agilent heads into its fiscal fourth-quarter report having done something few instrument makers managed this year: it raised its revenue, earnings and margin outlook three quarters in a row. That steady progression has rebuilt confidence in the story, and the stock has climbed accordingly. The question now is whether the drivers that surprised last quarter, a sharp turn in China, a pharma rebound and early reshoring orders, can repeat. Investors also want to know whether they can carry the company into fiscal 2027 without another guidance lift doing the heavy lifting.
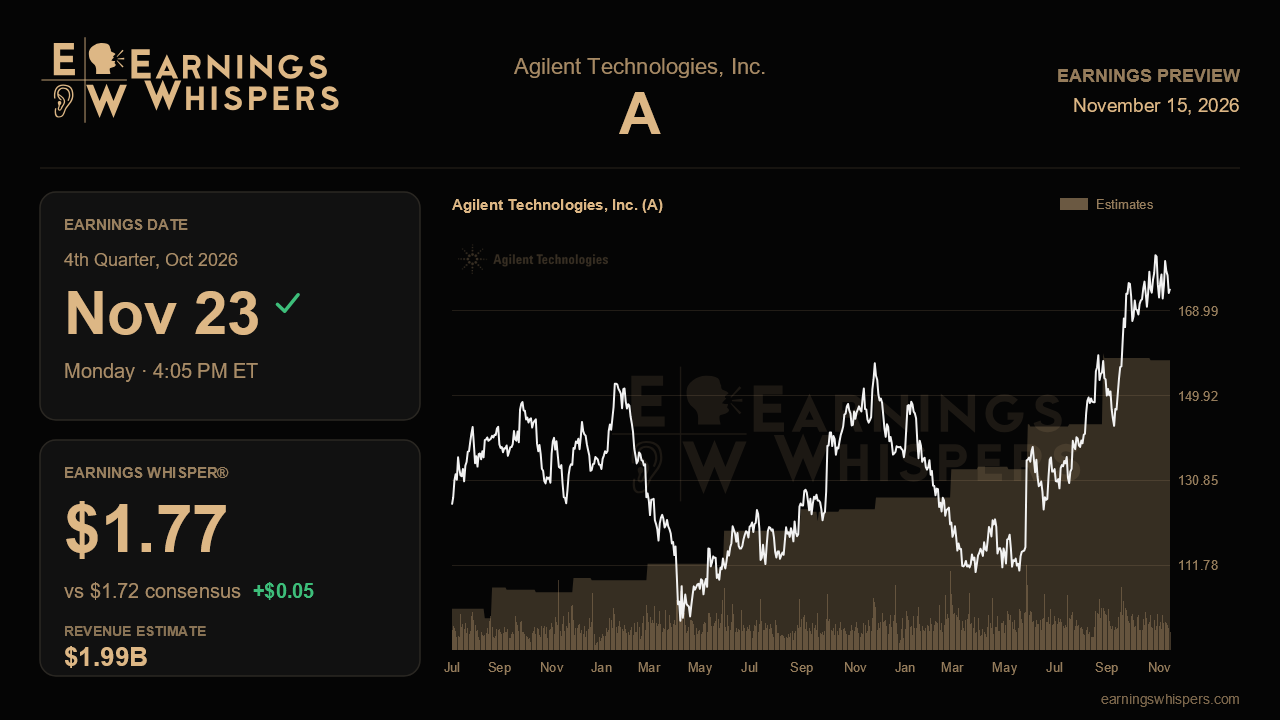
Wall Street is looking for earnings of $1.72 per share on revenue of about $1.99 billion, which would mean roughly 8% earnings growth and nearly 7% revenue growth from a year ago. That is solid, not spectacular, and it sits squarely inside management's own range of $1.71 to $1.74 per share on $1.98 billion to $2.00 billion in sales. The Earnings Whisper of $1.77 sits above both consensus and the top of guidance. That suggests the more engaged crowd expects Agilent to keep beating its own numbers, as it did last quarter when core growth topped the high end of its outlook by 140 basis points. A result merely at the midpoint would technically be fine, but it would break a pattern the market has come to price in.
China is the most important swing factor. Sales there rose 9% last quarter against expectations for flat, a dramatic reversal from a 9% decline the quarter before. Management raised its full-year China view to mid-single-digit growth. It credited CXO and biotech customers, contract testing tied to PFAS, and AI and semiconductor build-outs rather than government stimulus. That distinction matters because demand rooted in end markets is more durable than a policy sugar high. Still, management also cautioned that China could be non-linear heading into 2027. Another quarter of positive growth would validate the inflection. A slide back toward flat would suggest the third quarter was lumpy timing.
Pharma is the other pillar, and here the setup is more nuanced. Pharma accelerated to 12% growth last quarter, helped by roughly 30% expansion in the CDMO business. Management has already guided that business to flattish growth in the fourth quarter against a comparison above 40%, so a pause there should not shock anyone. The more telling evidence will be elsewhere. Management said 5 of the top 10 global pharma companies had placed early reshoring orders, ahead of plan, and investors should look for signs those orders are broadening and converting to revenue. They should also look for continued traction from new launches, including the 9500 ICP-MS, whose funnel topped $60 million, and the new flagship gas chromatographs, where orders ran at twice expectations. BioCare should add roughly $23 million in the quarter, so organic growth deserves closer scrutiny than the headline figure.
Margins are the quieter test. Operating margin expanded 210 basis points last quarter, helped by pricing that ran ahead of target. However, memory chip costs and Middle East logistics remain headwinds, and early depreciation and hiring for the Train C ramp are expected to weigh on fiscal 2027. How management frames that drag against continued pricing power will shape the earnings trajectory for next year.
The market has already rewarded the narrative. Shares are up about 9% since the last report while the S&P 500 slipped, and the stock trades well above its 200-day moving average, though about 5% below its post-earnings high. Sentiment is mildly bullish and essentially unchanged from last quarter, so enthusiasm has not run away. In the end, this report hinges on whether China and reshoring prove to be durable growth engines rather than one-quarter surprises. If they do, Agilent's claim to be entering 2027 from a position of strength holds up. If they falter, a stock priced for continued acceleration has less cushion than it did three months ago.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-12 | |
| Nov-10 | |
| Nov-04 | |
| Nov-03 | |
| Nov-02 | |
| Oct-29 | |
| Oct-28 | |
| Oct-27 | |
| Oct-22 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-01 |
