Zoom's Enterprise Inflection Faces Its Next Test As White-Label Churn And AI Costs Build
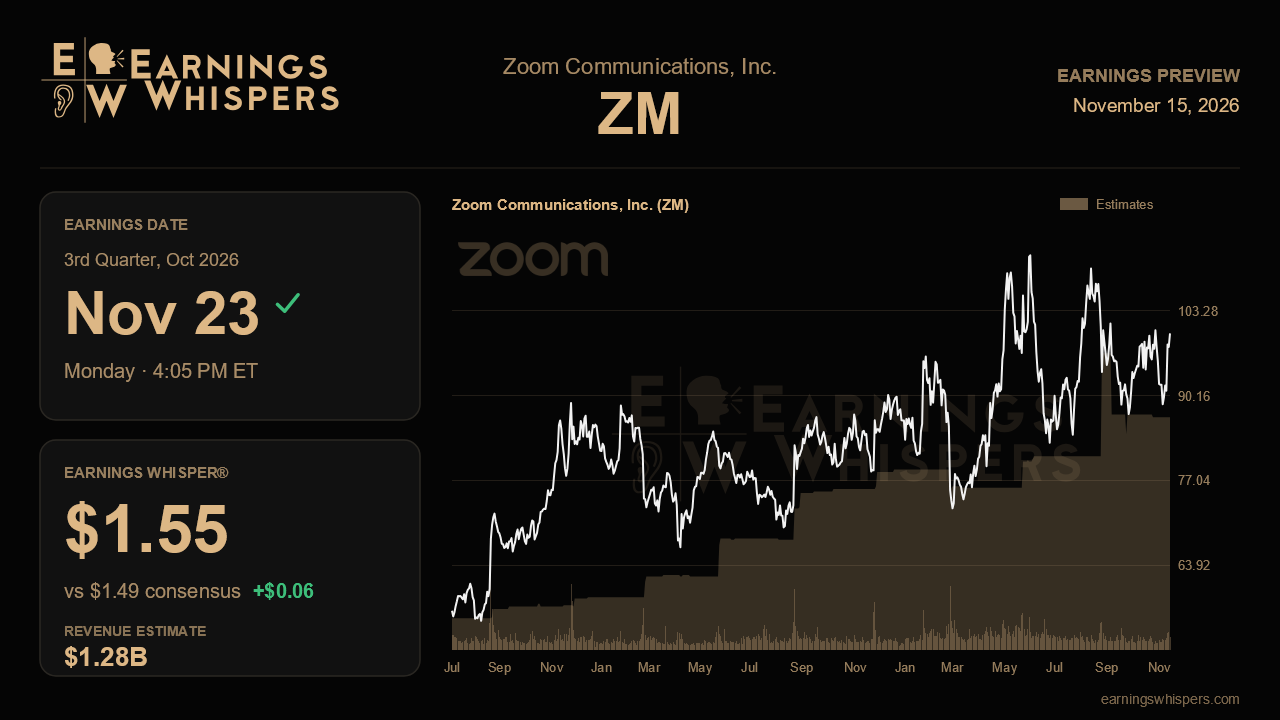
Zoom spent the last quarter convincing the market that its enterprise business has finally found a second gear. Enterprise revenue grew 7.8%, the fastest pace in three years, and remaining performance obligations jumped 14% to roughly $4.5 billion. The fiscal third-quarter report, due after the close on November 23, is where that story meets its first real friction: a white-label customer churn that management flagged as a building headwind for the back half of the year, a softer online business, and margins that slipped as AI usage and the Common Room acquisition weighed on costs.
The Street is looking for non-GAAP earnings of $1.49 per share on revenue of $1.28 billion, which would be growth of about 4.1% from a year ago. That is modest expansion, and a touch slower than the 4.9% Zoom posted last quarter, which fits with the churn drag management described. Management guided to $1.46 to $1.48 per share on revenue of $1.275 billion to $1.280 billion, so consensus sits a penny above the top of the earnings range and right at the high end on revenue. The Earnings Whisper of $1.55 raises the bar further, signaling that investors expect Zoom to clear its own guidance comfortably, as it has been doing. That reflects a pattern of steady raises: the full-year EPS outlook has climbed from $5.77 to $5.81 at the start of the year to $6.08 to $6.12 now, with free cash flow guidance also lifted.
The most important evidence will come from the enterprise segment. Holding enterprise growth near 7.8% would be impressive given that the white-label churn was described as worth roughly 40 to 60 basis points of drag. A further step up in enterprise net dollar expansion beyond 99%, along with RPO growth that stays in the low teens or better, would suggest last quarter's bookings strength reflected durable demand for larger, multiproduct deals rather than a one-off. A sharp fade in RPO growth or noncurrent backlog would challenge the idea that Zoom's contact center, Phone and AI offerings are reshaping its customer relationships.
AI monetization is the second pillar. Management pointed to licensed AI monthly active users up 125%, virtual agent customers up more than 250%, paid AI attached to nine of the top ten CX deals and a record number of seven-figure contact center wins. Continued growth there, plus early signs that Common Room and ZoomMate are pulling in revenue, would support the case. The catch is cost. Non-GAAP gross margin dipped to 79.1% and operating margin to 40.0% last quarter. If AI usage keeps pressuring margins while competition from OpenAI, Salesforce and CRM vendors intensifies in voice AI, the earnings upside that has fueled the guidance raises could narrow.
Online remains the soft spot. Management cut its full-year view for that business from slight growth to flat, blaming weaker top-of-funnel traffic as discovery shifts from search to AI tools. Another downgrade would raise questions about whether that channel is entering structural decline.
The market has leaned into the bullish view. Shares are up 4.8% since the last report while the S&P 500 fell 1.4%, and sentiment has improved to 43.9% bullish from 31.1% a quarter ago. At $99.80 the stock sits well above its 200-day moving average and within about 2.5% of its post-earnings high of $102.25, putting a breakout attempt in play. With expectations elevated, the report hinges on whether enterprise growth and backlog can absorb the white-label churn and margin pressure while still supporting another upward revision to the full-year outlook.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-13 | |
| Nov-11 | |
| Nov-10 | |
| Oct-29 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-14 | |
| Oct-12 | |
| Sep-30 | |
| Sep-29 | |
| Sep-21 | |
| Sep-15 |
