H World Beats And Raises Again As The Asset-Light Shift Lifts Margins, While Same-Hotel RevPAR Falls 4.4%
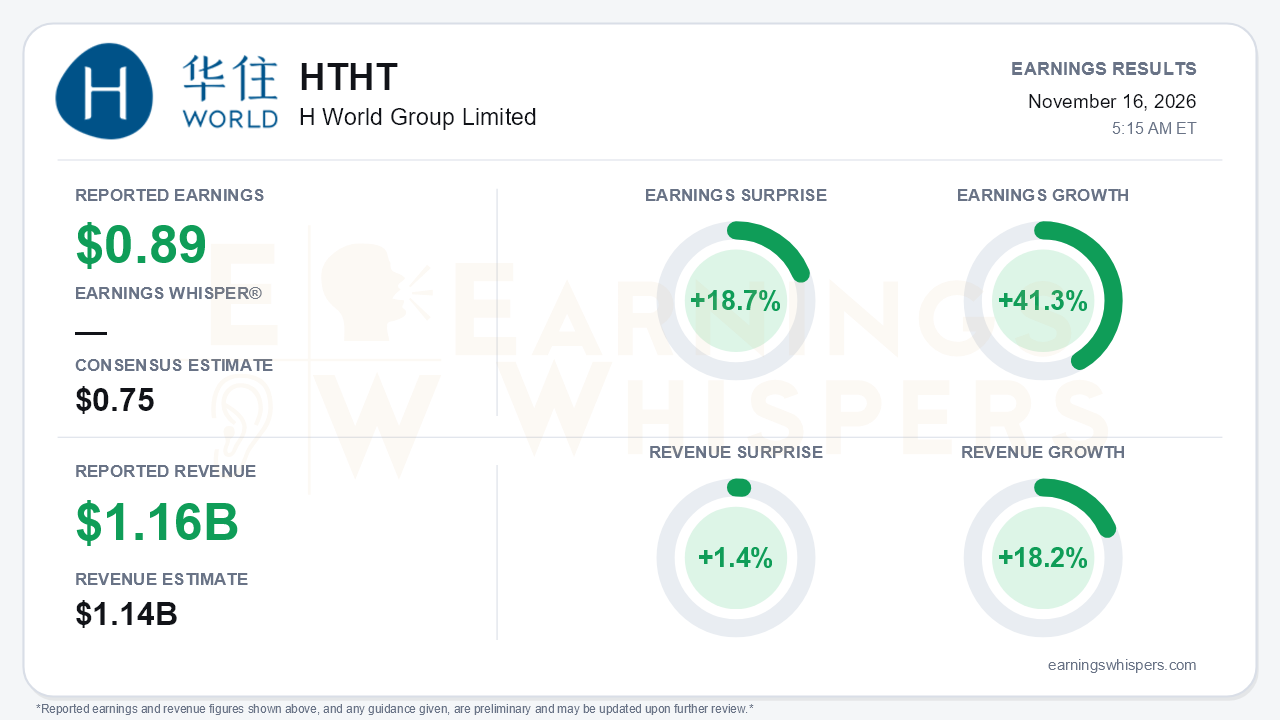
H World Group delivered a clear third-quarter beat. Earnings were $0.89 per share against a $0.75 consensus, an 18.7% surprise, and earnings grew 41.3% year over year. Revenue of $1.156 billion topped the $1.14 billion estimate by 1.4%.
The Earnings Whispers dollar-based revenue growth figure of 18.2% differs from the company's local-currency figure. In renminbi, H World reported revenue up 11.3% to RMB7.8 billion. That is only a modest pickup from 10.8% in Q2 and 11.1% in Q1, so the underlying top line was steady rather than sharply accelerating.
Full-year revenue guidance rose to 9%-10%, from 4%-8% last quarter and 2%-6% at the start of the year. That makes this a second consecutive raise. The catch is that the raise largely moves company targets closer to where the Street already was.
The central tension is that H World's profit engine and its hotel-level demand are moving in opposite directions. The earnings strength comes from mix rather than from stronger hotel-level demand.
- **Franchised growth:** Manachised and franchised revenue jumped 25.7% to RMB4.2 billion.
- **Exiting leases:** Leased-and-owned revenue fell 7.4% as the company exits leases.
- **Margins:** Operating margin expanded to 33.2% from 29.4% a year ago. On the call, management cited an adjusted EBITDA margin of 39.8%, up from 31.0% in Q1.
- **Other revenue:** Revenue from supply chain, technical services and retail more than doubled to RMB362 million.
- **GAAP versus adjusted:** GAAP net income attributable to shareholders rose 22.6% to RMB1.8 billion. The adjusted figure grew faster because a RMB136 million foreign-exchange loss was excluded.
Beneath that, the hotel-level picture is weaker. Same-hotel RevPAR for mature China hotels fell 4.4%, with ADR down 1.3% and occupancy down 2.7 points. The decline was nearly uniform across economy and midscale tiers.
Blended China RevPAR edged up just 0.1%, propped up by newer, higher-rate hotels. That reading continues a steady fade:
| Metric | Q1 | Q2 | Q3 |
|---|---|---|---|
| China RevPAR growth | +3.0% | +1.1% | about flat (+0.1%) |
| China ADR growth | +4.5% | +2.6% | +1.8% |
Management blamed extreme summer weather, which is plausible but does not explain a three-quarter deceleration.
The call also showed the growth machine slowing in several places:
- **Room growth:** Slowed from 14.1% in Q1 to 10.8%.
- **Pipeline:** Shrank to 2,772 China hotels from 3,054 at the end of Q2.
- **Closures:** Full-year closures are now expected to exceed the original 600-700 guide under a roughly two-year network-quality program.
- **Franchise profitability:** M&F gross operating profit growth slowed to 11.2% from 18.5% in Q2. GOP margin slipped to 59.8% from 63.6% in Q1.
- **Margin outlook:** The most telling change is rhetorical. The CFO now describes EBITDA margin as "relatively stable," with possible short-term fluctuation from stepped-up spending on brand, membership, marketing, technology, talent and overseas expansion. Last quarter the language was "continue to expand."
That is a meaningful softening just as margins hit a record. Bears have legitimate ammunition here.
There are offsetting positives:
- **Q4 demand:** Management said fourth-quarter demand is tracking slightly better than expected, helped by an October rebound in business and exhibition travel such as the Canton Fair and CIIE. It kept its "slight increase" full-year RevPAR outlook.
- **International:** HWI, the international segment, improved. RevPAR moved from -3.8% in Q2 to +0.1%, Europe rose 3.3%, and segment adjusted EBITDA more than doubled year over year to RMB136 million despite a 7.7% revenue decline tied to European closures.
- **New revenue streams:** Selling supply-chain services to third parties, a co-branded H Rewards card with China Merchants Bank and Mastercard, and AI-driven pricing all extend monetization beyond room nights.
- **Balance sheet:** Cash was RMB17.3 billion and net cash RMB9.3 billion per the release; the call cited a higher figure on a different basis. That supports the US$2.5 billion three-year shareholder-return plan.
Investors came into the print with no strong conviction either way. Earnings Whispers sentiment was essentially unchanged, edging from -0.0134 to -0.0128, slightly below neutral.
Price action has been more constructive than sentiment. Shares were $50.39 heading into the report:
- up 10.8% since the open after the August release;
- about 7.2% above the $47.00 200-day moving average;
- 22% above the October 2 low of $41.29;
- just 1.5% below the inter-earnings high of $51.16 set November 9.
The stock therefore entered the report near the top of its range, which raises the bar for a guidance raise that mostly catches up to consensus. Price, momentum and AVWAP trend readings are positive, consistent with that recovery.
The bottom line is that H World's beat was high quality in the sense that matters for a franchisor. Fee revenue, margins and cash generation are all scaling as the asset-light transition matures. However, the drivers of future growth are cooling at the same time: mature-hotel RevPAR, rate growth, unit additions, pipeline and margin ambition. The call preserved a credible earnings story for the next few quarters, but investors are now underwriting a slower-growing, pruned network funded by reinvestment, with the stock trading near its highs.
Read our earnings preview for H World Group Limited: https://www.earningswhispers.com/article/HTHT/23057
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| 5 hours | |
| Nov-09 | |
| Nov-04 | |
| Sep-16 | |
| Sep-09 | |
| Sep-03 | |
| Aug-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-05 | |
| Jul-28 |
