Niu Technologies Misses Its Own Revenue Guide As Growth Stalls, But Sequential Margin And Loss Improvement Keeps The 2027 Story Alive
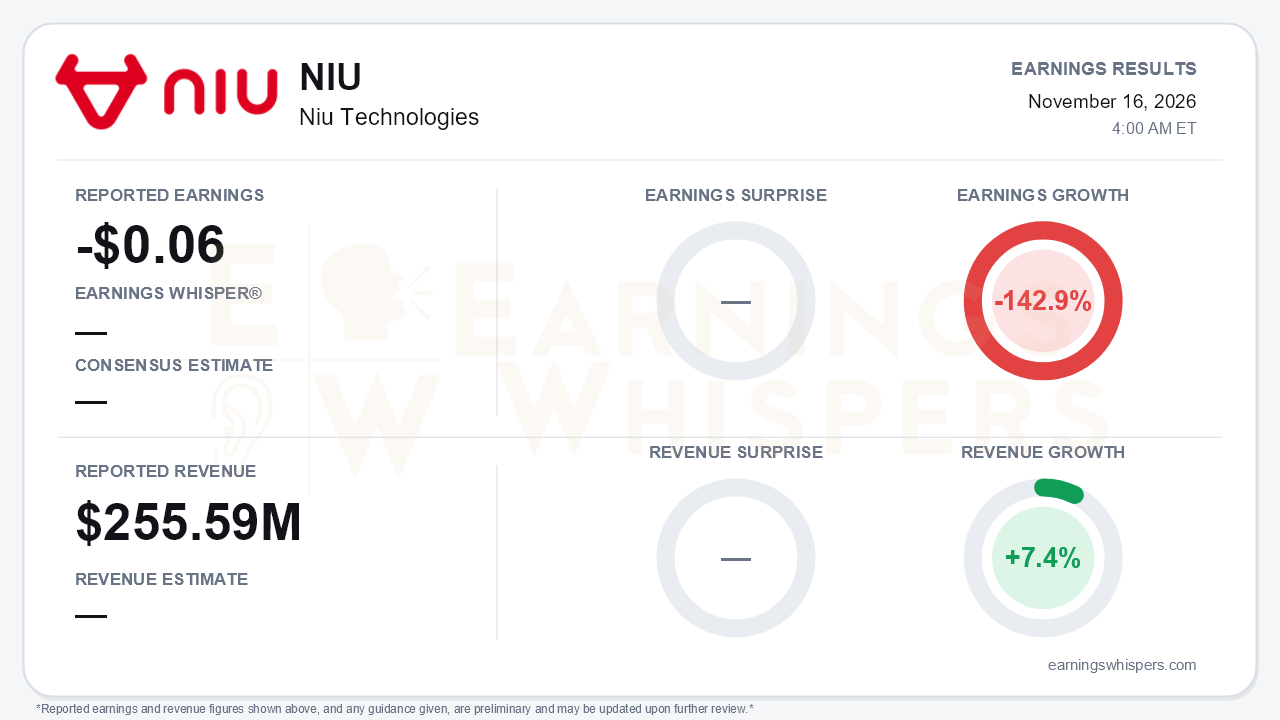
Niu Technologies' third quarter showed a growth story abruptly losing altitude. The company reported a loss of $0.06 per ADS, compared with a profit a year earlier, and earnings fell 142.9% year over year. Revenue was $255.59 million. Earnings Whispers calculates dollar revenue growth of 7.4%, but in reporting currency revenue rose only 1.2%, to RMB 1,713.6 million. Both figures stand, and the operating story follows the RMB number. No consensus estimate was available, but the more relevant benchmark is NIU's own: management had guided Q3 revenue to RMB 1.86 billion to RMB 2.03 billion, or 10% to 20% growth, and missed the low end by roughly RMB 150 million.
The deceleration is stark. RMB revenue growth slid from 33% in Q1 to 15% in Q2 to 1.2% in Q3. Total volume growth slowed from 29% to 24% to 15.4%, and China volume growth fell from 35% to 26% to 8.6%. Volume still grew, so the problem is pricing and mix. Revenue per e-scooter fell 11.5% to RMB 2,944, and China ASP dropped to RMB 2,902. That is down 12% year over year and down sequentially from RMB 3,010 in Q2 and RMB 3,120 in Q1. China e-scooter revenue declined 4.0% despite higher units. Gross margin compressed to 18.0% from 21.8% a year ago, and China gross margin fell 5.6 points on upstream cost inflation and the shift toward lower-margin e-motorcycles. Operating expenses grew 18.1%, with R&D up 48% and G&A inflated by foreign-exchange losses. The result was a GAAP net loss of RMB 34.0 million against net income of RMB 81.7 million a year earlier.
That is the central tension: the year-over-year picture is poor, while the sequential picture is improving.
- **Margins:** Gross margin rose two points from 16.0% in Q2 and also topped Q1's 17.4%. E-motorcycle margin improved by a point quarter over quarter, and e-motorcycle ASP rose to RMB 3,065.
- **Losses:** The net loss narrowed sharply from RMB 102 million in Q2 and RMB 94 million in Q1.
- **Expense discipline:** The operating expense ratio fell to 20.5% from 23.6% in Q2 and 29% in Q1.
- **Mix shift in China:** E-motorcycles grew roughly 350% and now account for 56% of China volume.
- **Retail network:** Tier 2 and Tier 3 retail sales rose 60%, and per-store sales there rose 47%. Management plans to add more than 1,000 domestic stores in 2027.
The weakness is concentrated in premium e-bicycles. China e-bicycle volume fell 45% and Tier 1 city sales fell about 30%. The recovery management expected by Q2 has now slipped into 2027. Management is betting on AI features and a mid-tier e-bicycle priced at RMB 3,299 to revive the category.
International results were the clearest bright spot. Overseas volume jumped 226% to 47,051 units, and international e-scooter revenue rose 137.6%. European dealers increased to 464 from 417 in Q2. NIU also added Best Buy distribution across more than 700 U.S. stores and a new German partner. Management said overseas micro-mobility inventory has normalized and expects the U.S. to return to positive gross margin in Q4. It is targeting international profitability in 2027. The quality of that growth deserves scrutiny, however. International revenue per unit fell 27.2%, and micro-mobility clearance was sold at negative gross margin, with European stock not yet fully cleared.
The Q4 outlook calls for revenue of RMB 947 million to RMB 1,082 million, up 40% to 60%. That headline is less impressive than it looks because it laps a weak year-ago base. It also absorbs an industry-wide 3C certificate renewal pause that halted e-bicycle production in November. Management expects those shipments to shift into a Q1 2027 restocking wave, but a longer pause could hit Q4 sell-in further. Notably, the FY2026 volume target of 1.67 million to 1.91 million units went unmentioned. With roughly 1.23 million units sold year to date, Q4 would need about 440,000 or more units, which looks out of reach given the guide. Bears have legitimate ammunition in a second straight disappointment against management's own forecasts.
The balance sheet offers some cushion. The release shows RMB 1.73 billion in cash, term deposits, and short-term investments. The call cited roughly RMB 1.9 billion, a figure that appears to include RMB 215.5 million of restricted cash. Operating cash inflow slowed to RMB 287 million from RMB 392 million in Q2. Accounts payable also swelled to RMB 1.2 billion from RMB 704 million at year-end, which flatters liquidity. Shareholders' equity fell to RMB 690 million from RMB 905 million at year-end.
Current sentiment and price data were not available for this report. Shares opened at $2.11 after the August report, below the 200-day moving average now sitting at $2.53. That suggests the stock entered this period with the market already discounting a weakening trajectory.
The bottom line is that NIU delivered a top-line miss against its own guidance, a profit-to-loss swing, and an all but abandoned annual volume target. Sequential gains in gross margin, expense control, and loss reduction, along with fast-growing international volume, keep a credible 2027 narrative in play. Until China ASPs stabilize and the premium e-bicycle recovery actually shows up, investors are being asked to look past near-term deterioration on management's word, and its recent forecasting record argues for caution.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 6 hours | |
| Oct-19 | |
| Oct-05 | |
| Aug-10 | |
| Aug-10 | |
| Jul-13 | |
| Jul-03 | |
| Jun-17 | |
| May-18 | |
| Apr-20 | |
| Apr-17 | |
| Apr-06 | |
| Mar-16 | |
| Mar-16 |
