Edible Garden's Gross-Margin Breakout Is Real, But A Q3 Cash Burn And Thin Liquidity Keep The Balance Sheet Central
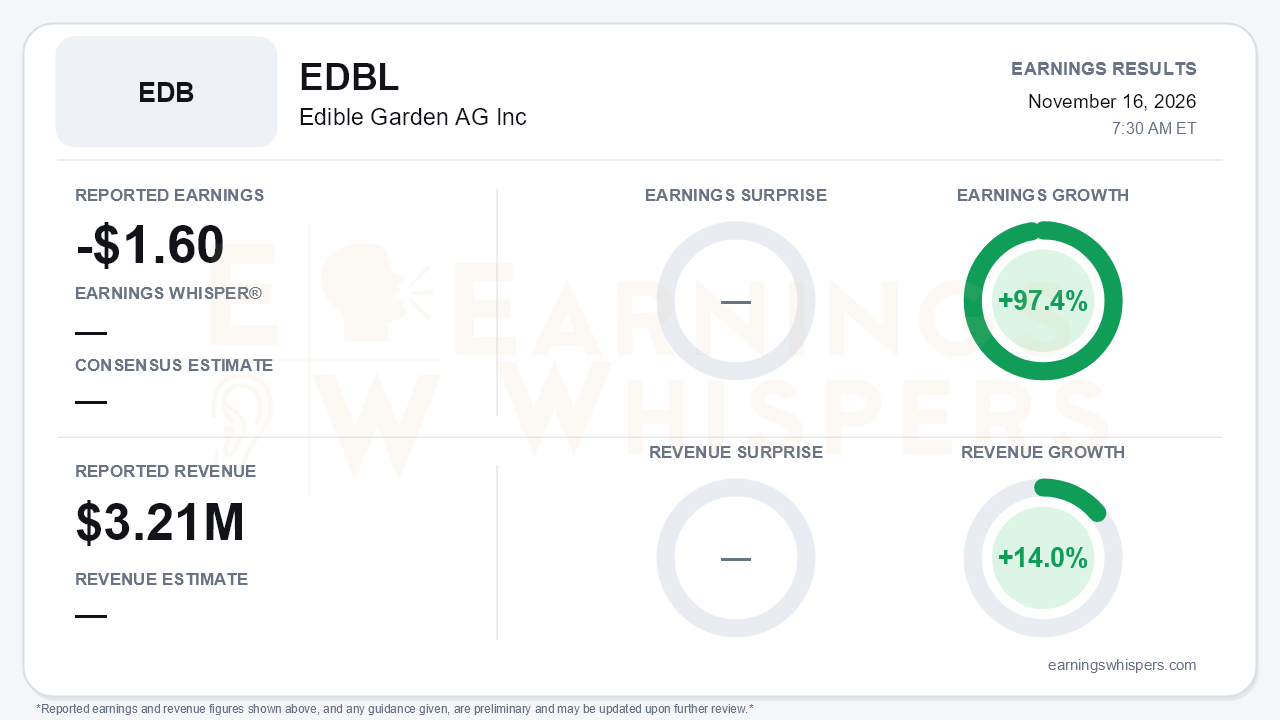
Edible Garden AG (NASDAQ: EDBL) posted its cleanest operating quarter in some time, and the funding question still looks bigger after the report. The company lost $1.60 per share on revenue of $3.21 million for the quarter ended September 2026. Revenue grew 14.0% year over year, and earnings per share improved 97.4%. No consensus estimate or Earnings Whisper was available, so there is no beat or miss to measure. The per-share comparison also says little about operations: weighted shares rose from about 6,500 a year ago to roughly 1.58 million after stock splits and heavy issuance. The more useful number is the net loss, which narrowed 37.3% to $2.5 million from $4.0 million. The central tension is that the income statement is clearly improving while operating cash flow went the other way.
The margin story deserves the most credit. Gross margin rose to 23.9% from 9.7% a year ago, an improvement of about 1,430 basis points. It was also up from roughly 16.7% in the second quarter; the release and call summary differ slightly on that figure. The company reported a gross loss of about $1.2 million in the fourth quarter of 2025, so the recovery has been steep. Cost of goods sold fell 4.0% even as volume increased. Management attributed the gains to three changes:
- moving from direct store delivery to retailer distribution centers;
- concentrating on higher-volume, mainstream herb varieties;
- the scale efficiencies that followed.
SG&A declined 11.7% to $2.7 million, down from $3.1 million in the second quarter. Those gains came in what is traditionally the slowest season. The improvement is also recent. Nine-month gross profit was just $0.3 million versus $1.0 million a year earlier, which shows how weak the first half was.
On the top line, the trend is less tidy than the headline suggests:
- Year-over-year growth edged up to 14% from 12.8% in the second quarter, but remains below the first quarter's 22.9%.
- Sequentially, revenue fell to $3.2 million from $3.6 million in the second quarter.
- Cut herbs are the engine, up 65.7% versus roughly 42–50% growth in the second quarter, helped by new programs with Kroger, Target, Walmart and Weis Markets.
- Distribution widened to more than 7,000 doors from about 6,000, including three more Walmart distribution centers and primary-supplier status at UNFI's Mid-Atlantic center, which serves more than 1,500 stores.
Management described the margin gains as sustainable. Its tone was more numbers-driven than the promotional language of earlier in the year.
The forward catalysts are concrete:
- **Caney Fork Farms supply agreement.** It is expected to cut production costs by more than 12% on transitioned activities. About 30–40% of production is slated to shift starting in the fourth quarter and be substantially complete in 2027.
- **First named ready-to-drink (RTD) customer.** A private-label protein beverage award from a global grocer with more than 2,000 stores gives the Farm-to-Formula strategy its first identified customer.
- **Prairie Hills ownership.** The company closed the roughly $6.3 million purchase of the Prairie Hills site in Iowa, its planned beverage plant, on Oct. 30.
- **Square Roots collaboration.** A plant-based RTD line is targeted for launch at Expo West in March 2027.
- **Management.** A permanent CFO replaced the interim one.
Skeptics will note what was not repeated. The call did not restate the second-quarter claims that plant capacity was 100% pre-sold or that first production would come in late 2027. RTD capital spending and timing also remain undisclosed. Outsourcing a large share of production to a third party carries its own execution risk.
That leads to the balance sheet, where bears have legitimate ammunition:
- **Cash burn.** Operating cash flow was about $0.9 million positive through six months but $3.9 million negative through nine. That implies roughly $4.8 million of burn in the third quarter alone, following two positive quarters.
- **Liquidity.** Of about $5.6 million in cash, $4.4 million is restricted, leaving roughly $1.2 million unrestricted.
- **Leverage and equity.** Long-term debt climbed to $12.2 million from $0.2 million at year-end, and stockholders' equity fell to $3.6 million from $12.5 million.
- **Dilution.** Prairie Hills was funded with Series B preferred stock and a secured note, on top of $13.5 million of second-quarter financing.
- **More financing likely.** Management said it continues to pursue ways to strengthen financial flexibility, which reads as a signal that more capital is coming.
The market has already been unforgiving. Shares opened at $1.68 after the August report, a small fraction of the $31.46 200-day moving average. That gap reflects a prolonged collapse in the share price and heavy dilution rather than any near-term signal. No current sentiment reading or price snapshot was available, so the post-report reaction cannot be judged.
The bottom line is that Edible Garden delivered real operational progress. Margins have inflected, cut-herb demand is accelerating, and the RTD strategy finally has a named customer. But revenue is still small and slipped sequentially, cash burn returned sharply, and unrestricted cash is about $1.2 million against an expensive beverage build-out. Until the company shows it can fund Prairie Hills without repeated dilution, the balance sheet will matter more to shareholders than the margin chart.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| Nov-10 | |
| Nov-05 | |
| Nov-03 | |
| Nov-02 | |
| Oct-27 | |
| Oct-23 | |
| Oct-14 | |
| Oct-09 | |
| Oct-06 | |
| Oct-01 | |
| Sep-25 | |
| Sep-22 | |
| Sep-17 |
