KE Holdings Doubles Adjusted Profit And Clears The Whisper As Margin Gains Outrun A Deepening Revenue Decline
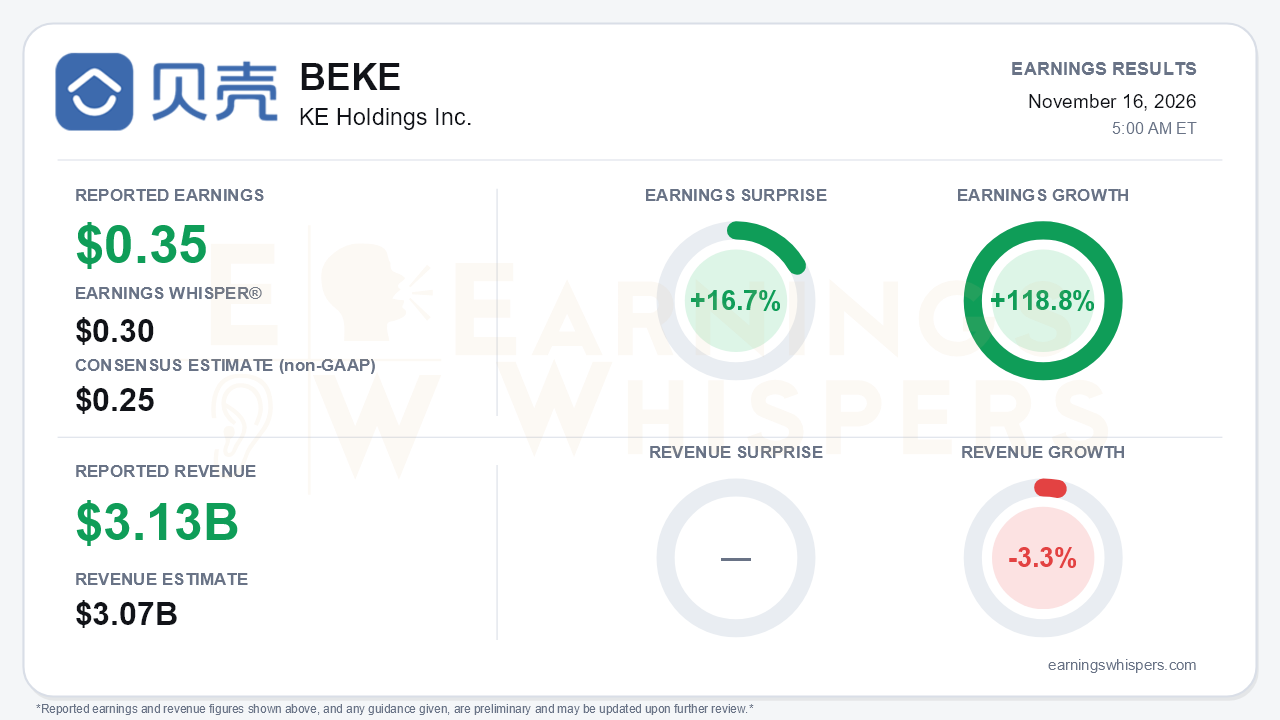
KE Holdings (NYSE: BEKE) delivered another quarter in which profitability, not growth, drove the story. Adjusted earnings of $0.35 per ADS beat the $0.25 consensus and topped the $0.30 Earnings Whisper number by 16.7%. Earnings grew 118.8% year over year, while revenue of $3.131 billion came in 2.0% above the $3.07 billion consensus. The central tension is that profits are accelerating as the top line moves the other way. Earnings Whispers measures a 3.3% revenue decline in dollar terms. In renminbi, the company's reporting currency, net revenues fell 8.9% to RMB21.0 billion, a wider drop than the 5.7% decline in the second quarter. The gap between the two figures reflects currency translation. Either way, the business is shrinking at the revenue line even as earnings power climbs.
The beat came from margins and cost cuts, and the evidence for that is broad rather than one-off. Gross margin rose 6.3 percentage points to 27.7%, and every major business line improved its contribution margin:
- Existing home: 42.5%, up from 39.0%.
- New home: 27.9%, up from 24.1%.
- Renovation: 40.2%, up from 32.0%.
- Rental: 16.6%, up from 8.7%.
Operating expenses fell 22.4%, with sales and marketing down 27.5%, largely on lower headcount. GAAP operating margin jumped to 11.7% from 2.6%, and GAAP net income nearly tripled to RMB2.2 billion. The GAAP improvement matters because it shows the gains are not simply an artifact of non-GAAP adjustments. Adjusted net income growth also accelerated sharply, to 102.6% from 74.9% in Q2 and 15.7% in Q1.
Much of the revenue weakness is cosmetic, though not all of it. Rental revenue fell 25.4%, worse than Q2's 14.8% decline, because Carefree Rent is shifting to net-fee recognition. More than 65% of that business is now booked on a net basis, versus over 50% in Q2. That shift is shrinking reported revenue while lifting rental contribution profit to RMB708 million. Renovation revenue fell 22.9%, but that decline reflects earlier channel pruning flowing through deferred revenue. On the call, management said renovation contract value returned to year-over-year growth for the first time this year, and conversion from existing-home buyers rose to 4.0% from 3.2%.
The less flattering signals are real. Existing home GTV growth slowed to 3% from 8% in Q2, and Lianjia-served existing home volume fell 7.3%. Active agents declined 4.4%, and mobile MAUs dropped to 44.5 million from 49.3 million. Managed rental unit growth decelerated to roughly 25% from 34% in Q2. Operating cash flow halved sequentially to RMB3.28 billion, and new home receivable days stretched to about 49 from 39. Even the new home business showed strain: its contribution margin slipped 0.9 points sequentially as KE raised commission sharing to partners in some cities.
The forward catalysts lean constructive. Management pointed to the late-September mortgage interest subsidy and said October unit volumes across 50 tracked cities rose about 31%. New home GTV growth improved to 5.3% from 1.2% in Q2. KE also launched an integrated developer offering, and its first project, in Guangzhou, saw more than 90% subscription at its initial launch. Management framed completed-home sales reform as a potential share-gain opportunity. However, the company offered no numeric guidance and kept a neutral stance on the market. It also signaled phased new investments, which bears can read as a warning that the cost tailwind may partly reverse. Quarterly buybacks fell to about $162 million from roughly $250 million in Q2. Cumulative repurchases now total about 15.6% of shares since the program began.
Investor sentiment did not anticipate a strong quarter. It slipped from mildly positive (0.16) to slightly negative (-0.02) heading into the report. Shares have gone essentially nowhere since the August report, down 0.4% at $17.86. That flat result masks a round trip from a $15.86 low in mid-September to a $19.32 high on November 5, the latter coinciding with improving post-subsidy volume data. The stock enters the post-report period about 6% above its 200-day moving average but 7.6% below that recent peak. Earnings Whispers price, momentum and AVWAP trend readings are positive, while sequential growth is neutral.
The bottom line is that KE produced a high-quality profit beat built on structurally better unit economics, not accounting gymnastics. Leading indicators in renovation, new homes and post-subsidy transaction volumes have turned up. But revenue is still contracting, existing home growth slowed, and cash conversion weakened. Management also declined to commit to numbers while hinting at reinvestment. For investors, the profit and margin turnaround is largely in hand. Upside from here likely depends on proving that October's volume rebound can drive actual top-line growth.
Read our earnings preview for KE Holdings Inc.: https://www.earningswhispers.com/article/BEKE/23050
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 5 hours | |
| Nov-08 | |
| Nov-04 | |
| Aug-21 | |
| Aug-21 | |
| Aug-11 | |
| Jun-12 | |
| May-19 | |
| May-19 | |
| May-15 | |
| May-07 | |
| Apr-24 | |
| Apr-24 | |
| Apr-24 |
