Outdoor Holding Tops Revenue Views, But GunBroker's Growth Downshifts As FFL Fees Do The Heavy Lifting
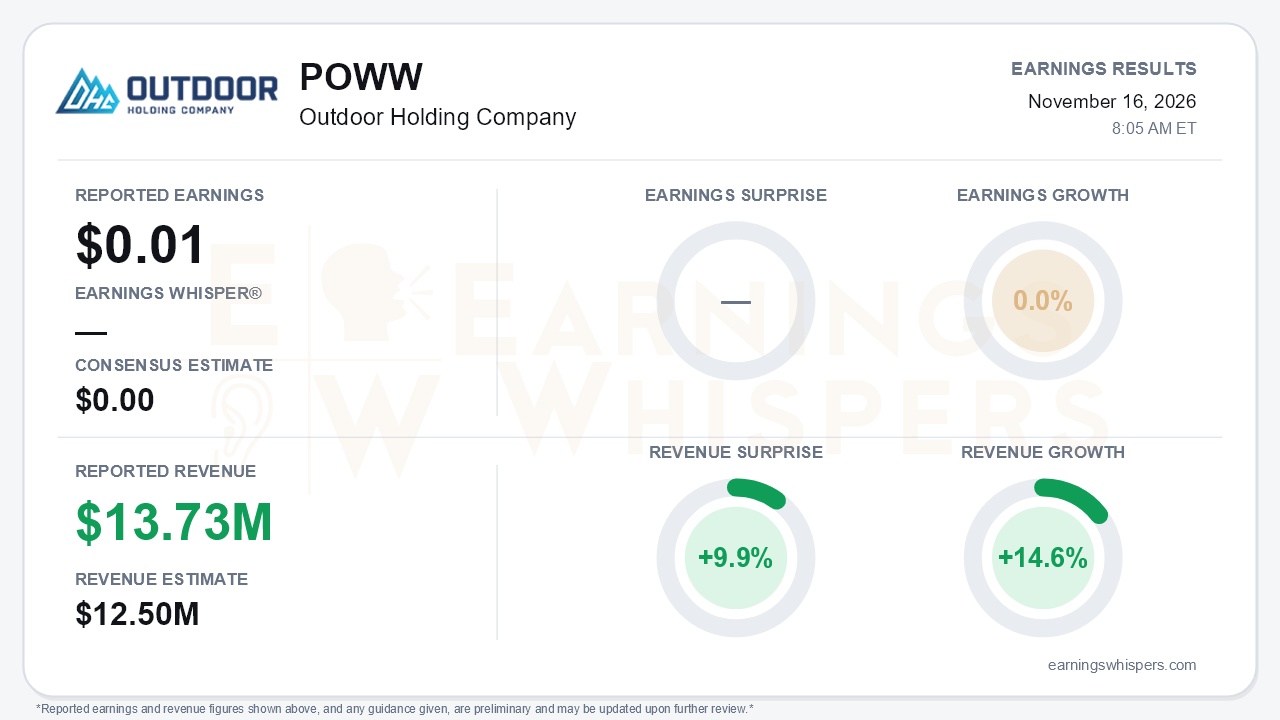
Outdoor Holding Company (NASDAQ: POWW) earned $0.01 per share in its fiscal second quarter, edging past the $0.00 consensus. Revenue of $13.73 million beat the $12.5 million estimate by 9.9% and rose 14.6% year over year. Per-share earnings were flat versus a year ago, with 0.0% growth, but that hides a much stronger profit trend. Operating income nearly tripled to $2.0 million from $0.7 million, and adjusted EBITDA climbed 24.7% to $6.1 million. The central tension is that GunBroker's operating leverage is real, while the top-line growth producing it is slowing.
The deceleration is clear when compared with the first quarter. Revenue growth slowed to 14.6% from 22.1%. GMV growth fell to 10.3% from 18.1%, and firearm unit growth dropped to 4.8% from 11.6%. Q1 was helped by Virginia legislation pulling demand forward, so some slowdown was expected.
The quality of the revenue beat also deserves scrutiny. About $0.8 million came from the new FFL transfer service, which added 40 basis points to a 6.59% take rate. Excluding FFL transfers:
- Net revenue grew only about 8%.
- The legacy take rate was modestly lower, as mix shifted toward firearms and the largest sellers, who pay lower fees.
FFL transfers also carry a per-transaction cost. That pushed cost of revenues to 15.4% of sales from 12.9%, around the same time the company stopped reporting a gross profit subtotal. Management argues the mix shift does not weaken the business's underlying economics. That is a reasonable position, but investors should recognize that monetization is now rising faster than organic marketplace volume.
The bottom-line comparison needs context as well. The prior-year quarter was distorted by several one-time items:
- An $0.8 million gain on debt extinguishment
- A $1.75 million vendor contingency
- A $1.6 million credit tied to the SEC investigation
Cost discipline in the current quarter is clear. Employee expense fell $0.7 million, and about 70% of incremental revenue flowed through to EBITDA, lifting adjusted EBITDA margin to 44.6% from 41%. Even so, management signaled that opex declines will moderate as reinvestment begins. The quarter still carried about $0.5 million of Texas redomestication costs and $0.4 million of largely one-time AI spending.
The call kept a credible growth story intact. In a seasonally soft quarter with no legislative tailwind, GunBroker posted its first year-over-year Q2 GMV increase since fiscal 2021. Other operating gains included:
- Market share of adjusted NICS checks rose to about 6.3%.
- Average order value rose 8.3% to $485.
- Silencer and suppressed-firearm GMV more than doubled to roughly $3 million.
Management said same-day transaction volume has run 16% to 23% or more above last year since the midterm election, and it struck a more confident tone than in Q1. Universal payments cleared underwriting with several vendors and coding is underway, but there is no launch date. That matters because nearly 30% of transactions are still not paid by card. Bears have legitimate ammunition here:
- Active sellers slipped 1.6% to about 36,000, which management admitted it is not satisfied with.
- Adjusted NICS checks slid from +8.5% in July to -2.3% in September.
- The share gain narrowed to 16 basis points from 41 basis points in Q1.
- Sequential adjusted EBITDA fell to $6.1 million from $7.9 million, ending the sequential growth streak management had highlighted, though seasonality explains much of that.
Capital allocation is the cleanest part of the story. Second-quarter operating cash flow was about $8.5 million, which included a $2.0 million D&O insurance reimbursement. Cash grew to $70.4 million despite these outlays:
- $5.4 million of buybacks at an average $2.20 per share
- $0.8 million of preferred dividends
The company has no bank debt. After quarter-end, the board added $20 million to the repurchase authorization, leaving $24.5 million available. That is meaningful relative to the company's size. Trailing adjusted EBITDA of about $28 million now sits above management's $25 million run-rate goal. Lingering class-action, derivative and indemnification costs remain a drag that could be material in individual periods.
The market setup is more complicated than the beat implies. Investor sentiment stayed positive heading into the report but fell sharply, from 0.55 to 0.24. Shares at $2.29 were down 4.6% from the $2.40 open after the August report. They have given back much of the post-report spike to a 52-week high of $2.67 and sit 14.2% below that peak. The stock remains 7.3% above its 200-day moving average and 9% above its September low of $2.10, which puts it roughly where the company has been buying back shares. Trend readings are mixed: momentum is positive, while AVWAP remains negative.
The bottom line is that Outdoor Holding delivered a profitable, cash-generative quarter with a clear revenue beat. However, growth is downshifting, and a growing share of it comes from fee layering rather than marketplace expansion. The post-election demand lift, universal payments and an aggressive buyback give the bull case real catalysts. Shrinking seller counts, softening NICS trends and pressure on the legacy take rate are the metrics that will show whether the cooling in investor enthusiasm was premature.
Read our earnings preview for Outdoor Holding Company: https://www.earningswhispers.com/article/POWW/23061
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-16 | |
| Nov-16 | |
| Nov-12 | |
| Nov-09 | |
| Oct-22 | |
| Oct-08 | |
| Sep-29 | |
| Sep-03 | |
| Aug-18 | |
| Aug-13 | |
| Aug-10 | |
| Aug-10 | |
| Jul-20 | |
| Jun-23 |
