Bilibili's Earnings Test: Can Ads And Lumi Master Offset Macro Caution?
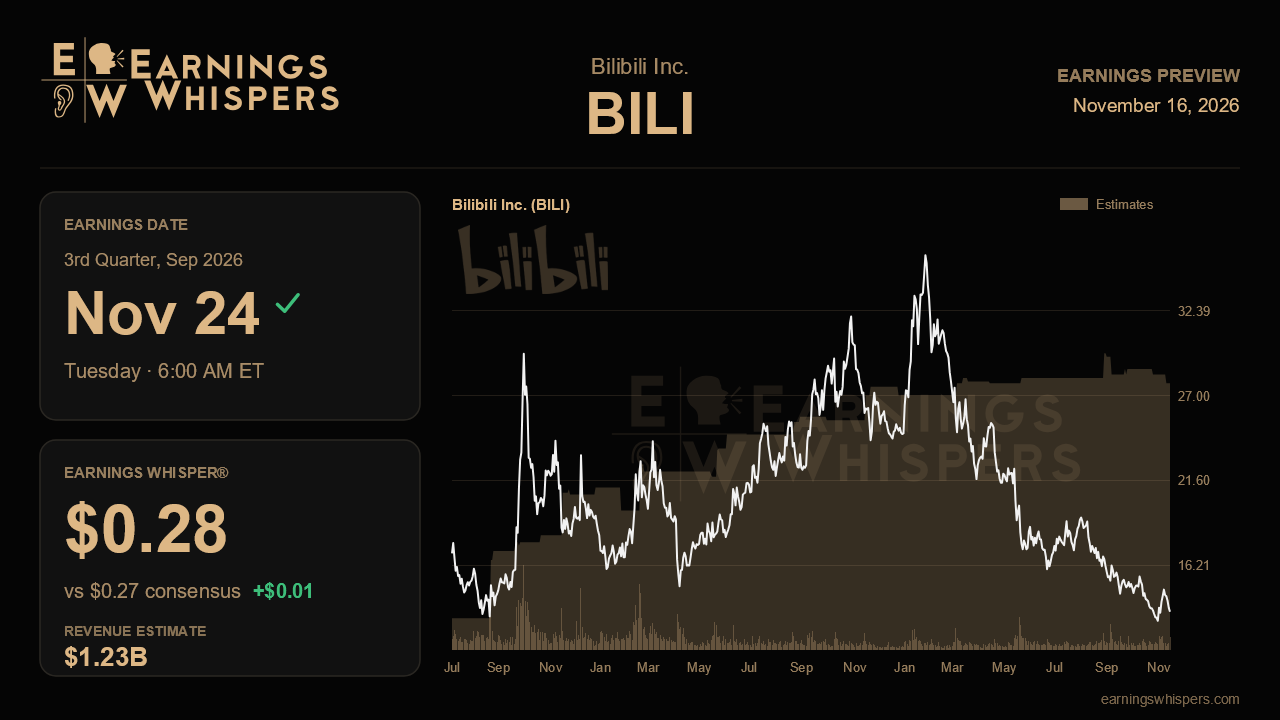
Bilibili heads into its September-quarter report with a fundamentals story that still looks intact on paper and a share price that has been treated as if it is not. Last quarter delivered a 16th straight quarter of gross margin expansion and 55% growth in net profit. Yet management also acknowledged, for the first time, a very challenging macro backdrop in China. Since then the stock has dropped 18.1%, trailing the S&P 500 by more than 16 percentage points. This report has to show which of those two signals deserves more weight.
The Street is looking for non-GAAP earnings of $0.27 per share on revenue of about $1.23 billion. That revenue figure implies roughly 14.5% growth from the year-ago $1.07 billion, a noticeably faster clip than the 8% local-currency growth Bilibili posted last quarter. Some of that gap may come from currency translation, so the growth rate in renminbi will be the cleaner test of underlying momentum. The profit bar is more demanding. The consensus estimate is close to double the $0.14 earned last quarter and well above the $0.15 from a year ago, so the forecast assumes real operating leverage. The Earnings Whisper of $0.28 sits only a penny above consensus, a modest lean toward upside rather than a sign of outsized hopes. Management offered no formal numerical guidance, which leaves the conference call commentary as the main yardstick.
Advertising is the first pressure point. It accounts for about 39% of revenue, and its growth slipped to 28% last quarter from a 30% peak. That would be a small dip in a normal year. It looks more meaningful next to management's comment that advertisers are demanding faster, more measurable returns. Strong growth in verticals such as automotive, home decoration and apparel, AI advertisers more than doubling, and search revenue doubling all suggest Bilibili is winning share even in a tougher market. A result holding in the mid-to-high 20s would support that view. A slide toward the low 20s would suggest the macro warning was a preview rather than a precaution.
Games are the second swing factor, and the timing matters. Game revenue fell 14% last quarter. The CFO has pointed to a return to year-over-year growth only from the fourth quarter, so a further soft gaming number in this report should not be a shock. What matters more is early evidence on Lumi Master, the self-developed simulation title that launched globally on September 17. Investors also want confirmation that the licensed strategy game San Wang remains on schedule for the fourth quarter. If management reaffirms the fourth-quarter inflection with some early traction data, the 2027 lineup, which includes Ragnarok Online 3, Mistbound and Three Kingdoms: The Ravages of Time, becomes far more credible.
Beneath the headline numbers, three other trends deserve attention. Paying users have fallen for several quarters, down to 33.4 million. Gross margin, at 37.2%, is still well short of the 40% to 45% long-term target. R&D spending on AI rose 16% last quarter, and how much of that cost the business absorbs will shape whether adjusted net margin can climb back toward the 10% range it reached late last year.
Expectations look subdued. Bullish sentiment has edged up only slightly, to 11.2% from 10.2%. At $13.25, the stock trades about a third below its 200-day moving average and sits near the bottom of its post-earnings range of $12.64 to $17.13, a range that lies entirely below the prior quarter's. The new $300 million buyback gives the company a tool to support the shares, but the narrative rests on whether ad growth can hold up against a weaker consumer while the game pipeline arrives on schedule. Firm ad numbers and a confident fourth-quarter gaming outlook would keep the story intact. Another step down in ad growth paired with a vague game update would give the market's skepticism more support.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-03 | |
| Oct-28 | |
| Sep-25 | |
| Sep-09 | |
| Sep-04 | |
| Sep-04 | |
| Aug-27 | |
| Aug-27 | |
| Aug-27 | |
| Aug-06 | |
| Jul-22 | |
| Jun-30 | |
| Jun-24 | |
| Jun-24 |
