Kingsoft Cloud's First Operating Profit Faces Its Real Test After A 38% Stock Slide
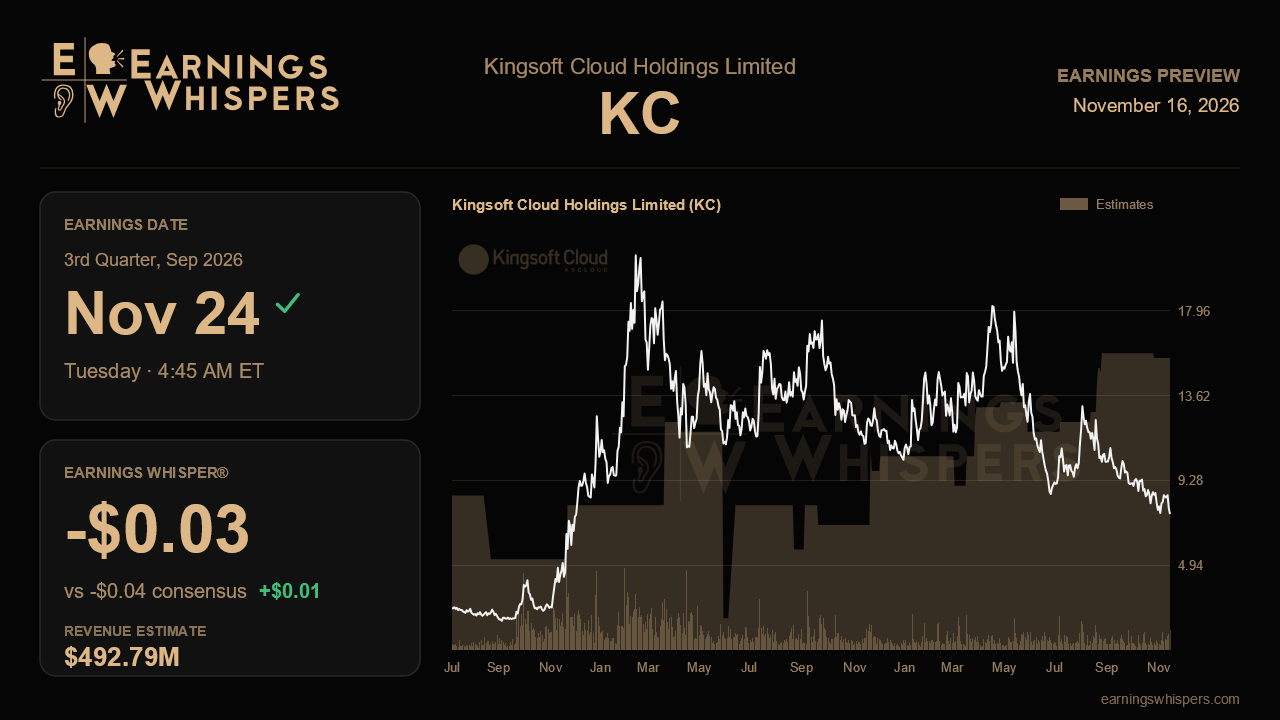
Three months ago Kingsoft Cloud delivered the quarter its bulls had been waiting years for: revenue above RMB3 billion for the first time and, more importantly, its first positive adjusted operating profit ever. The market's response since then has been brutal. Shares have fallen 38.5% since that report while the S&P 500 slipped only about 2%, leaving the stock at $7.55, well below its 200-day moving average of $11.82 and barely above the post-earnings low of $7.42. That gap between improving fundamentals and a collapsing share price is what makes this report, due before the open on November 24, unusually consequential. Either the profitability inflection holds and the selloff looks overdone, or the numbers show the inflection was more fragile than management suggested.
The Street is looking for a loss of 4 cents a share on revenue of about $492.8 million, which would be roughly 42% growth from the year-ago quarter. That is an acceleration from the 31% pace reported last quarter. It would also represent a solid sequential step up from $452.8 million. The Earnings Whisper sits at a loss of 3 cents, a hair better than consensus. The difference is small, but it suggests the more engaged crowd expects the loss to keep narrowing rather than widening. The company did not issue formal guidance, so the bar is set largely by the momentum management described on its last call.
That momentum ran almost entirely through AI. AI cloud gross billings reached RMB1.33 billion last quarter, up 82% from a year earlier and now more than half of public cloud revenue. Management argued this business is margin-accretive, citing successful price increases on storage and compute and an emerging managed-services model with better economics. The validation investors need is straightforward. Adjusted gross margin should hold at or above last quarter's 15.4%, and adjusted operating margin should stay positive. A slip back toward the 13% gross margin trough of the first quarter would suggest that the improvement owed more to timing than to a durable mix shift.
The call also raised several issues that this quarter should help resolve. Enterprise cloud revenue fell 1% year over year, which management blamed on memory and storage price spikes delaying state-owned and government budgets, a delivery calendar weighted toward the back half, and a reclassification of project revenue into public cloud. If that explanation is right, the third quarter should show at least some recovery, helped by newly announced public-sector wins in Nanjing, Wuhan and Gansu. Continued contraction would make the softness look structural. Supply is the other swing factor. Management described chip and compute scarcity as a new norm that limits how quickly it can convert backlog. So revenue upside depends partly on whether the company gets hardware deployed, not just on demand.
The balance sheet is the quiet risk beneath the growth story. Management firmed full-year capital spending at RMB15 billion after spending RMB6.2 billion in the first half. That implies an even heavier second half. Cash dipped to RMB4.67 billion, and higher borrowing costs have already squeezed EBITDA margin. Investors will want evidence that financing costs are not eroding the operating gains. They will also look for support from related-party demand, after the Xiaomi and Kingsoft transaction caps were lifted to RMB10 billion for 2026 and 2027. Progress on the Starflow model platform, which serves more than 230 enterprise customers, and on the new AgentKit tools would help show the AI franchise is broadening beyond a few large buyers.
Sentiment has swung from 53% bullish ahead of the last report to slightly bearish now, so expectations have clearly reset lower. That gives the company room to impress. The central question is whether Kingsoft Cloud can grow AI revenue at this pace while keeping operating profit positive and its capital needs manageable. If it can, last quarter's inflection becomes a trend. If margins slip under the weight of capex and debt, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Oct-29 | |
| Oct-19 | |
| Sep-25 | |
| Aug-19 | |
| Aug-19 | |
| Aug-19 | |
| Aug-06 | |
| Jul-07 | |
| May-27 | |
| May-27 | |
| Apr-23 | |
| Apr-15 | |
| Apr-07 | |
| Mar-31 |
