Ituran's Record Run Meets A Skeptical Market As Growth Comparisons Get Tougher
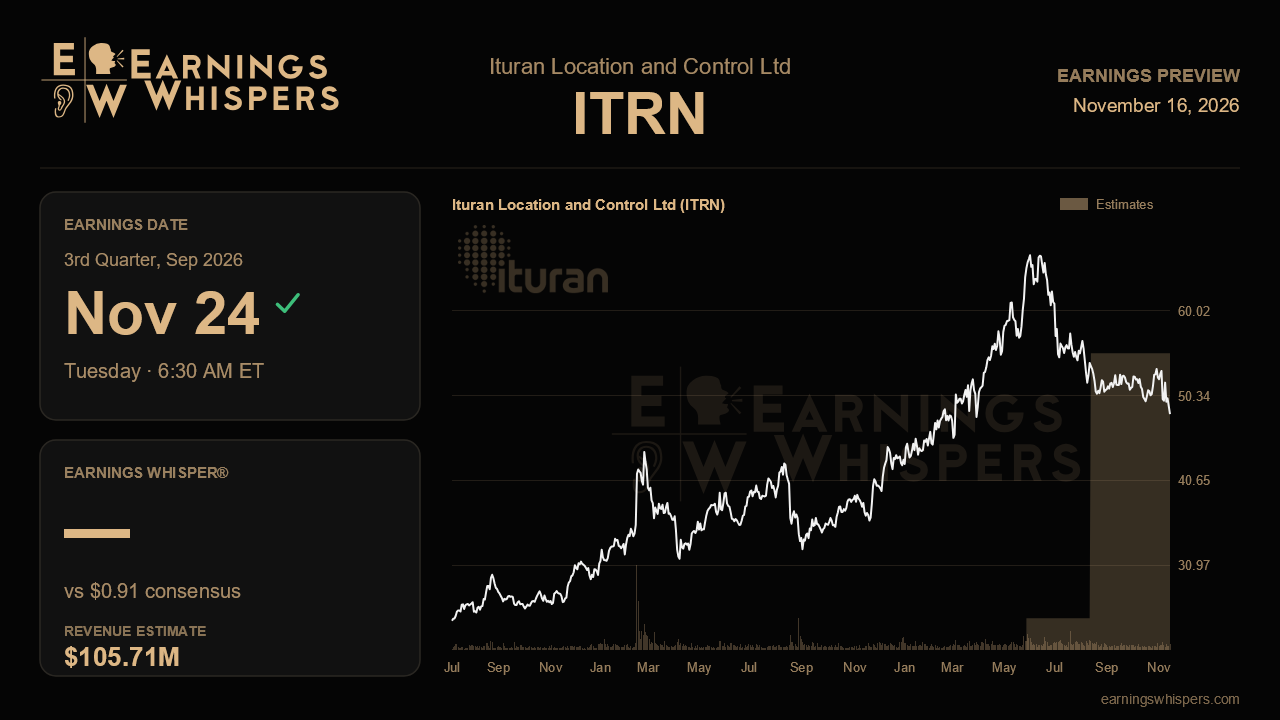
Ituran heads into its third-quarter report with a striking disconnect. The business has just delivered four straight quarters of accelerating revenue growth, record profitability and its first paid big data deal, yet the stock has slid 13% since that report, roughly 10 percentage points worse than the S&P 500. The shares now sit at $48.23, essentially at the bottom of their post-earnings range and well below the 200-day moving average near $53.86. The market is either doubting that the momentum can last or simply no longer paying for it. This report will help settle which.
The Street is looking for earnings of $0.91 per share on revenue of about $105.7 million. That would be 23% EPS growth and 14.6% revenue growth from a year ago. These are healthy numbers, but they also imply a visible slowdown from the 21% top-line growth posted last quarter. Much of that is arithmetic. The year-ago quarter was a tougher comparison, and on a sequential basis consensus calls for only a modest step up from the record $104.8 million just reported. Ituran does not issue formal financial guidance, so the Street's bar rests on extrapolation rather than a company range. That makes the quality of the beat, if one arrives, more important than its size.
The operating story to test is subscription strength. Subscription revenue growth accelerated from 13% to 25% over the past year and now makes up about three quarters of sales, which is why margins have been expanding faster than revenue. EBITDA margin reached 27.2% last quarter and net income grew 29%. If subscription growth holds near the 20% range even against the harder comparison, the earnings leverage story stays intact. A sharper fade, particularly if product revenue does the heavy lifting, would suggest the recent acceleration was partly cyclical. Subscriber additions are the cleanest gauge. Management reaffirmed, rather than raised, its 160,000 to 180,000 net-add target for 2026, and with roughly 81,000 added in the first half, another quarter around 40,000 keeps the company on pace. A meaningful shortfall would be the first real crack in the demand narrative.
The newer growth vectors matter more for sentiment than for this quarter's numbers. Management signaled optimism about a larger big data agreement in the near term, following the completed Israeli Ministry of Transportation deal, and pointed to active pilots plus discussions with insurers on usage-based pricing. Progress on the eTuran Mob rental platform in the U.S. and the Connect Fiat OEM program in South America also bears watching. None of these is expected to move 2026 results, but an announced second data deal would go a long way toward convincing investors the optionality is real. Silence would not break the thesis, though it would leave the stock leaning entirely on its core business.
There are smaller swing factors. Currency moves have become worth roughly $1 million to operating profit, and last quarter's shekel strength produced a finance expense that dented net income. Net cash also dipped after the special dividend and buybacks, so investors will want to see strong cash generation resume after the record $32.2 million in operating cash flow last quarter.
Expectations around the stock have clearly cooled. Bullish sentiment has fallen to 8.8% from 39.1% heading into the prior report, and the shares now trade below the entire range of the previous quarter. That lowers the emotional bar, even if the numerical one has not moved much. The central question is whether Ituran can show that subscription-driven margin expansion survives the tougher comparison. If it can, the selloff looks like a mispricing of durable growth. If growth and margins both soften, the market's skepticism will look early rather than wrong.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Oct-20 | |
| Sep-09 | |
| Aug-19 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-06 | |
| Jul-20 | |
| May-26 | |
| May-26 | |
| Apr-27 | |
| Mar-09 | |
| Mar-05 | |
| Mar-05 |
