MiniMed's Second Standalone Quarter Must Show Flex Demand Can Outrun Fading Margin Patience
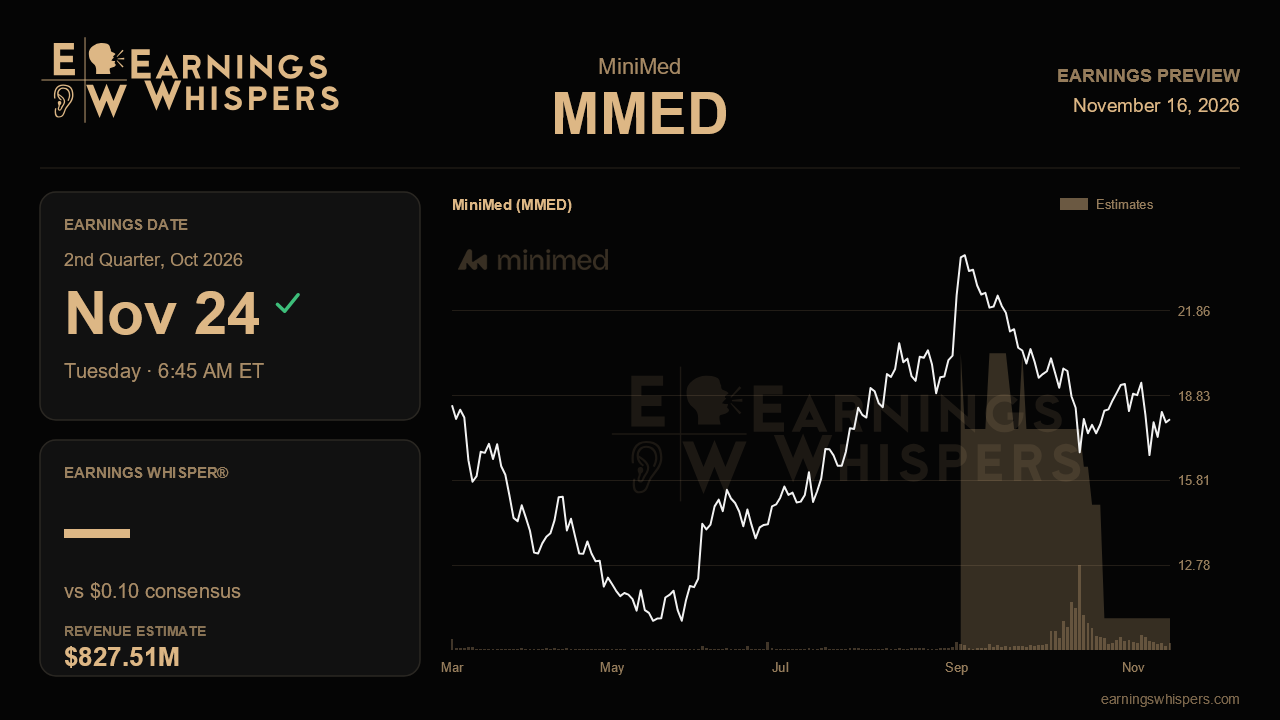
MiniMed delivered nearly everything a newly independent company could want in its first full standalone quarter: a sharp rebound in US growth, a raised revenue outlook and a pipeline that kept arriving early. The stock has fallen anyway. Shares are down about 11.8% since that report, roughly 10.8 percentage points worse than the S&P 500, which frames the fiscal second-quarter release before the open on November 24 as a test of whether the market's doubts center on demand or on the slow climb in profitability.
The Street expects earnings of $0.10 per share on revenue of about $827.5 million. That revenue figure sits below the $843.0 million reported last quarter, but the comparison is less alarming than it looks. The first quarter carried an extra week that management estimated added 4 to 6 points to headline growth, so some sequential normalization is built into the math. On the full year, MiniMed lifted its fiscal 2027 revenue target to roughly $3.43 billion from $3.41 billion, while consensus sits at $3.42 billion, slightly below the company's own number. Analysts have not fully embraced the raise, which leaves room for upside if the quarter confirms that the acceleration was not just an extra-week illusion.
The demand story is what needs validating. US organic growth snapped back to 13.1% from just 1.5% in the prior quarter as the Flex pump launch cleared the air pocket management had flagged earlier. New US pumps sold rose more than 20%, new prescribers climbed 24% and CGM attachment edged up to 69%. Flex with the Instinct sensor began shipping in the US in mid-August, so this is the first quarter to show a full period of that combination. Sustained double-digit US organic growth once the calendar distortion washes out, alongside another uptick in sensor attachment, would support the 10.5% organic growth guide. A slide back toward mid-single digits would suggest the first quarter was more pent-up demand than durable momentum. Internationally, the UK and France benefited from new sensor launches, and continued strength there would indicate the Instinct rollout has legs.
Profitability is where the narrative is most exposed. Adjusted EBITDA margin was only 9.9% last quarter, or about 12.2% excluding a pulled-forward investment and a currency remeasurement charge. Management merely reaffirmed its roughly 16% full-year margin target rather than raising it, and that goal leans heavily on the back half. Gross margin of 55.9% beat internal plans on better Simplera yields and warranty costs, so holding near that level matters. Without a visible step up in EBITDA margin this quarter, the second-half ramp will start to look steep. Cash is a related worry: free cash flow was a $90 million outflow on separation costs, and only 17 of roughly 160 transition service agreements with Medtronic had been exited. Progress on that count would ease concerns about standalone costs lingering.
Sentiment has soured noticeably, swinging from modestly bullish ahead of the last report to clearly bearish now. The stock, at $17.99, sits well above its 200-day moving average of $14.61 but much closer to its post-earnings low of $16.56 than its $24.43 high, a sign that early enthusiasm has been largely unwound. Pipeline updates on the Fit launch, the Vivera closed-loop program and the newly started pivotal for the next-generation extended-wear sensor could help, though the market appears to want earnings evidence more than milestones.
Ultimately, the quarter turns on whether MiniMed can show that its growth spurt is translating into operating leverage. Solid organic growth paired with a credible move toward the 16% margin target would keep the improving narrative intact; strong sales with stalled margins would likely keep skeptics in charge.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 hours | |
| Nov-16 | |
| Nov-16 | |
| Nov-05 | |
| Nov-04 | |
| Nov-03 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-07 |
