Autodesk's Raised Outlook Faces Its First Test As MaintainX Joins The Numbers
Three months ago Autodesk finally sounded like a company that had stopped bracing for trouble. After several quarters of cautious messaging around its sales reorganization, management raised its full-year billings and revenue targets, lifted its underlying organic billings growth outlook to 9% to 10% from 8% to 9%, and closed MaintainX, the largest acquisition in its history. The fiscal third-quarter report, due after the close on November 24, is the first chance to check whether that newfound confidence was earned or merely front-loaded into a strong first half.
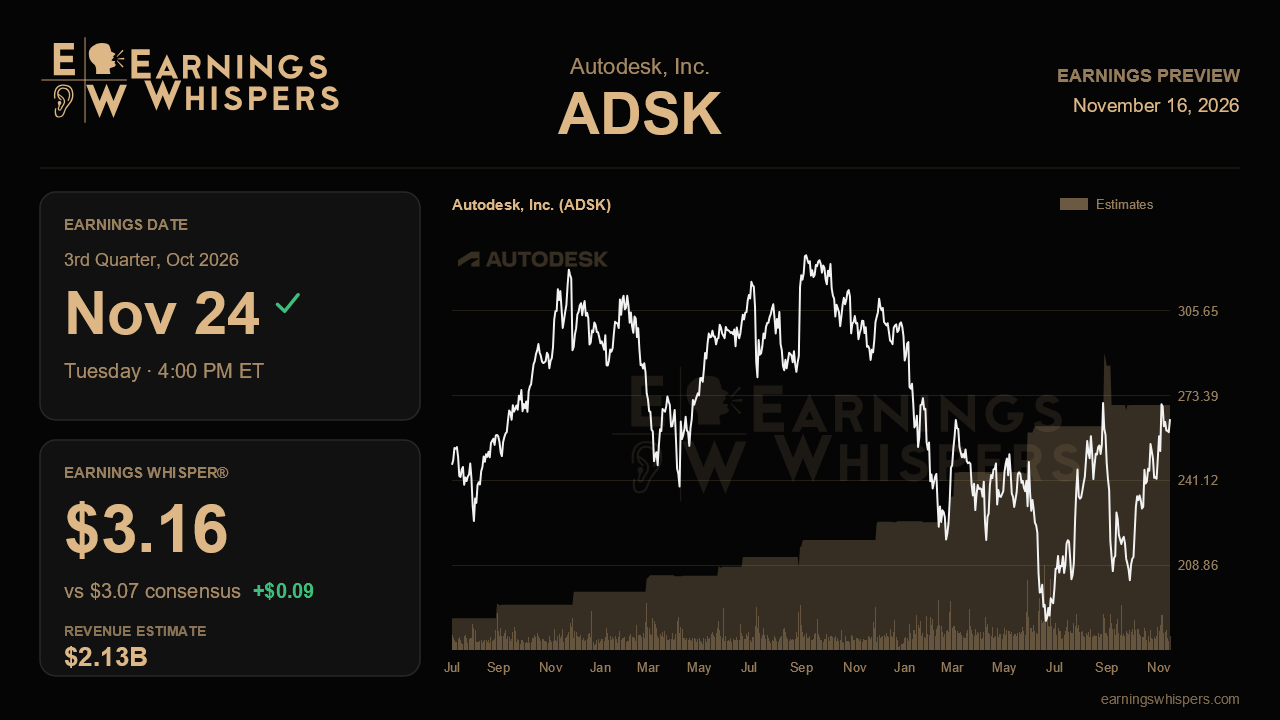
The Street is lining up almost exactly with management. Consensus calls for non-GAAP earnings of $3.07 a share on revenue of $2.13 billion, both sitting near the midpoint of guidance for $3.04 to $3.09 and $2.125 billion to $2.140 billion. Revenue growth of roughly 15% from the year-ago $1.85 billion would mark a strong pace for a software company of this size, though part of the lift now comes from acquired revenue rather than the core franchise. The Earnings Whisper of $3.16 sits above both consensus and the top of the guided range, implying that the informal bar assumes another clean beat rather than a quarter that simply lands where Autodesk said it would. That matters because Autodesk beat the high end of its revenue outlook last quarter, and a merely in-line print could feel like a step backward.
The most useful evidence will be on organic momentum. Management argued that the second-half raise reflected genuine business improvement, not just the flow-through of earlier beats, and that most regions had normalized from the go-to-market overhaul sooner than expected. Validation would look like billings tracking toward the raised full-year range of $8.575 billion to $8.65 billion, continued construction growth above 20%, and signs that Western Europe, the one region still lagging in new-business productivity, is catching up. A quarter in which reported growth looks fine but leans heavily on MaintainX would challenge the claim that the core accelerated. That distinction may be harder to parse now that Autodesk is no longer breaking out design and make revenue, so commentary on organic billings carries extra weight.
MaintainX itself is the second test. Management folded about $60 million of second-half revenue and $70 million of billings from the deal into guidance and pitched the business as the launch of an Operations segment growing more than 50% on its own. Early integration progress, cross-selling with tools like Forma and Tandem, and further enterprise digital twin wins like last quarter's large retailer deal would support that story. The cost side is the other half: the acquisition is unprofitable, the full-year non-GAAP margin target of about 39% was held rather than raised, and free cash flow guidance was narrowed to absorb deal costs. Holding margins near plan while absorbing a money-losing acquisition would reassure investors that the drag is as contained as promised.
Looking ahead, the fourth quarter holds the largest enterprise agreement renewal cohort of the year, and the AEC business is navigating the retirement of its longtime leader. Any update on renewal pipeline health or the succession search could shape how the market reads the year-end outlook, especially since full-year earnings guidance of $12.52 to $12.60 already sits close to Street expectations.
Sentiment is slightly bearish but marginally less so than before the last report, and the stock has edged up about 1% since then while the S&P 500 slipped, a modest vote of confidence. At about $264, shares trade well above the 200-day moving average and in the upper portion of their post-earnings range, though still roughly 5% below the $279 high. The verdict will hinge on whether Autodesk can show that organic billings are holding at the raised pace while MaintainX adds growth without eroding profitability. If both hold, the improving narrative stays intact; if the core softens beneath acquired revenue, last quarter's optimism will look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-12 | |
| Nov-11 | |
| Nov-09 | |
| Nov-02 | |
| Oct-28 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-13 | |
| Oct-09 | |
| Oct-09 | |
| Oct-08 | |
| Oct-06 | |
| Oct-06 |
