Vipshop's Shrinking Top Line Faces A Test As Outlets And Members Try To Offset Weak Demand
Vipshop heads into its third-quarter report with a credibility question rather than a growth story. Last quarter, management retreated from talk of a path back to growth and instead framed the business around navigating a cautious, value-hunting Chinese consumer, cutting its full-year view to slightly negative revenue. The upcoming release will show whether that reset was conservative enough, or whether the online discount retailer is still searching for a floor.
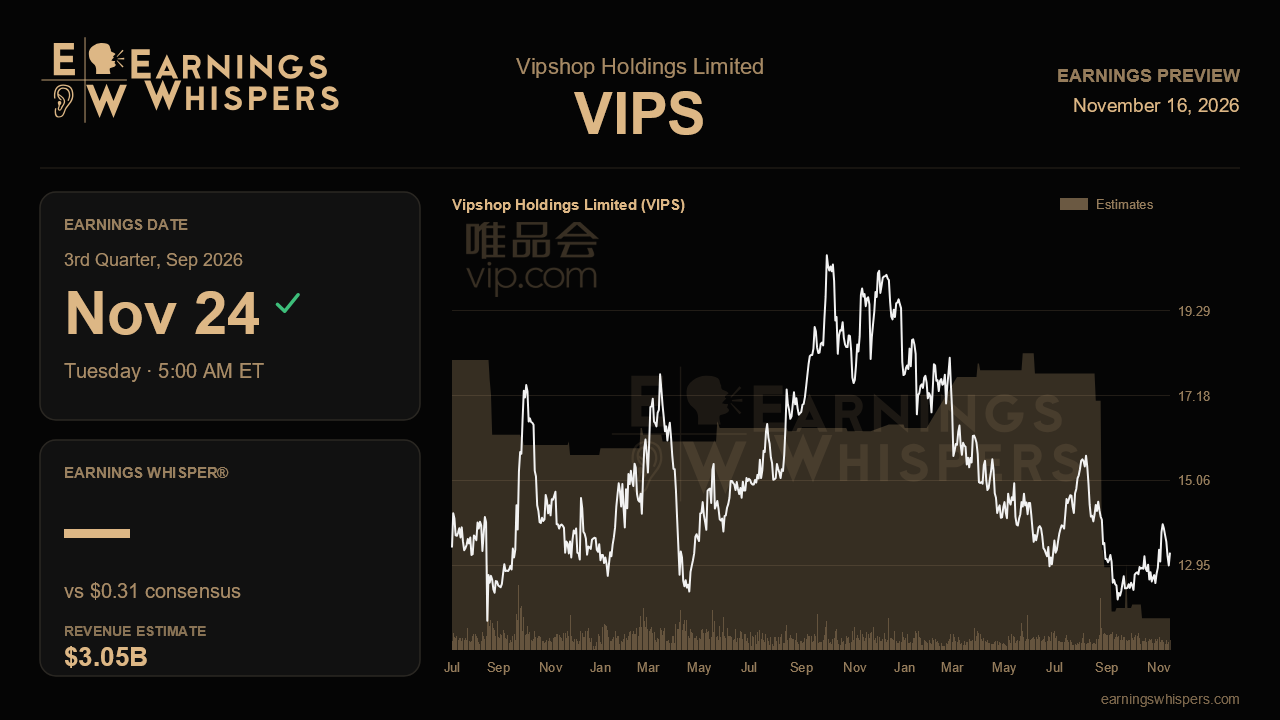
The Street expects GAAP earnings of $0.31 per share, a touch below the $0.33 earned a year ago, on revenue of about $3.05 billion. That revenue figure implies roughly 1.6% growth in dollar terms, which looks better than the underlying setup: in local currency, management guided to a decline of 0% to 5%. Its dollar range of $3.02 billion to $3.18 billion puts consensus near the low end, so analysts have effectively priced in the weaker half of the outlook. That matters because Vipshop landed at the bottom of its guided range last quarter, when revenue fell about 4% year over year. Another low-end print would be roughly what the market expects; a result toward the top of the range would be the first sign that demand stabilized after a summer management described as only slightly better than June and still far from good.
Margins may be the more revealing swing factor. Non-GAAP operating margin slipped to 8.1% last quarter from 9.3% a year earlier, and the culprits were structural rather than promotional. Gross margin held near 23%, showing merchandising discipline, but fulfillment costs climbed to 8.7% of revenue as return rates rose, while fixed costs weighed more heavily on a shrinking sales base. If return rates kept rising and revenue contracted again, the EPS estimate could prove vulnerable even with stable gross margins. Evidence that fulfillment expense stopped deleveraging would validate the view that last quarter's squeeze was cyclical rather than a lasting erosion of the model. Clean earnings also matter after the prior quarter's loss, which was muddied by a roughly RMB1.6 billion withholding tax accrual on past dividend repatriation; investors will want clarity on how much higher ongoing tax costs on offshore cash might run.
The bright spots management leaned on deserve scrutiny too. Super VIP members topped 10 million, with active members up 8% and accounting for 54% of online spending, though that share dipped from 55% in the first quarter. Continued member growth would suggest the core loyal customer remains engaged even as casual traffic stays muted. Shanshan Outlets, which grew GMV 20% in the first half, carries a full-year target above 20% and at least double-digit same-store growth, so any slippage there would remove a key cushion. Updates on the AI marketing tools, the refreshed brand campaign and the pipeline of 18 outlet projects eligible for future REIT securitization will indicate whether these initiatives can move traffic or simply recycle capital.
Sentiment has warmed slightly, with readings still bearish but far less so than heading into the last report. The stock has not shared that thaw. Shares are down 5% since the prior release, lagging the S&P 500 by 3.5 points, and at $13.26 they sit below the 200-day moving average of $14.43, in the lower part of the post-earnings range between $12.02 and $14.93. The new $1 billion buyback and a commitment to return at least 75% of last year's non-GAAP net income offer support, but have not yet convinced the market that the business has bottomed.
Ultimately, the report hinges on whether Vipshop's contraction is orderly. Revenue inside guidance, steady operating margins and a fourth-quarter outlook that does not cut further would confirm that last quarter's caution was a reset, not the start of a slide. Another low-end result with widening fulfillment pressure would suggest the slightly negative year is still not the bottom.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-16 | |
| Nov-12 | |
| Aug-25 | |
| Aug-25 | |
| Aug-17 | |
| May-21 | |
| May-21 | |
| May-21 | |
| May-11 | |
| Apr-16 | |
| Mar-10 | |
| Mar-01 | |
| Feb-27 | |
| Feb-26 |
