Titan Machinery's Rally Meets A Tough Second-Half Ag Test As Europe Weakens
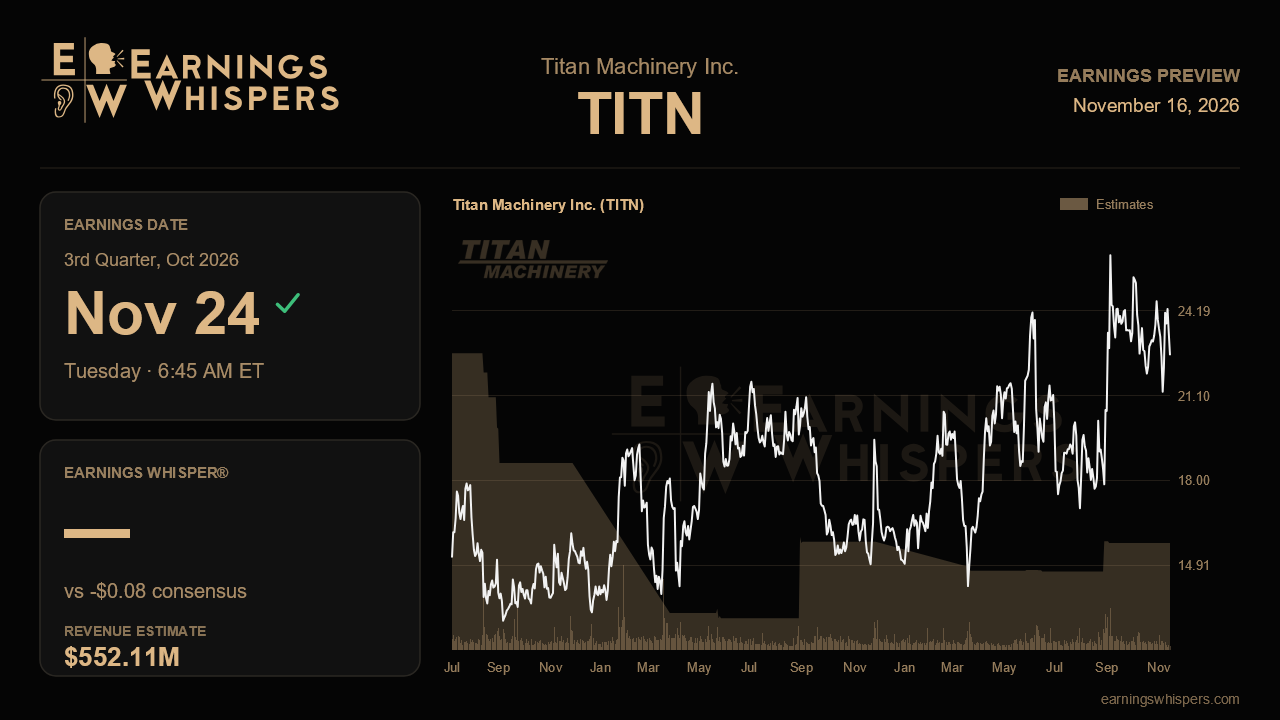
Titan Machinery shares have climbed roughly 32% since the company last reported, even though management used that report to cut its European outlook and warn that domestic farm equipment sales would get worse in the back half of the year. That gap between a recovering stock and a still-deteriorating top line is what makes the fiscal third-quarter release, due before the open on November 24, worth close attention. The market appears to be betting that 2026 marks the bottom of the ag cycle. This report will show whether the company's cost and margin work can carry earnings while demand keeps shrinking.
The Street expects a loss of about 8 cents a share on revenue of roughly $552.1 million. That would be a 14.3% revenue decline from the $644.5 million posted a year ago and a swing from a 5-cent profit to a loss. It would, however, be a sharp improvement from the 40-cent loss in the second quarter, consistent with this being a seasonally heavier delivery period. For the full year, management held its adjusted loss outlook at $1.25 to $1.75 a share, a range it has now reaffirmed across three straight calls. The consensus of a $1.50 loss sits right at the midpoint. Revenue is a different story. The company trimmed its sales range to $1.953 billion to $2.075 billion, yet the full-year consensus of about $2.13 billion still sits above the top of that range. Some estimates may need to come down, and a quarterly revenue miss would not be shocking even if profitability holds up.
The second-half setup is harder than the first. Management said domestic ag equipment sales should fall about 20% in the back half, versus 13.5% in the first half, because pre-sold factory shipments were pulled into earlier quarters. Europe is the bigger worry. The segment's outlook was cut to a 30% to 40% decline from 20% to 25%, and only about $44 million of that reflects the planned German wind-down. The rest is broader regional softness tied to weak commodity prices, high costs and Black Sea uncertainty. If European sales fall at a pace near the low end of that new range, or if the segment's pre-tax loss deepens, the case that the cut fully reset expectations gets weaker.
The offsets are in the parts of the business Titan controls. Equipment margins have risen steadily, reaching 8.5% in the second quarter. With the first half at 8.2%, the roughly 8.3% full-year target requires margins to hold firm as sales volumes fall. Floorplan interest is now guided down about 30% for the year, helped by leaner used and aged inventory. Construction, where same-store sales rose 9.2% on infrastructure and data center work, and Australia, where guidance was raised to as much as 20% growth, offer the clearest growth signals. Continued strength there would support the view that the company is no longer purely a farm-cycle story. One caution flag: operating expenses were guided higher, to 17.5% to 18% of sales, so cost discipline on a smaller revenue base deserves scrutiny.
Sentiment has flipped from moderately bearish ahead of the last report to moderately bullish now, and the stock has beaten the S&P 500 by about 34 percentage points over that span. At $22.57 it trades comfortably above its 200-day moving average. It has also pulled back about 16% from its post-earnings high of $26.90, a sign that some of the early enthusiasm has already been tested. With better corn prices and renewed Chinese buying cited as tailwinds, investors will want management to sound more confident about the next planting season, not just about this year's cost cuts.
The central question is whether margin gains, lower interest costs and the construction and Australian businesses can fully absorb a steeper second-half ag decline and a worsening Europe. If equipment margins stay near 8.5% and Titan reaffirms its loss and EBITDA ranges again, the bottoming narrative stays intact. Another European downgrade or slipping margins would suggest the rally got ahead of the fundamentals.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-10 | |
| Aug-31 | |
| Aug-27 | |
| Aug-27 | |
| Aug-27 | |
| Aug-27 | |
| Aug-13 | |
| Jun-09 | |
| Jun-09 | |
| Jun-09 | |
| Jun-09 | |
| May-19 | |
| Mar-19 | |
| Mar-19 |
