Smucker's Tariff Windfall Raised The Bar; Now Uncrustables And Costs Must Carry It
J.M. Smucker enters its fiscal second-quarter report with a better story than it has had in a year, and a harder job proving that story does not depend on a one-time gift. Last quarter's results were lifted by an 84-cent tariff refund, an early hit on its leverage target and a raised full-year outlook. The question now is whether the underlying business, without a fresh windfall doing the heavy lifting, can keep pace with expectations that have quietly moved up.
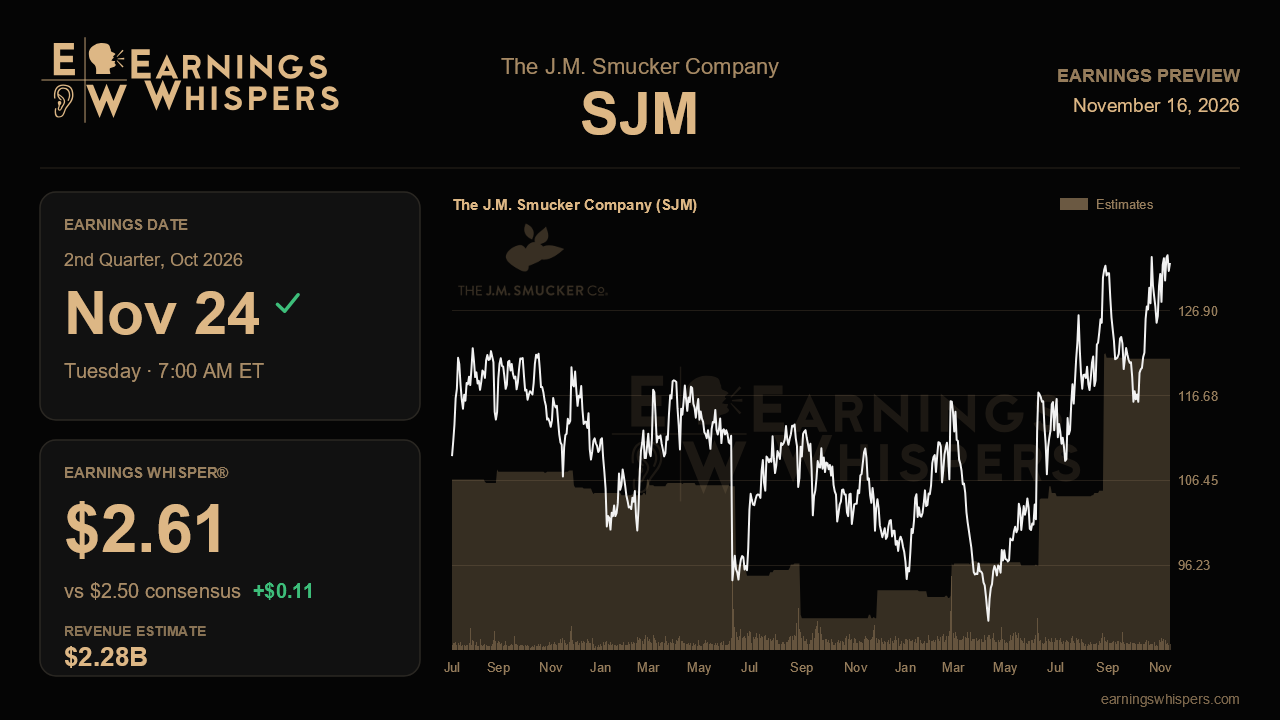
Wall Street expects earnings of $2.50 per share on revenue of $2.28 billion when Smucker reports before the open on November 24. That implies roughly 19% earnings growth from the $2.10 earned a year ago, even as sales slip about 2%. It is a classic packaged-food profile: margin recovery and cost discipline doing the work while the top line contracts modestly. The Earnings Whisper sits at $2.61, about 4% above consensus, a meaningful gap for a staples company and a sign that the real bar is higher than the published number suggests.
Guidance reinforces that view. Management lifted its fiscal 2027 earnings outlook to $10.50 to $11.00 per share from $9.75 to $10.25, and raised its revenue range to $8.87 billion to $8.96 billion. The full-year consensus of $9.98 sits below even the old midpoint, which looks stale relative to the new range, while the revenue consensus of $8.87 billion rests at the bottom of the guide. Either analysts are skeptical that the refund benefit, which management expects to net out to about 60 cents for the year after reinvestment, will fully reach the bottom line, or estimates have simply not caught up. A clean quarter could force that catch-up.
The operating evidence matters most in three places. First, Uncrustables. Management raised its growth outlook to high single digits from mid-single digits, citing the fridge-friendly conversion and recovering away-from-home demand, and pulled forward the start-up of Phase 2 capacity in McCalla, Alabama. Continued traffic gains would validate that call, though the same early start-up brings pre-production costs that management warned would nudge frozen handheld and spreads margins slightly lower for a few quarters. A dip there is expected; a deeper one would not be. Second, coffee. Folgers held roughly flat on volume and mix while Cafe Bustelo grew 23%, and a planned list-price cut was shelved because green coffee costs had not fallen far enough. Holding volume at elevated prices is the swing factor for both revenue and margin. Third, costs. Underlying inflation excluding coffee and tariffs moved up about a point to the mid-single digits on freight and ingredients, the main crack in last quarter's narrative. If gross margin absorbs that without help, the guidance raise looks durable.
Sweet Baked Snacks remains the laggard, with management expecting the first half to be weaker than the full year's low-single-digit decline as it laps product rationalization and convenience-store traffic stays soft. Pet snacks, by contrast, showed life with Pepperoni and Milk-Bone returning to growth, and sustaining that would ease a long-standing concern.
Sentiment has warmed noticeably, with bullish readings well above where they stood before the last report, yet the stock has essentially tracked the S&P 500 since then. Shares trade about 18% above their 200-day moving average and within 3% of their post-earnings high of $136.22, approaching a breakout from a range that has shifted decisively higher than last quarter's. With leverage near 3.0 times, any firmer commitment to share repurchases would add support. Ultimately, this report hinges on whether Smucker can show that Uncrustables momentum and coffee pricing are outrunning rising freight and ingredient costs. If they are, the raised guidance looks conservative; if not, last quarter's upgrade starts to look like a tariff story rather than a turnaround.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-16 | |
| Nov-12 | |
| Nov-04 | |
| Nov-03 | |
| Oct-26 | |
| Oct-22 | |
| Oct-16 | |
| Oct-10 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-06 | |
| Sep-25 | |
| Sep-16 |
