GameSquare Misses On Revenue And Earnings As Ether Gains Mask The Loss And Guidance Now Leans On FanEngine
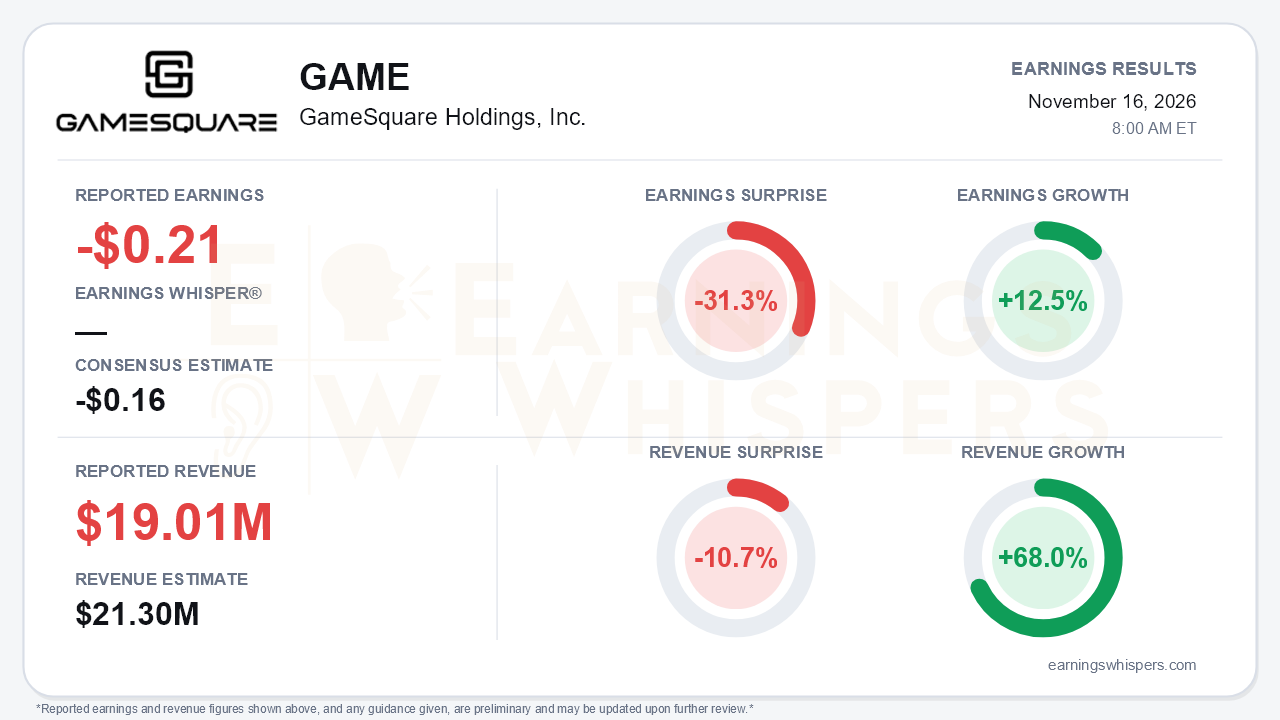
GameSquare Holdings (NASDAQ: GAME) reported a third-quarter loss of $0.21 per share on revenue of $19.01 million. That missed the consensus estimate of a $0.16 loss by 31.3% and the $21.3 million revenue consensus by 10.7%. On the Earnings Whispers basis, earnings still improved 12.5% from a year ago, meaning the loss narrowed, and revenue grew 68.0%. The company reaffirmed its 2026 outlook, but that reaffirmation is the central tension of the quarter. Guidance held only after the newly closed FanEngine acquisition was folded in, which covered for an organic shortfall and roughly $5 million of treasury yield that never materialized.
The quality of the headline deserves scrutiny. GameSquare's GAAP statements show net income from continuing operations of $10.1 million, or $0.79 per diluted share. That figure rests entirely on $14.2 million of realized and unrealized gains on digital assets. Before those gains, the company posted an operating loss of $3.9 million, wider than the $3.0 million loss a year earlier. Operating expenses rose to $12.9 million from $8.0 million, driven by higher general and administrative and selling costs. Share-based compensation alone was $3.1 million.
Adjusted EBITDA was positive at $0.6 million, or 3.1% of revenue, compared with a $0.6 million loss a year ago. That marks a second straight positive quarter, but it is a thin result by any measure. The growth figures also differ by source. Earnings Whispers puts year-over-year revenue growth at 68.0%, while management cited 77%, apparently based on a different prior-year continuing-operations base. Either way, growth slowed sharply from the 137% management reported for the second quarter.
The sequential picture softened more than the year-over-year comparison suggests:
- **Revenue** inched up to $19.0 million from $18.5 million in the second quarter.
- **Gross margin** slipped to 47.5% from 49%.
- **Adjusted EBITDA** fell to $0.6 million from $1.0 million.
Management attributed the shortfall to two factors. The conflict in the Middle East stalled auto and airline deals in the region, and brands held back gaming marketing commitments ahead of the GTA 6 launch. There were real bright spots. Agency-of-record clients, including Dairy Max, Jack in the Box and Roblox, renewed at 100% for 2027. The content division is tracking to roughly double its revenue in 2026. The company also launched Hatchet's AI creator-intelligence platform and opened an Asia-Pacific division.
The tone, however, shifted noticeably. In the second quarter, management said it was "more confident than ever" and spoke of exceeding guidance. On this call, it addressed a cash-burn "perception," voiced frustration with the share price and pointed to the 1-for-8 reverse split completed in August to preserve the Nasdaq listing.
The forward story now rests heavily on FanEngine. Management expects the Peaky Blinders digital fan experience to contribute high-seven to low-eight figures of high-margin fourth-quarter revenue. It also floated a first 2027 framework of about $150 million in revenue:
- **Core business:** roughly $100 million in revenue and $10 million in EBITDA, assuming about 20% organic growth.
- **FanEngine:** roughly $50 million in revenue and $20 million in EBITDA.
The math for 2026 is demanding. Nine-month pro forma revenue was $53.3 million, with adjusted EBITDA of just $0.9 million. Hitting $85 million to $90 million in revenue and more than $5 million in adjusted EBITDA implies a fourth quarter of roughly $32 million to $37 million in revenue and over $4 million in EBITDA. That would be close to double the current quarterly revenue run rate.
The reaffirmed 35% to 40% gross-margin range also sits well below the 46.7% pro forma margin posted through nine months. That gap is difficult to square with the high-margin framing of the FanEngine revenue. Bears have legitimate ammunition here: execution risk on an untested IP model, a back-end-loaded year and 2027 targets that assume FanEngine immediately becomes the most profitable part of the company.
The balance sheet offers some flexibility, but it is not comfortable. Cash and digital assets totaled $31.2 million, or $2.38 per share, up from $25.9 million at the second quarter. Against that:
- **Cash on hand** was only $4.9 million.
- **Current promissory notes** stood at $10.8 million.
- **Accounts payable** were $19.4 million.
- **Receivables** swelled to $14.6 million.
Management says short-term debt will be repaid by year-end as it sells ETH and that no financing is needed. Investors will want to see that happen, because converting volatile ether into cash is now doing much of the balance-sheet work. GameSquare has also repurchased about $5.6 million of stock at an average of roughly $3.49 per share, well above where the stock now trades.
The market had already turned skeptical before the report. Shares closed at $2.21 on November 13, down 27.8% from the $3.06 open after the August report. The stock sits 25.6% below its 200-day moving average of $2.97 and 42.6% below the September 11 inter-earnings high of $3.85. It is also just 2.3% above the October 27 low of $2.16. Investor sentiment, already negative, slipped modestly from -0.32 to -0.37. That is a measured deterioration rather than capitulation. Price-based trend readings remain negative, even as momentum readings are more constructive.
The bottom line is that GameSquare's quarter was weaker than its GAAP profit implies. The company missed on both revenue and normalized earnings, organic growth decelerated and margins slipped. Its full-year guidance now survives only by leaning on an acquisition that has yet to prove itself. The agency renewals, content growth and FanEngine catalyst preserve a credible upside story, and the stock already reflects considerable doubt. Still, the fourth quarter has become a show-me period, and management has left itself little room for another shortfall.
Read our earnings preview for GameSquare Holdings, Inc.: https://www.earningswhispers.com/article/GAME/23056
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-17 | |
| Nov-16 | |
| Nov-16 | |
| Nov-13 | |
| Nov-12 | |
| Nov-08 | |
| Nov-05 | |
| Nov-02 | |
| Oct-26 | |
| Oct-20 | |
| Oct-05 | |
| Oct-01 | |
| Sep-22 | |
| Sep-11 | |
| Sep-10 |
