Nutanix Must Prove Its Beat-And-Raise Turn Can Survive Persistent Server Shortages
Three months ago Nutanix delivered the kind of quarter that ends arguments. After two straight guidance cuts tied to server shortages and delayed contract start dates, the company beat every metric it had guided, lifted its operating margin well past plan, and opened fiscal 2027 with a confident outlook. The stock has fallen roughly 15% since then, trailing the S&P 500 by more than 13 percentage points. When Nutanix reports fiscal first-quarter results after the close on November 24, the question is whether the fundamentals still match the optimism of August, or whether the market is right to doubt that the turn will hold.
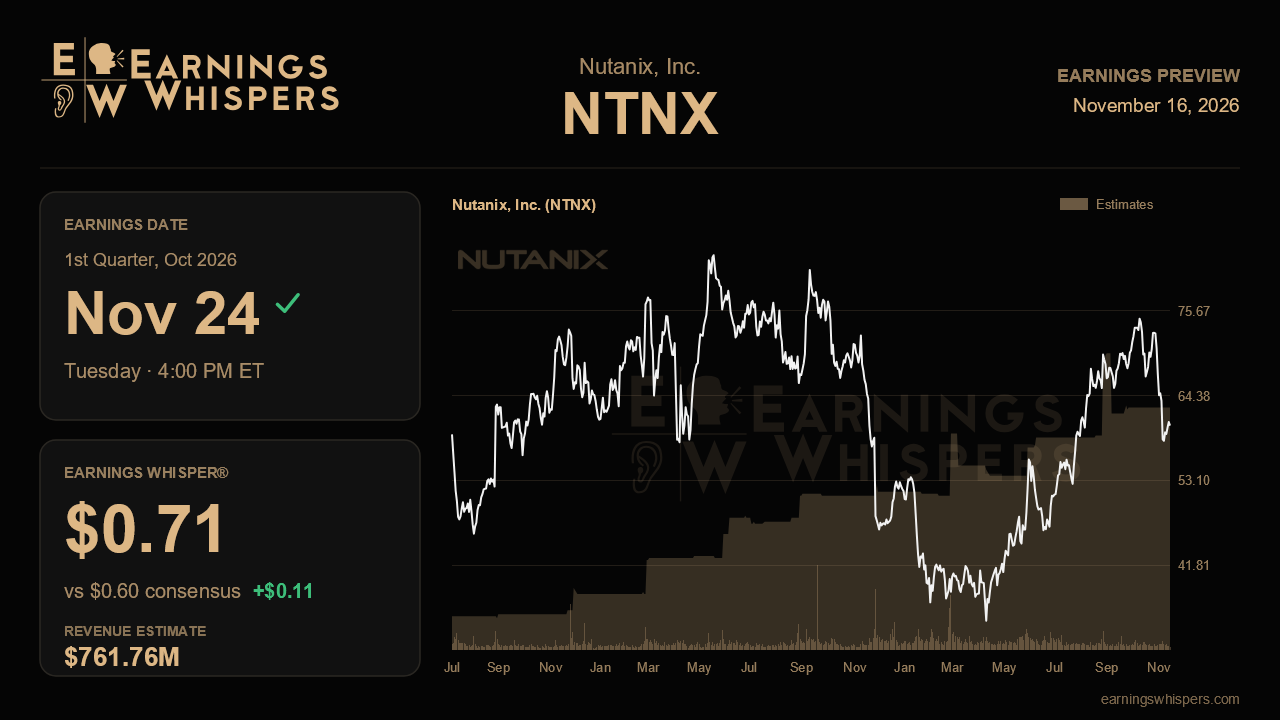
The Street expects non-GAAP earnings of $0.60 per share on revenue of $761.8 million, up about 13.6% from a year ago. That revenue estimate sits slightly above the midpoint of management's $755 million to $765 million guidance, which was itself set above the Street's prior view. The real bar is higher than consensus suggests. The Earnings Whisper sits at $0.71, nearly 20% above the published estimate, a sign that many traders expect the profit upside seen last quarter to repeat. That expectation is not unreasonable. Nutanix posted a 26.2% operating margin in the fourth quarter against a 21% to 23% guide, and full-year free cash flow came in at $841 million versus a $760 million to $780 million target. A company that has shown that much conservatism tends to get credit for it, and anything close to the midpoint may feel like a letdown.
The operating story rests on a few claims that this quarter can test. Annual recurring revenue growth re-accelerated to 16% in the fourth quarter, and holding or improving that pace would confirm that demand, not just timing, drove the recovery. External storage support is the newest catalyst. After a slow start, bookings jumped sharply in the fourth quarter, with several seven-figure wins helped by integrations with NetApp, Dell PowerStore, EverPure and Lenovo. A second consecutive step up would suggest that letting customers keep their existing storage arrays is opening doors that were previously closed, especially among companies leaving rival virtualization platforms. Continued growth in NC2 bookings, early traction with the AMD agentic AI partnership, and any follow-on deals in the neocloud market after the Chronoscale win would add to that case.
The risks are just as concrete. Management now expects CPU and memory shortages and higher server prices to last through all of fiscal 2027, along with a somewhat larger share of orders that start in future periods. Those factors caused the cuts earlier in fiscal 2026, so any sign that shipments slipped or that deferred start dates grew faster than planned would revive old worries. Net revenue retention has slipped from 109% to 106% over the past year, and a further decline would raise questions about expansion within existing accounts, particularly since the renewal cohort is expected to grow more slowly this year. Cash conversion matters too. Management already guided free cash flow margin down to about 28% as it offers more annual billing and payment plans, and investors will want that shift to show up as a deliberate trade-off rather than a sign of weakening pricing power. Costs from the roughly 5% workforce reduction will also cloud GAAP results.
Sentiment has turned somewhat more bearish than before the last report, and the stock, at about $60, sits close to the bottom of its post-earnings range of roughly $58 to $76, though still above its 200-day moving average near $53. That positioning means a clean report could find a receptive audience, while a break below the recent low would show the market still doubts the recovery.
The key issue is whether August marked a real inflection or a single strong quarter. If ARR growth holds near 16%, external storage bookings keep climbing, and management reaffirms or raises its full-year outlook despite the supply constraints, the recent selloff will look like a gap between price and performance. If supply problems and deferred start dates return to explain a soft spot, investors will likely conclude the turnaround is less durable than it first appeared.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-26 | |
| Oct-09 |
This AI Stock Snatches Share, Eyes Entry As Funds Pile In. Earnings Are Soaring.
NTNX
Investor's Business Daily
|
| Oct-08 | |
| Sep-24 | |
| Sep-23 | |
| Sep-22 | |
| Aug-27 | |
| Aug-27 | |
| Aug-27 | |
| Aug-27 | |
| Aug-26 | |
| Aug-26 | |
| Aug-25 | |
| Jun-01 |
