XBP Global's Record Margins And Bookings Clash With A Deepening Revenue Slide, A Pushed-Back Inflection And A $68M Write-Down
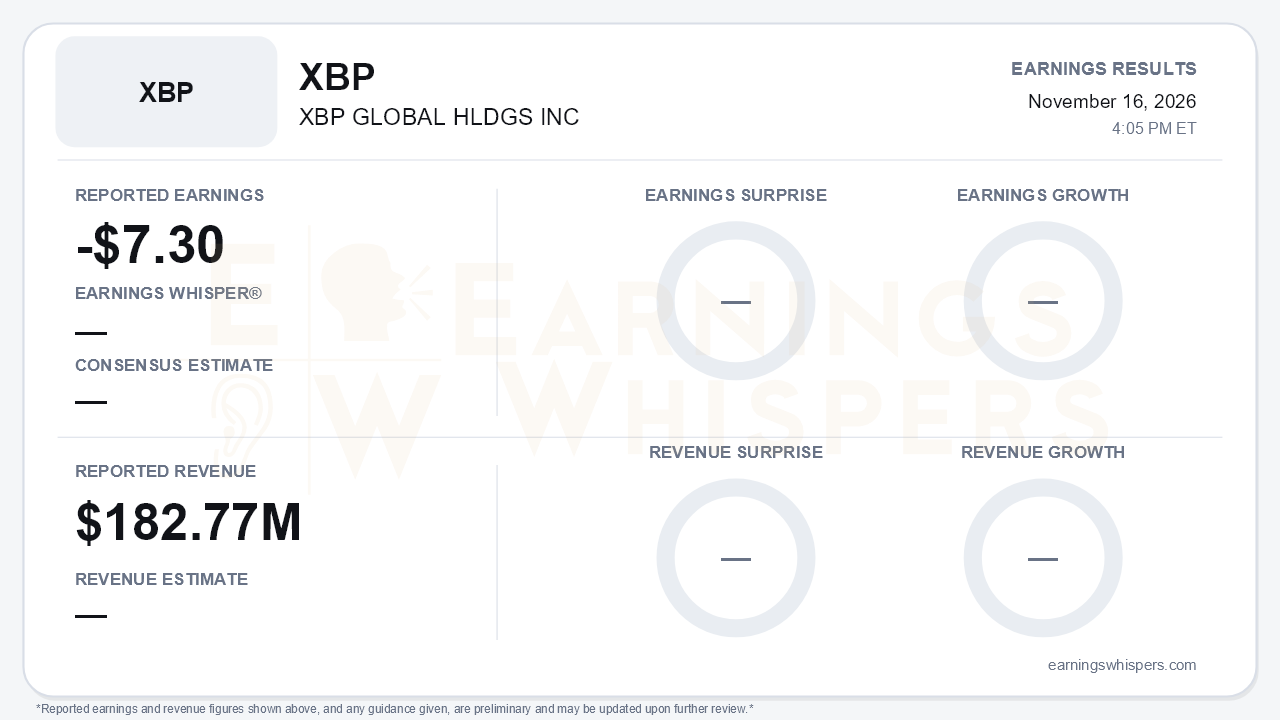
XBP Global reported a GAAP loss of $7.30 per share for the September quarter on revenue of $182.77 million. No consensus estimate was available, so there is no clean beat-or-miss read. The headline loss is dominated by a $68.4 million non-cash goodwill impairment, which drove an $89.0 million net loss. Beneath it sits a quarter with two opposing trends. The cost side of the turnaround keeps working: normalized EBITDA margin hit a combined-company record of 12.4%, and bookings were the strongest since the July 2025 combination. The top line, however, is shrinking faster, not slower, and the promised inflection keeps moving out. That is the central tension.
The revenue picture deteriorated. On a pro forma basis, sales fell 17.1% year over year, worse than the roughly 14% declines in each of the first two quarters. Revenue fell 4.5% sequentially, extending a run of $207 million, $197.1 million, $191.3 million and now $182.8 million. Management attributes the decline to the planned run-off of client exits tied to restructuring.
Profit quality also deserves scrutiny:
- Normalized EBITDA of $22.6 million rose only 3.3% sequentially and fell 8.5% year over year, reversing the year-over-year gain reported in the second quarter.
- That figure includes about $1.9 million of add-backs for annualized run-rate savings not yet fully realized.
- GAAP gross margin did improve 200 basis points sequentially to 23.5%.
- Adjusted gross margin, however, slipped 50 basis points to 24.4%.
The call showed where the improvement is real and where it is fading. Margin gains in the core automation-heavy operations look genuine. Adjusted gross margin there rose to 20.3% from 19.2%, which management called the clearest evidence of automation replacing labor. Revenue per employee climbed to $92,000 from $89,000. Management also said headcount reductions will exceed the planned roughly 20%, and it raised the low end of its annualized efficiency target to $70 million to $75 million, still expecting about $35 million of in-year benefit.
The weak spot was the technology segment:
- Revenue fell 14.6% sequentially on lower Americas platform revenue.
- Adjusted gross margin dropped to 56.3% from 64.2%.
The year-end revenue-per-employee goal was also trimmed to about $96,000 from "approaching $100,000."
The forward story rests on bookings, and here the numbers are strong:
- Total contract value of $147.5 million was up 204.8% year over year.
- New annual contract value of $37.5 million was up 103.7%.
- The pipeline grew to $2.6 billion, up 17%.
- Year-to-date new TCV already exceeds all of 2025.
- The British Airways engineering-records deal, built on the Plexus AI platform and run on BA's private cloud, gives the regulated-industry AI positioning a marquee name.
The messaging on when bookings show up as revenue has steadily retreated. Early in the year, management talked about near-term stability and second-half growth. It then described a second-half inflection. Now the commitment is only that fourth-quarter revenue will rise sequentially from a lower base, with no formal guidance. European public-sector clients were described as sluggish due to geopolitics. Bears have legitimate ammunition in that pattern.
The balance sheet is the other pressure point:
- Debt stands at roughly $368 million against $28.7 million of cash.
- Stockholders' equity swung to a $38.3 million deficit from a positive $87.3 million at year-end.
- Quarterly net interest expense of $15.5 million consumes a large share of normalized EBITDA.
- Nine-month operating cash flow was slightly negative.
The company raised about $6.1 million in a private placement for roughly 2.3 million shares, implying a price in the mid-$2 range. That is below the $2.86 opening price after the August report, and it adds dilution. On the positive side, the $6.5 million second lien note was repaid at maturity in October. Management also expects most pre-petition claim payments to be behind it by January, which should ease cash drag in 2027. The strategic alternatives process received no update.
Current sentiment and technical data were not available for this report, so the market's reaction cannot yet be framed against positioning. The financing price does suggest the shares have not rewarded the margin progress since the last report.
The bottom line is that XBP Global is executing well on the controllable half of its turnaround: automation-driven margins, cost targets and bookings all moved in the right direction. The half that ultimately matters for a leveraged company, converting bookings into stable revenue and cash flow, slipped again. Until the promised fourth-quarter sequential increase materializes and the revenue decline visibly narrows, the record margins look more like a cushion against shrinkage than proof of a durable recovery.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-16 | |
| Nov-04 | |
| Oct-08 | |
| Sep-03 | |
| Aug-26 | |
| Aug-14 | |
| Aug-13 | |
| Aug-12 | |
| Aug-04 | |
| Jul-30 | |
| May-15 | |
| May-14 | |
| May-14 | |
| May-12 |
