Data Storage Corp: Nexxis Turns Negative And The AI Platform And M&A Timelines Slip, Leaving Cash As The Main Support
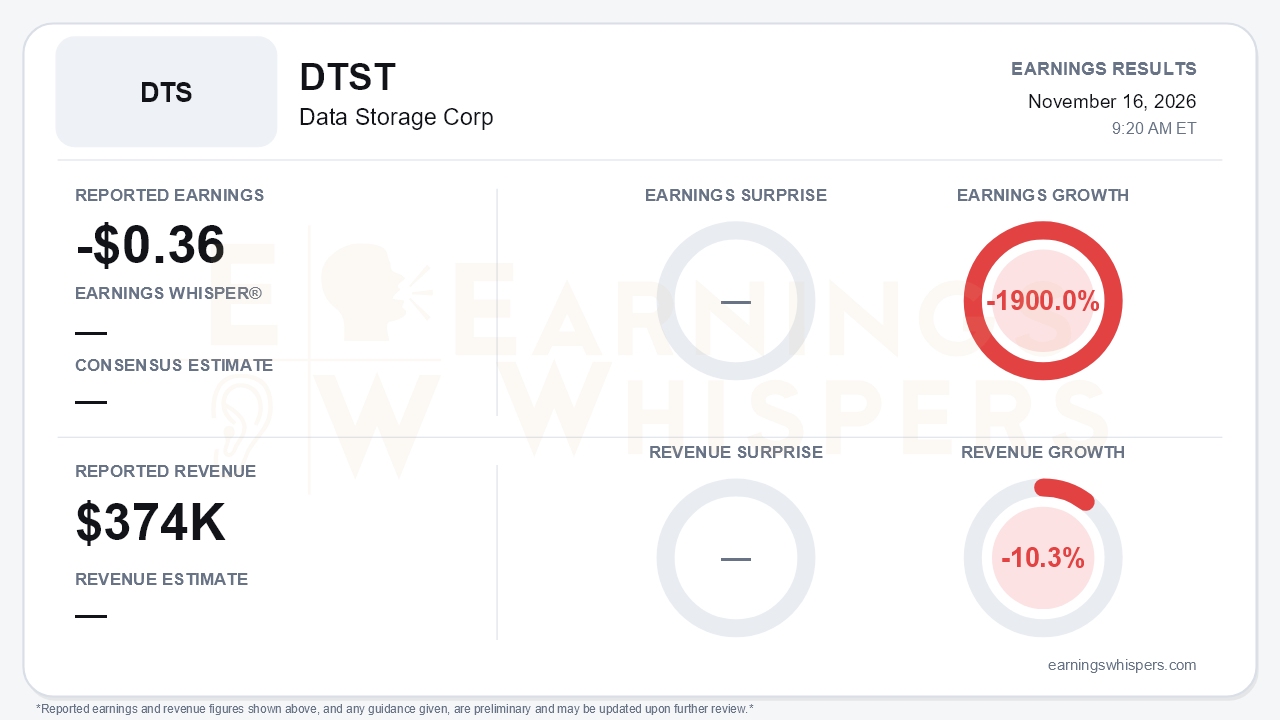
Data Storage Corp (NASDAQ: DTST) reported a third-quarter loss of $0.36 per share on revenue of $0.37 million. Earnings fell 1900.0% year over year, from a $0.02 profit from continuing operations, and revenue fell 10.3%. There was no consensus estimate or Earnings Whisper to measure against, so the quarter has to be judged on its own trajectory. That trajectory weakened. The small Nexxis operating business slipped into a year-over-year decline, margins compressed, and the two initiatives meant to justify the post-CloudFirst strategy both moved further out. Those are the AI Continuity Control Platform and an acquisition.
The headline EPS swing overstates the operating deterioration. The prior-year quarter's $0.02 from continuing operations depended on a roughly $1.02 million tax benefit. Before taxes, the loss from continuing operations actually narrowed, to $830K from $905K. The operating loss also improved, to $886K from $1.10 million, as SG&A fell 19.7% to $1.04 million on lower stock compensation. That is a sharp reversal from SG&A growth of 33.2% in Q2 and 71.8% in Q1.
The per-share math has also changed. The tender offer returned about $29.3 million to shareholders and cut weighted shares to roughly 2.4 million from 7.3 million. Every dollar of loss now carries far more weight per share. The same shrinkage in the cash pile cut interest income to $74K from $193K.
On net loss, the call cited $865K. The release shows a net loss of $851K, or $855K attributable to common holders. The difference is minor, but the release figures are the reported numbers.
The more troubling detail is in Nexxis. Revenue grew 10.9% in Q1 and 9.3% in Q2, then fell 10.3% in Q3 to $374K. Management attributed the decline to existing customers moving to lower-revenue services. Cost of sales held flat at about $218K while sales fell, so gross margin dropped to 41.6%. That compares with 47.6% a year ago, 47.0% in Q2 and 53.7% in Q1, a steady three-quarter slide. Gross profit fell 21.6%.
There are offsets:
- Revenue rose 4.3% sequentially.
- Nine-month revenue is still up 2.0%.
- Nine-month data transport revenue grew 15.9%.
- Nine-month gross margin of 47.3% is above the prior-year period.
Still, customer downgrades are a demand signal, not a timing quirk. Management's response is modest: a $100K to $250K investment over the next year for sales reps, a website and inbound lead generation, plus SkySwitch-based AI voice services. That is an attempt to restart growth, not evidence that growth has resumed.
The strategic story is where the call did the most damage to the setup. Development of the AI continuity platform formally began in Q3. Management added concrete specifications: recovery times of seconds to 15 minutes and on-demand GPU activation without idle standby hardware. The timeline, however, keeps stretching:
- **Q1 call:** management talked about reservations in Q1 2027 or earlier.
- **Q3 call:** first prospect conversations around March-April, a hoped-for first order in June-August, and broad customer rollout in 2028.
M&A has cooled similarly. Q2's hope for a deal or letter of intent in Q4 was not repeated. Instead, the CEO said acquisitions have been "very difficult to find," with more than 100 targets reviewed. Cybersecurity is now named as an explicit complementary focus, but naming a category is not the same as finding a deal. The tone was noticeably more measured than the multi-billion-dollar addressable-market framing of earlier in the year.
That leaves the balance sheet as the real anchor. Cash and marketable securities of $9.5 million rose from $9.3 million in Q2, but only because the final $1.0 million of CloudFirst escrow arrived. Nine-month operating cash outflow was $3.5 million. That figure is inflated by roughly $1.8 million of income taxes paid tied to the sale, and a $632K tax receivable should provide some relief. Still, with continuing losses and roughly $2 million a year in public-company costs, the cushion erodes every quarter that the AI platform and M&A remain pre-revenue.
Stockholders' equity of about $9.5 million against roughly 2.4 million shares outstanding works out to around $3.90 per share. The stock opened at $3.56 after the prior report, which matches its 200-day moving average. Current price and sentiment readings were not available. Even so, the stock appears to have been priced largely as a cash-backed option on the strategic pivot, so the slipping timelines matter more than the tiny revenue line.
The bottom line is that Data Storage Corp's per-share loss looks worse than the operating results. Cost control narrowed the pretax loss, and most of the EPS swing reflects a lapsed tax benefit and a much smaller share count. The underlying story, however, softened on every forward-looking front. Nexxis turned negative with margins sliding, AI platform revenue is now a mid-2027 hope with real adoption in 2028, and the acquisition pipeline has produced nothing. Until either initiative produces something tangible, investors are effectively holding a shrinking cash base and a promise, and this quarter made that promise more distant.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-16 | |
| Nov-05 | |
| Aug-14 | |
| Aug-14 | |
| Aug-06 | |
| Jul-07 | |
| Jun-09 | |
| May-21 | |
| May-15 | |
| May-15 | |
| May-12 | |
| May-05 | |
| Apr-14 | |
| Apr-09 |
