Elauwit's Recurring Engine Accelerates, But An 8.6% Gross Margin And Thin Liquidity Undercut The Q3 Rebound
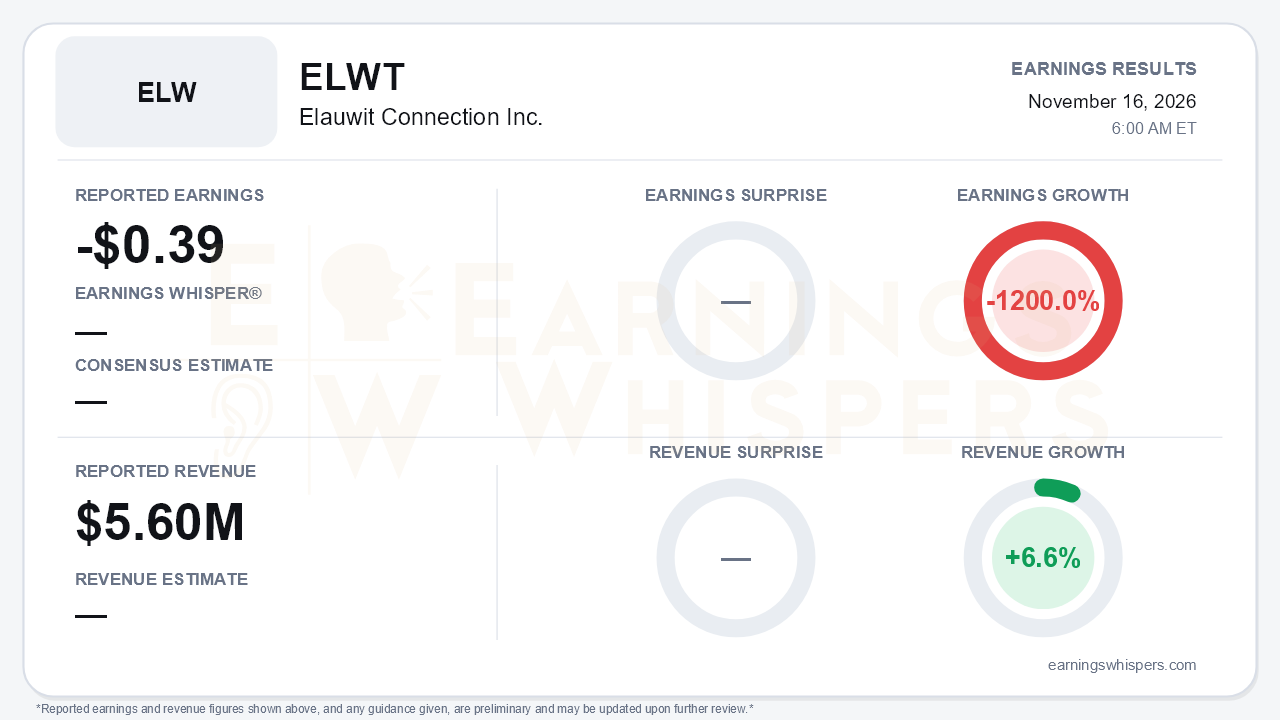
Elauwit Connection (NASDAQ: ELWT) reported a third-quarter loss of $0.39 per share on revenue of $5.6 million. No consensus estimate or Earnings Whisper was available, so there is no surprise to measure. By Earnings Whispers' normalized figures, earnings fell 1200.0% year over year and revenue grew 6.6%.
The company's own comparison against restated year-ago results shows revenue up 17%, from $4.8 million. Investors should note that the two growth figures rest on different bases. Either way, the GAAP net loss quadrupled to $2.6 million from $0.6 million.
That is the central tension. The recurring business is scaling quickly, but the company is still burning through a thin balance sheet while it builds.
The operating metrics are the strongest part of the report:
- Billed units rose 140% year over year and 12% sequentially to 25,746.
- Recurring service revenue climbed 86% to $1.5 million, and is up 101% to $3.9 million for the nine months.
- Monthly recurring revenue, which management now calls its primary KPI, reached $539,000 at quarter-end, up 66%. Management said it topped $600,000 by early November.
- Contracted units grew 43% to 46,955, and management reaffirmed its goal of exceeding 50,000 by year-end.
With roughly 21,000 contracted units not yet billing, management has a credible argument that MRR growth is largely a matter of construction and conversion timing. Sequentially, revenue more than doubled as the promised second-half construction rebound arrived.
The quality of the quarter deserves scrutiny below the top line. Gross profit fell to $480,000 from $1.4 million a year ago. Gross margin compressed to 8.6% from 15.5% in the second quarter, with construction at just 7.3% and recurring services at only 12.5%.
On the call, the company attributed the decline to milestone-based recognition that booked zero-margin revenue. It plans to shift to percentage-of-completion accounting to smooth construction margins. Even so, the recurring margin sits far below the long-term 60–75% target discussed earlier in the year, and that target was not reiterated.
Cost discipline is real but incomplete. Operating expenses fell 19% sequentially to $2.9 million, and adjusted EBITDA loss narrowed to $2.4 million from $3.1 million in Q2. Management has implemented $1.8 million of its $1.9 million SG&A program and identified roughly $1 million in additional savings, including AI-enabled platforms. Still, G&A remains well above the year-ago $1.7 million.
More broadly, the call marked a clear change in tone. Management moved from the 'investment year' framing of earlier quarters to a confident recurring-revenue-platform pitch, complete with an illustrative ~$1,200-per-unit valuation that implies roughly $60 million at 50,000 units. Investors should treat that as management's marketing math, not a valuation; the company itself said so.
The land-and-expand catalysts are tangible:
- Avenue Living, a 21,500-unit owner, selected Elauwit for three communities, with activation targeted for December.
- Two REITs added 14 communities and 4,100 units in July.
- Pipeline units rose to 107,000.
Bears have legitimate ammunition, however:
- Pipeline properties slipped to 450 from 500+.
- Two REIT communities slid to January.
- Activated-unit growth decelerated to 74% from 94% in Q2.
- Nine-month revenue of $12.7 million trails last year's $15.5 million, and management did not repeat its earlier assurance that the full year 'remains robust.'
- Backlog jumped to $53.5 million from $38.9 million, but partly because the definition was broadened without recasting prior periods.
- Prior quarters were revised again.
Liquidity is the most pressing risk. Cash of $2.7 million doubled from June but is down from $6.2 million at year-end. The company carries a $2.9 million working-capital deficit and relies on related-party loans with about $1 million of remaining availability. Stockholders' equity has swung to a $3.4 million deficit from a positive $4.6 million in December.
The $9.0 million of deferred revenue cuts both ways. It shows customers are prefunding work, but it also accounts for much of the working-capital gap.
Market context is limited. Shares opened at $8.18 after the August report, above the 200-day moving average of $6.65, but current pricing and sentiment readings were not available to judge how investors received this quarter.
The bottom line is that Elauwit delivered the recurring-revenue acceleration its thesis depends on, and the unit funnel gives that growth genuine visibility. But single-digit gross margins, a widening GAAP loss, repeated restatements and a balance sheet leaning on related-party credit mean the company must prove it can fund the conversion of its contracted base before the recurring economics can carry the story.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-16 | |
| Nov-12 | |
| Nov-10 | |
| Nov-09 | |
| Nov-05 | |
| Oct-20 | |
| Oct-13 | |
| Aug-18 | |
| Aug-18 | |
| Aug-13 | |
| Aug-13 | |
| Aug-07 | |
| Jul-23 | |
| Jun-17 |
