Agora's Revenue Acceleration Extends To A Third Quarter As The Operating-Profit Target Slips To 2H 2027
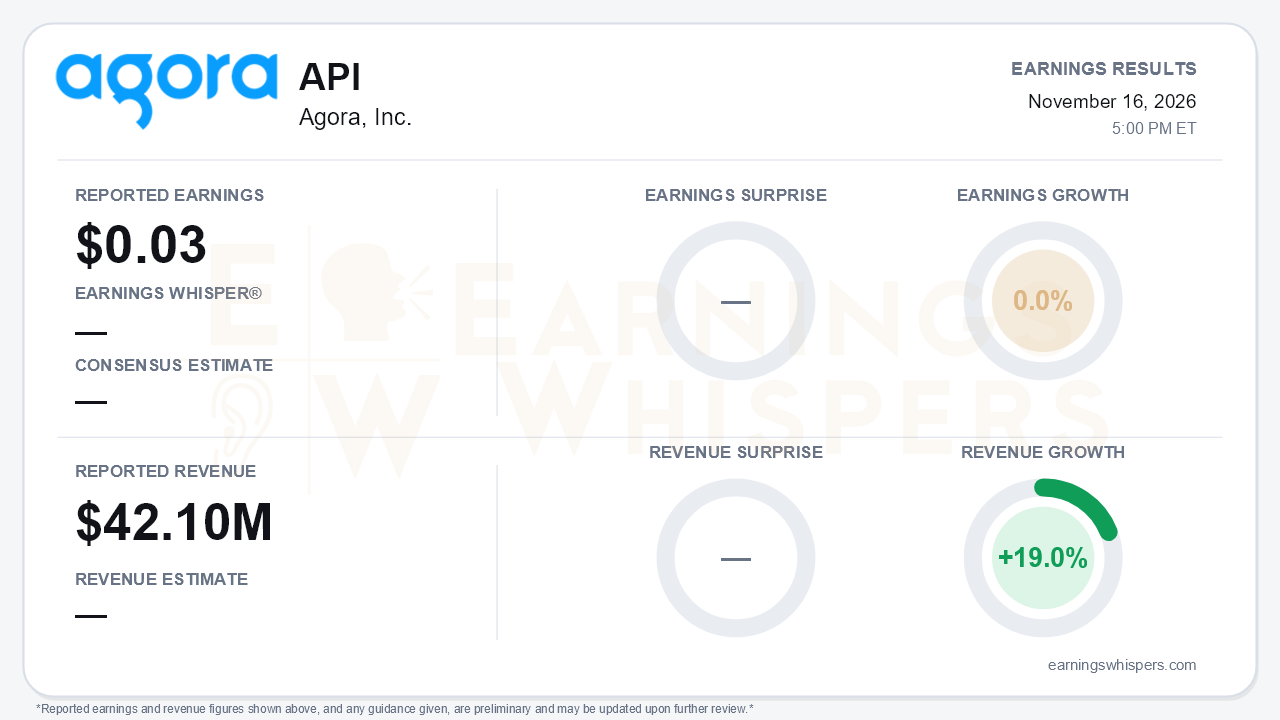
Agora delivered its third consecutive quarter of accelerating revenue growth in the third quarter, but the headline the market will weigh most is the one about profitability. Revenue rose 19.0% year over year to $42.1 million, above the top of the company's $41 to $42 million guidance range. Growth has now moved from 10.7% in Q4 FY25 to 13.5% in Q1, 18% in Q2 and 19% in Q3. Earnings did not keep pace. Diluted EPS was $0.03, unchanged from a year ago, so earnings growth was 0.0%. No consensus estimate was available for comparison. The central tension is clear. The top line and customer economics are improving, but management pushed its GAAP operating-profit target out by roughly a year to the second half of 2027.
The quality of the earnings line deserves scrutiny. Agora still lost $1.5 million at the operating level, slightly better than the $1.6 million loss a year ago but wider than the $1.0 million loss in Q2. Net income of $3.0 million, the company's eighth straight GAAP-profitable quarter, came from below the operating line:
- **Interest income:** $3.6 million, down from $3.9 million a year ago.
- **Investment income:** a $1.3 million fair-value gain on equity investments, versus a $0.3 million loss a year earlier.
Without those items, the core business remains in the red. Gross margin also continued to erode, falling to 63.4% from 66.0% a year ago and 63.7% in Q2. Management attributed the decline to mix, specifically conversational AI products that are still subscale. Cost of revenues grew 27.9%, outpacing revenue. G&A rose 15.9%, partly on higher credit-loss provisions, a reversal from the lower provisions of earlier quarters. Accounts receivable rose to $30.1 million from $24.9 million at year-end.
Underneath, the demand picture is the strongest it has been in some time. Dollar-based net retention climbed to 110%, up from 104% in Q2, 99% in Q1 and 97% a year ago. Existing customers are expanding rather than shrinking. Active customers grew only modestly, to 4,024 from 3,944, so expansion within the installed base is doing most of the work. Management pointed to healthy real-time engagement demand in US and international live shopping and social streaming, plus IoT in China. Conversational AI now handles more than one million agent calls per day across more than a dozen use cases. Operating cash flow turned positive at $2.2 million after negative $2.1 million in Q2. Management's tone was notably more confident.
The forward story is built on conversational AI, and it is a credible growth narrative. Management reiterated its target for conversational AI to reach about 5% of Q4 revenue, a goal it has held on every call since Q4 FY25. It said FY2027 contribution will be "significantly higher." New products include:
- the Agora Conversational Agent System, a full-duplex system with memory, evaluation and self-improvement capabilities;
- a self-serve Call Agent Studio that management says is seeing healthy small-developer adoption.
Management also framed industry adoption of WebRTC for human-to-AI interaction, including by OpenAI, as a tailwind for its infrastructure. Bears have legitimate ammunition, however:
- **A drifting profit target.** The operating-profit goal has moved on every call: Q4 2026, then 2H 2026, then by year-end, and now 2H 2027.
- **No 2027 numbers.** Management offered no numeric FY2027 conversational AI guidance, citing uncertainty about technology and adoption and noting that conversational AI ARPU is not yet stable.
- **Margin timing.** Management said conversational AI gross margin may take a few quarters to reach its target.
- **A softer Q4 guide.** Q4 guidance of $44 to $45 million implies 15.3% to 17.9% growth, which would pause the acceleration streak. Agora has, however, beaten the top of its range every quarter this year.
The market setup was already weak heading into the print. Shares closed at $3.96 on November 13, down 15.6% from the $4.69 opening after the August report. That left the stock about 4.3% below its 200-day moving average and just 3.4% above its inter-earnings low of $3.83, set that same day. The quarter's high of $4.73 came the day after the last report, so the stock has steadily given back its prior post-earnings gains. Investor sentiment moved further into negative territory, falling from -0.23 to -0.40, a meaningful but not extreme deterioration. The trend readings are mixed, with momentum positive while AVWAP remains negative.
Capital allocation offers some cushion but also some complexity. Cash and equivalents totaled $363 million, and the buyback has cut the share count to 333.4 million from 449.8 million at the program's inception. The CEO has also been executing an open-market purchase plan since September. Q3 repurchases slowed to $1.9 million, though, and the program expires in February 2027. Spending on the headquarters project also continues, with $122.6 million in construction in progress funded partly by $103.1 million in related borrowings.
The bottom line is that Agora is growing faster, retaining customers better and pushing conversational AI into real production volume. But it is paying for that growth with lower gross margins and a profitability timeline that keeps receding. Earnings remain dependent on interest and investment income rather than operations. Investors already skeptical going into the report now have a delayed profit target to point to. The bull case rests on whether conversational AI scale arrives fast enough to lift margins before patience runs out.
Read our earnings preview for Agora, Inc.: https://www.earningswhispers.com/article/API/23065
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-16 | |
| Nov-09 | |
| Nov-04 | |
| Aug-14 | |
| Aug-13 | |
| Aug-04 | |
| Jun-17 | |
| Jun-01 | |
| May-26 | |
| May-12 | |
| Apr-22 | |
| Apr-01 | |
| Mar-11 | |
| Mar-06 |
