XP Inc. Misses The EPS Bar As Growth Ambitions Shrink, With A Bigger Capital-Return Package Stepping In
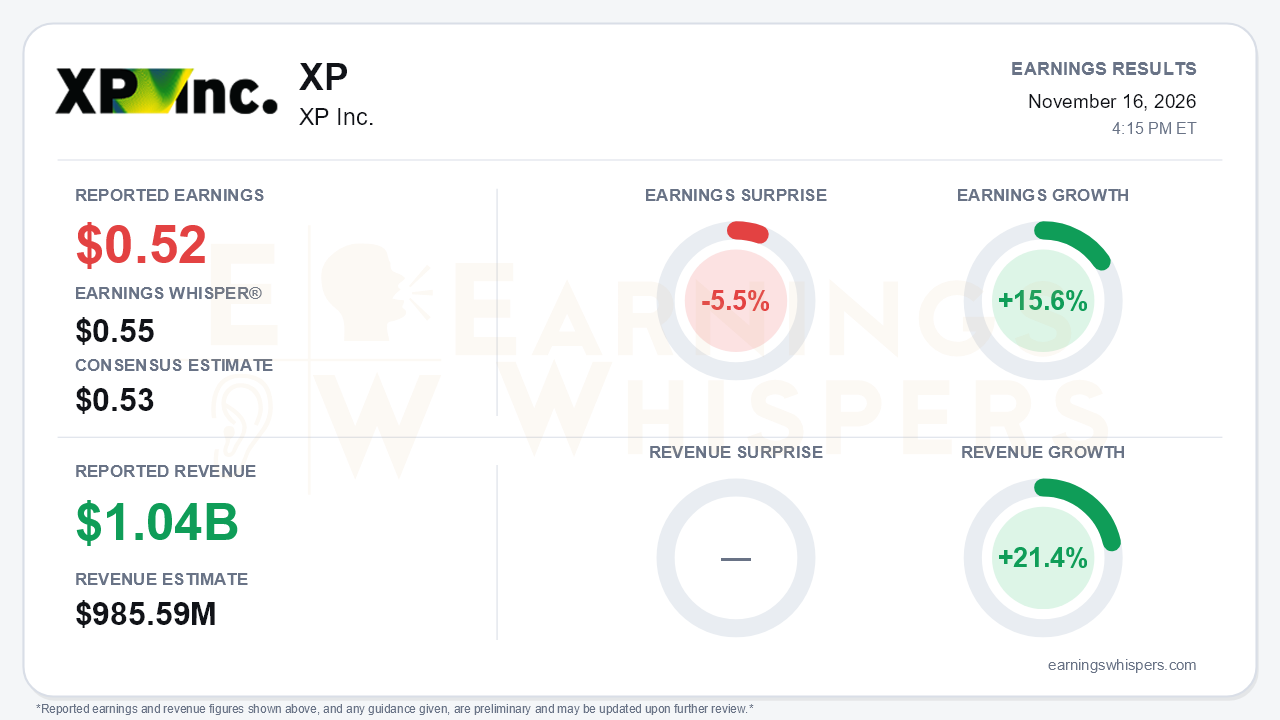
XP Inc. reported third-quarter earnings of $0.52 per share, short of the $0.53 consensus and the $0.55 Earnings Whisper number, a 5.5% miss. Revenue of $1.039 billion beat the $985.59 million consensus by 5.4%. Dollar-denominated earnings grew 15.6% and revenue grew 21.4% year over year, but those figures overstate the underlying pace. In reais, diluted EPS rose 9% to R$2.69, adjusted net income grew only 4% to R$1.38 billion, and gross revenue rose 8%. The gap between dollar and local-currency growth points to currency translation rather than operating acceleration. The central tension is that XP delivered a solid top line but showed decelerating profit growth and a quietly lowered growth ambition. Management answered with a much larger capital return.
The quality of the quarter is mixed. Gross revenue rose 6% sequentially to R$5.3 billion, up from 3% sequential growth in the second quarter. Gross margin expanded to 70.2% from 68.6%. Retail revenue was the bright spot:
- Total retail revenue grew 11% year over year, up from 8% in the prior quarter.
- Equities rose 16%, the funds platform 18%, and credit and insurance 32% each.
- The retail take rate rose 6 basis points sequentially to 1.25%.
That strength did not reach the bottom line. SG&A jumped 14% sequentially and 12% year over year, driven by:
- bonus provisions up 20% from the second quarter;
- non-people expenses up 24%, partly tied to the Expert event.
As a result, EBT margin fell 130 basis points sequentially to 30.7%, and net margin slid to 26.9%. Net income growth has now slowed from 7% in the first quarter to 5% in the second and 4% in the third. Annualized ROAE slipped to 21.7% from 22.5%. Management attributed the lower return partly to capital building up ahead of distributions.
The wholesale story changed most beneath the surface. Wholesale revenue growth slowed to 13% year over year from 32% in the second quarter. Corporate, the engine of that segment, cooled to 55% growth from 117%. Issuer Services fell 40% year over year amid weak debt-capital-markets and tax-exempt issuance, and management described a competitive market in which peers use their balance sheets. Asset gathering also softened:
- Total net inflow fell to R$22 billion from R$28 billion in the second quarter.
- Retail net new money of R$17.5 billion missed the roughly R$20 billion quarterly soft target that management still maintains.
- The release shows client assets up 11% to R$1.57 trillion, and the call framed client-asset growth as slowing steadily through the year.
On the positive side, active clients resumed growth, NPS improved to 67 from 61 in the first quarter, and the fee-based share of retail assets climbed to 27%.
Guidance is where bears have the most legitimate ammunition. The 2026 double-digit revenue growth target, reaffirmed in the first and second quarters, was not reiterated. Revenue has tracked roughly 8% all year, well below the roughly 17% implied by the Investor Day guide. Management instead framed 2027 around roughly 10% top-line growth, with operating leverage as this year's investment spending on new business lines and technology rolls off. That is a credible but more modest growth story.
Capital return is the clear catalyst. XP completed its prior R$1 billion buyback and authorized a new R$1.5 billion program. It also declared a R$1.3 billion dividend payable in 2026 and will cancel about 11.7 million treasury shares, roughly 2.3% of the outstanding count. Management cited a year-to-date payout near 60% and called a floor of at least 50% sustainable. The warehouse book has been cut to roughly 20-25% of its start-of-year size, which should keep mark-to-market losses small after about R$400 million in the first half. Management also flagged possible inorganic opportunities.
Several risks remain:
- Credit risk-weighted asset growth from corporate derivatives, energy, and credit consumes capital.
- A lower share price increases dilution from R$400-500 million in annual RSUs.
- Management described election-related volume spikes as non-sustainable.
Investor sentiment entered the report modestly positive at roughly 0.18, and an updated reading was not available. Shares opened at $15.70 after the August report, well below the current 200-day moving average of $18.98. That positioning fits management's own acknowledgment of a depressed share price and helps explain the push toward buybacks. The Earnings Whispers trend readings are largely neutral, with AVWAP still negative.
The bottom line is that XP produced a respectable revenue quarter but a weaker earnings one. Retail strength and margin gains at the gross level were offset by cost growth, slowing wholesale momentum, and softer inflows. The retreat from double-digit 2026 growth to a roughly 10% 2027 framing resets the growth narrative lower. The enlarged buyback, dividend, and payout floor give shareholders a tangible offset, but delivering operating leverage next year is now the key test.
Read our earnings preview for XP Inc.: https://www.earningswhispers.com/article/XP/23077
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-17 | |
| Nov-16 | |
| Nov-16 | |
| Nov-16 | |
| Nov-09 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Aug-24 | |
| Aug-17 | |
| Aug-17 | |
| Aug-17 | |
| May-19 |
