Opera Misses By A Penny As Growth Slows And The Q4 Outlook Points To Mid-Teens Growth
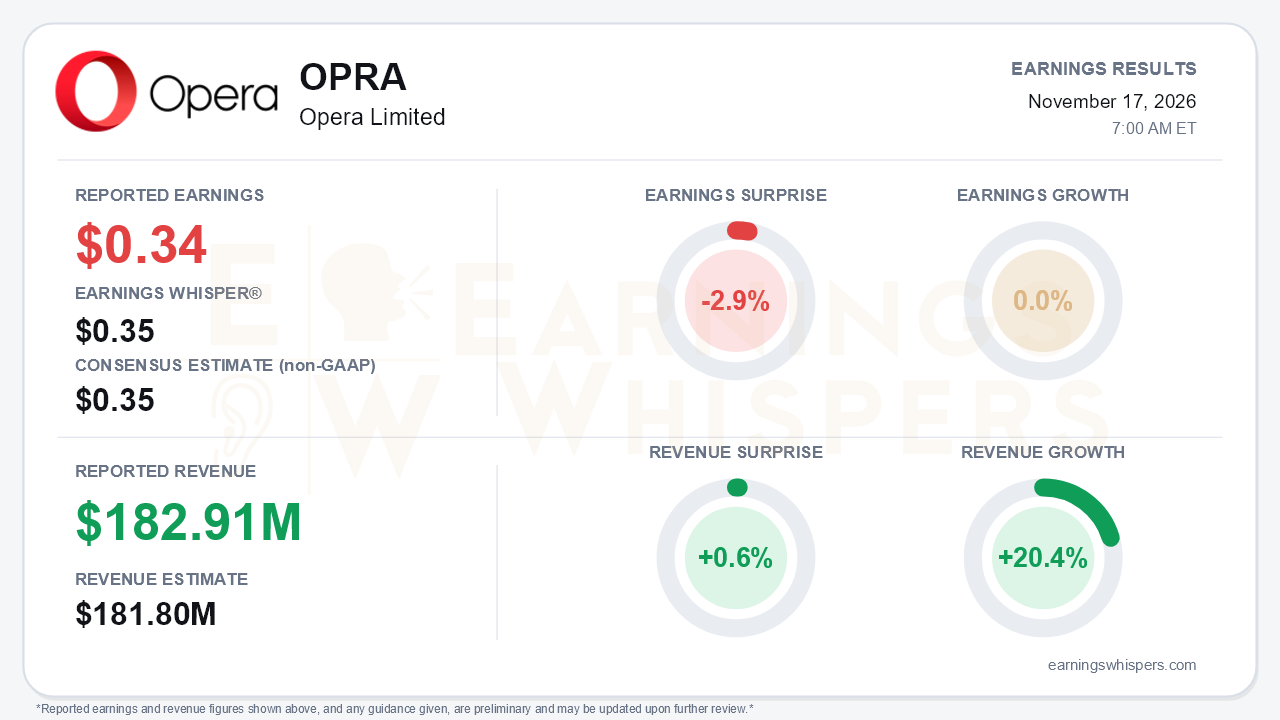
Opera Limited (NASDAQ: OPRA) reported third-quarter adjusted earnings of $0.34 per share, a penny short of both the $0.35 consensus and the $0.35 Earnings Whisper number, a 2.9% miss. Revenue of $182.9 million beat the $181.8 million consensus by 0.6% and grew 20.4% year over year. On Earnings Whispers' normalized basis, earnings were flat year over year. The company's own reconciliation shows adjusted diluted EPS of $0.34 against $0.30 a year ago, and GAAP diluted EPS rose to $0.30 from $0.21, so investors should note the difference in comparison bases. The miss is small. The bigger issue is that Opera's growth is slowing, and management's fourth-quarter guidance tells investors the slowdown has further to run.
The quality of the quarter is mixed. Revenue landed at the top of the $181–183 million guidance range, and adjusted EBITDA of $43.2 million edged past the $41–43 million guide. In earlier quarters, however, Opera cleared its guidance outright, so the beat is narrowing. Adjusted EBITDA margin was flat at 24%, and adjusted net income margin slipped to 17% from 18%. The 52% jump in GAAP operating profit was helped by several items:
- a $3.3 million reversal of a prior-quarter impairment;
- a 23% drop in share-based compensation as 2025 awards passed their first vesting period;
- flat personnel and marketing spending.
Cost of inventory sold rose about 45%, more than twice as fast as revenue, and hosting costs climbed to $5.0 million from $3.3 million. The cleanest strength was cash. Free cash flow reached $32.6 million, or 75% of adjusted EBITDA, up from about $17 million in the second quarter, and year-to-date conversion improved to 67%.
The call made the deceleration explicit. Revenue growth slowed to 20% from 25% in the second quarter. Advertising growth eased to 22% from 27%, and query growth fell to 17% from 21%. Management attributed the e-commerce slowdown to new EU cross-border rules and said that drag is fully reflected in third-quarter results. The fourth-quarter guide of $198–205 million implies only about 14% growth at the midpoint. Fourth-quarter cost of revenue is expected to rise to roughly 46% of revenue, pushing the quarter's adjusted EBITDA margin to about 22.6%. The CFO framed the step-down as lapping exceptional year-end quarters in 2024 and 2025, when e-commerce scaled into Opera's largest ad vertical. He also described the fourth-quarter spending as investment in new clients and inventory formats ahead of 2027. Both points are reasonable, but the guidance changes tell their own story:
- the full-year revenue range moved up by only $1 million at the low end, to $735–742 million;
- the adjusted EBITDA range was left unchanged at $172–175 million, after raises on each of the prior two calls;
- full-year marketing growth was guided down to low single digits.
Opera still has credible growth drivers to point to. Gaming advertising is growing more than 100% and is now a double-digit percentage of ad revenue, which management compared with where e-commerce stood three years ago. Connected-TV inventory is new and, by management's account, performing well. User metrics were strong:
- ARPU rose 22% to $2.60;
- PC browsers reached 100 million MAUs in October, up 16%;
- Opera GX added more than 4 million users;
- US iOS usage is growing more than 40%;
- MiniPay passed 20 million wallets and added a Stripe integration.
The risks are concrete. Opera is moving to a slower growth rate before gaming and CTV are large enough to replace e-commerce. In addition, management said OPay decided not to pursue its IPO for now, which delays any way to unlock value from a stake carried at $301 million.
Capital allocation is the other major development. Opera returned $73.3 million in the quarter. It bought back about 2 million shares for $37.7 million, compared with 636,000 shares in the second quarter, and paid its $0.40 semi-annual dividend. Cash fell to $109.5 million from $145.2 million as a result. The conversion from ADSs to Nasdaq-listed ordinary shares on December 7 eliminates depositary fees, and management expects it to remove a barrier to index inclusion.
The market had largely anticipated a slowdown. Shares closed at $15.40 before the report:
- down 15.8% from the $18.30 open after the August release;
- 10.2% below the 200-day moving average of $17.15;
- 23.1% below the August 27 inter-earnings high of $20.03;
- just 6.2% above the November 5 low of $14.50.
Investor sentiment, already slightly negative, became modestly more negative heading into the print. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP are negative.
The bottom line is that Opera delivered a cash-rich, well-executed quarter that still reads as a step down. The business keeps generating cash and returning it to shareholders, and gaming and CTV give it a plausible 2027 story. Even so, the slim EPS miss, a guidance raise of just $1 million, an unchanged EBITDA outlook and an implied mid-teens fourth quarter mean investors are now paying for a slower-growth Opera.
Read our earnings preview for Opera Limited: https://www.earningswhispers.com/article/OPRA/23105
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-17 | |
| Nov-17 | |
| Nov-17 | |
| Nov-17 | |
| Nov-10 | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-22 | |
| Aug-26 | |
| Aug-19 | |
| Aug-19 | |
| Aug-19 | |
| Aug-10 | |
| Aug-04 |
