Onfolio Repairs Its Balance Sheet, But Revenue Falls 51% And Gross Margin Keeps Sliding
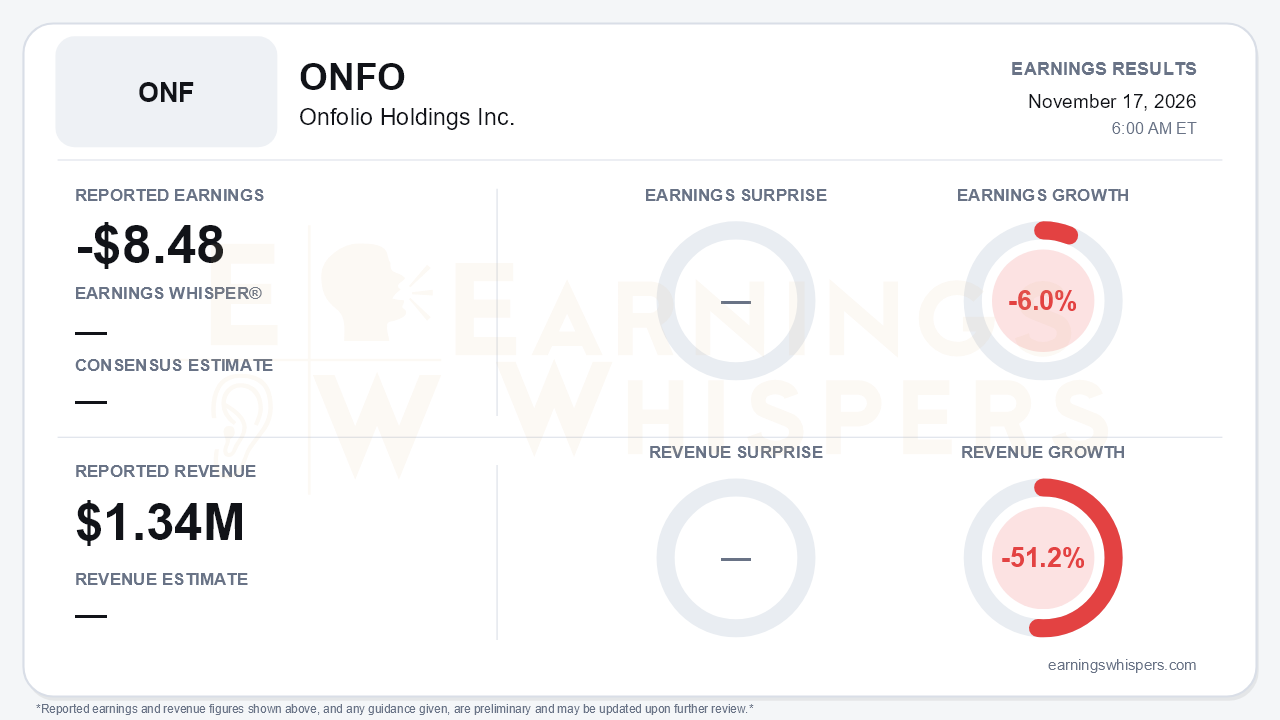
Onfolio Holdings reported a third-quarter loss of $8.48 per share on revenue of $1.34 million. Earnings fell 6.0% year over year and revenue fell 51.2%. There was no consensus estimate or Earnings Whisper to measure against, so the quarter has to be judged on its own terms. Those terms are split. Management used the quarter to clean up the capital structure: the Senior Secured Convertible Notes were fully converted and extinguished, and equity was rebuilt above Nasdaq's minimum. The operating business, however, kept shrinking, and margins deteriorated further. That is the central tension. The balance sheet is materially less dangerous than it was three months ago, but the earnings engine that has to service it is still losing ground.
The per-share comparison understates how much changed. Net loss swelled to $12.63 million from $0.63 million a year earlier. Weighted average shares jumped to roughly 1.49 million from about 102,500, and that dilution is what kept the per-share decline to 6.0%. Most of the loss was non-cash. Net interest expense of $13.78 million included about $8.2 million tied to the note conversion and $5.4 million from writing off the remaining debt discount. These were partly offset by $1.88 million of fair-value gains on derivatives and digital assets. Those same gains make reported EBITDA of $1.29 million misleading. The more useful measures point the other way:
- EBITDA As Defined was a loss of $0.57 million, versus a $0.04 million profit a year ago.
- Operating loss widened to $0.70 million from $0.27 million.
- Cash operating loss was about $0.54 million.
The cleanup itself is real. Total liabilities fell to about $3.4 million from roughly $9.6 million at the end of Q2. Equity attributable to Onfolio swung to about $2.9 million from a deficit of roughly $3.1 million.
The operating trends were weak almost everywhere outside the cost line. Revenue has now declined three straight quarters, from $1.87 million in Q1 to $1.5 million in Q2 and $1.34 million in Q3. B2C product revenue collapsed 79% year over year to $183,000. B2B revenue fell 34%, and that segment's operating loss widened to about $152,000 from about $103,000 in Q2 as Eastern Standard's decline persisted. Gross margin dropped to roughly 41% from about 49% in Q1 and Q2 and 65% a year ago. That leaves it far below the mid-60% target management set earlier this year and withdrew in Q2. Operating expenses fell 39% to $1.25 million, with SG&A down 47%. But cost cuts are chasing a shrinking gross profit line rather than creating operating leverage.
There are genuine bright spots inside the portfolio, and management leaned on them:
- RevenueZen's operating profit excluding amortization rose more than 200% year over year. Year-to-date results already exceed each of the past two full years, and AI-assistant tools like ChatGPT are cited as a source of inbound leads.
- DDS Rank has been profitable on that same basis in each of the first three quarters of 2026.
CEO Dominic Wells described "green shoots" and a "cautiously optimistic" fourth-quarter outlook, a notably warmer tone than Q2's admission that the company had not turned the corner. Still, these are small units. The CEO himself conceded that the cash balance is "still thin."
The forward-looking risk list is long, and bears have legitimate ammunition:
- The roughly $4 million EBITDA seller-financed acquisition missed its October 1 target close and has no new date. That makes the earlier goal of $5 million to $10 million of acquired EBITDA by year-end look out of reach.
- Two other deals sit at the LOI stage.
- The Series A preferred dividend was not paid, and accrued dividends have risen to about $246,000.
- The DDS Rank note maturity has been only informally extended to December 6.
- The Eastern Standard forbearance required a $450,000 upfront payment, funded by selling Ethereum, followed by $60,000 monthly through July 2027.
Cash of $459,000 rose from $251,000 in Q2, but only with help from crypto sales. Bitcoin holdings fell to 2.18 from 5.32 and Solana to about 1,007 from roughly 6,972. Current liabilities of $3.36 million still dwarf current assets of $0.94 million. Year-to-date operating cash burn was $1.9 million.
The market backdrop reflects that fragility. Shares opened at $1.50 after the August report, well below a 200-day moving average of $19.42, though that average likely reflects pre-split prices from the August 1-for-50 reverse split. The November 13 Nasdaq bid-price notice means another reverse split may be needed. Shareholders have already approved that authority, and the company has requested a hearing. Equity compliance is effectively resolved pending Nasdaq review, but the listing is not yet secure.
The bottom line is that Onfolio bought itself time rather than a turnaround. Extinguishing the convertible notes removed the most acute threat, at the cost of heavy dilution and a large non-cash loss. Revenue, gross margin, and acquisition execution all moved the wrong way. RevenueZen and DDS Rank offer a credible template, but until Eastern Standard stabilizes and a deal actually closes, the company is funding a shrinking business partly by selling down its digital assets.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-17 | |
| Nov-17 | |
| Nov-13 | |
| Nov-13 | |
| Nov-11 | |
| Oct-07 | |
| Aug-27 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-18 | |
| Aug-06 | |
| Aug-06 | |
| Jul-28 | |
| Jul-28 |
