LuxExperience Misses On EPS But Raises Margin Outlook As YNAP Turnaround Gains Traction
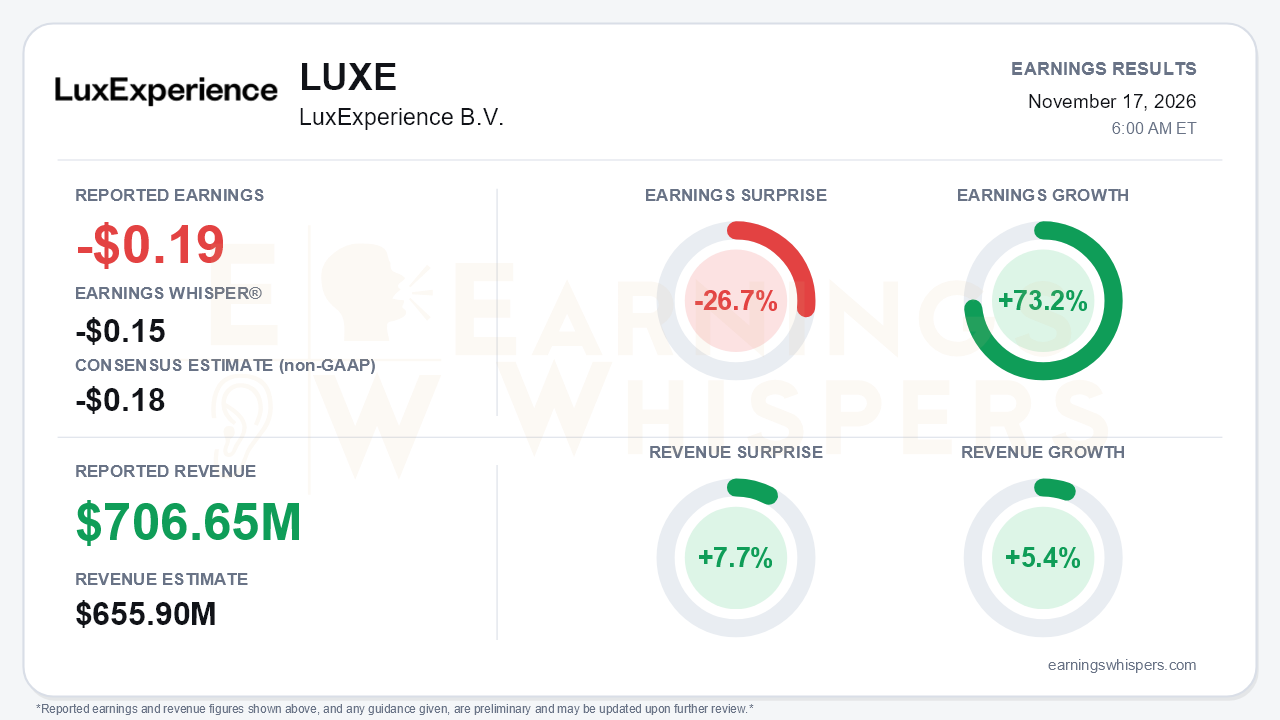
LuxExperience delivered a quarter where the headline EPS result and the operating story point in opposite directions. The company reported a loss of $0.19 per share for its fiscal first quarter ended September 2026. That missed the -$0.18 consensus and the -$0.15 Earnings Whisper number by 26.7%. Revenue told a different story. It came in at $706.65 million, 7.7% above the $655.9 million consensus and up 5.4% year over year. Earnings improved 73.2% from the prior-year period. Management also lifted its full-year profitability outlook after beating its own internal plan by a wide margin. That is the central tension: the per-share miss reflects items below the operating line, while the underlying business is improving faster than management expected three months ago.
The quality of the miss deserves scrutiny. On an IFRS basis, the net loss from continuing operations narrowed to €34.1 million from €87.7 million, and pre-tax loss shrank to €19.6 million from €85.1 million. Two items weighed on the bottom line:
- Income tax expense jumped to €14.4 million from €2.6 million.
- Transaction, legal and distribution-center closure costs still totaled €18.7 million, though that was down from €41.5 million.
Operationally, Adjusted EBITDA swung to a €12.7 million profit on a total-segments basis from a €21.5 million loss. Margin reached 2.1% against a prior-year -3.9%. Management had guided the quarter to a 'slightly negative' margin. Adjusted SG&A fell 11.1% in absolute euros, cutting the cost ratio to 17.6% from 21.8%. This was the fourth consecutive quarter of positive Adjusted EBITDA.
The call made the acceleration case explicit. Group constant-currency sales growth has improved from roughly flat in Q3 FY26 to +7.6% in Q4 and +8.5% this quarter, which management described as the best since the YNAP deal. All three segments accelerated:
- **NET-A-PORTER and MR PORTER:** Growth rose to +7.2% from +5.6% in Q4 and -5.1% in Q3, with U.S. sales up 24.3%. Its SG&A ratio dropped 560 basis points, and the segment held a positive, if thin, 0.3% EBITDA margin.
- **YOOX:** The off-price business grew 8.2% and cut its EBITDA margin loss to -4.6% from -16.1%, aided by a 24.2% reduction in SG&A. Breakeven is targeted for FY28.
- **Mytheresa:** Sales rose 10.0% while gross margin expanded 160 basis points to 46.2%. EBITDA margin doubled to 7.1%.
Bears still have legitimate ammunition. Mytheresa's U.S. growth decelerated sharply to +9% from +39.3% in Q4; management attributed the slowdown to tough comparisons. Roughly 110 basis points of Mytheresa's margin came from non-recurring IEEPA tariff refunds, and similar refunds flattered NAP/MRP in Q4. Customer counts are also shrinking across the board. Active customers fell 3.8% at Mytheresa, 6.0% at NAP/MRP and 4.4% at YOOX, and NAP/MRP orders declined 7.6%. That means growth is leaning heavily on order value and top-customer spending rather than breadth, and bags remain the slowest category. Cash is another pressure point. Operating cash flow was -€104 million, and cash and equivalents fell to €199.7 million from €317.7 million. The call's figure of €324.7 million, down from €442 million, appears to include €125 million of treasury investments held as non-current financial assets.
On guidance, the FY27 Adjusted EBITDA margin target rose to 2.5%–3.5% from 2%–3%. The sales outlook was characterized as 'narrowed' to +6% to +9%, from mid-to-high single digits. Management framed that as an upgrade, and the call indicated the new range tilts toward the upper end of the old one. Q2 is guided to high-single-digit growth with a mid-single-digit margin. Two items held steady:
- **Medium-term targets:** 10–15% growth and a 7–9% margin at €4 billion in sales were reaffirmed, not raised.
- **Replatforming:** The new NAP/MRP e-commerce platform has been pulled forward to summer 2027, a potential efficiency catalyst.
The market had already priced in much of the recovery. Shares closed at $10.75 ahead of the report, up 28.1% from the $8.39 open after the September release. That left the stock 26.5% above its $8.50 200-day moving average and just 1.8% below its inter-earnings high of $10.95, set November 11. The rally began from a quarter low of $7.88 on September 16. Investor sentiment remained slightly negative and was essentially unchanged, moving from -0.14 to -0.12. Momentum and AVWAP trend readings are positive. The stock therefore entered the print near the top of its range, while investors remained mildly skeptical rather than euphoric.
The bottom line is that LuxExperience's EPS miss is a below-the-line story, driven largely by taxes and lingering restructuring costs, set against a quarter of genuine operating progress. Sales accelerated, profitability beat internal plans and the margin outlook moved higher. Turnaround skeptics can point to Mytheresa's U.S. slowdown, one-time tariff benefits, a shrinking customer base and heavy cash burn. With the stock already near its quarterly high, further gains likely depend on whether the margin improvements prove durable without tariff refunds and whether higher order values can offset declining customer counts.
Read our earnings preview for LuxExperience B.V.: https://www.earningswhispers.com/article/LUXE/23102
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-17 | |
| Nov-17 | |
| Nov-12 | |
| Nov-10 | |
| Oct-27 | |
| Sep-16 | |
| Sep-16 | |
| Sep-16 | |
| Aug-26 | |
| May-19 | |
| May-19 | |
| Apr-30 | |
| Apr-28 | |
| Feb-13 | |
| Feb-10 |
