AECOM Beats On Record Margins And Guides FY27 Above Estimates, But Muted NSR Growth And Construction Management Cash Burn Temper The Recovery
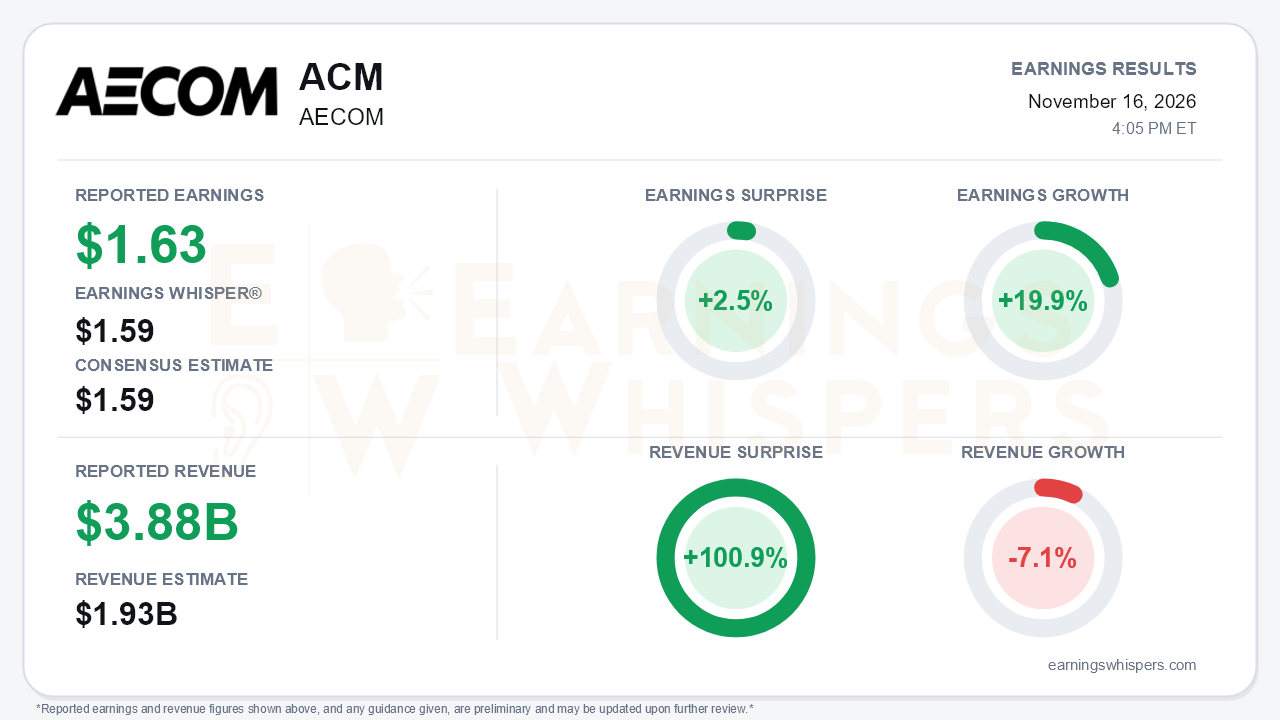
AECOM delivered the quarter it needed after last quarter's Construction Management reset. Adjusted EPS of $1.63 topped both the $1.59 consensus and the $1.59 Earnings Whisper number by 2.5% and grew 19.9% year over year. Management also initiated fiscal 2027 guidance for adjusted EPS of $6.15 to $6.35, which Earnings Whispers characterizes as above estimates. That compares with roughly $6.00 of underlying FY26 earnings power cited on the prior call. The central tension is that AECOM's earnings story is now being driven by margins rather than growth. Profitability hit records while net service revenue (NSR) growth and free cash flow guidance remain subdued.
The headline numbers need some translation. Reported revenue of $3.878 billion fell 7.1%, driven by declines in the pass-through-heavy Construction Management business. The supplied revenue consensus of $1.93 billion appears to track NSR rather than gross revenue, so the 100.9% revenue surprise reflects a mismatch in measurement basis, not a blowout. On the measure that matters, NSR was $1.92 billion and grew 3% after adjusting for fewer working days, roughly in line. The earnings beat also has a meaningful GAAP gap. GAAP diluted EPS from continuing operations was flat at $0.99, weighed down by $85 million of restructuring and acquisition costs and intangible amortization tied to the Advisory build-out. Still, the operating improvement is real:
- Segment adjusted operating margin rose 110 basis points to a record 18.2%.
- Adjusted EBITDA margin climbed 170 basis points to 19.2%.
- Adjusted EBITDA grew 9%.
The call showed how uneven the recovery is beneath the surface. International has become the clear improvement story:
- NSR growth moved from a 3% constant-currency decline in Q2 to +4% in Q3 and +5% in Q4, helped by a return to growth in the Middle East.
- Adjusted operating margin rose from 11% in Q2 to 14.3% in Q3 and a record 14.8% in Q4.
The Americas design business tells a softer story. Its 6% growth was below the 7%-plus management guided on the Q3 call and well under the 8% to 9% pace earlier in the year, even though enterprise design growth accelerated to 6%. Management's tone shifted from defensive to confident. Executives pointed to record win rates, a 1.3x full-year book-to-burn, and a 13% rise in backlog to $28.0 billion. Q4 book-to-burn was a more modest 1.1x. Management also cited AI as a driver of new types of work beyond traditional engineering and said the Advisory team is on track to double.
The forward catalysts are substantive:
- Selection for two of the largest state DOT transportation programs
- A major metro rail win in Ireland and a large rail award in Saudi Arabia
- Supportive U.S. state and local ballot measures and Canadian infrastructure budget commitments
- A 10% dividend increase to $0.34 per quarter
Bears still have legitimate ammunition. FY27 NSR guidance of 4% to 6% sits below the company's 5% to 8% long-term algorithm, and the first quarter is expected at or below the low end. Management flagged longer award-to-start conversion across the business, especially in the Middle East.
Cash is the bigger constraint. FY26 free cash flow of $344 million beat the $300 million guide, and Q4 free cash flow doubled to $274 million. However, FY27 free cash flow is guided to only about $300 million because roughly $500 million will go to the two troubled Construction Management projects, implying negative first-half free cash flow. Management framed normalized free cash flow at about $800 million. The projects themselves appear to be on track:
- Phase one of the first project has been delivered.
- The second project is expected near the end of fiscal Q2.
The remaining exposure is long-dated. Roughly a quarter of the first project's scope extends into FY29, claims resolution will be lengthy, and net debt has already risen to $1.5 billion from $1.16 billion a year ago.
Investor sentiment improved modestly, from -0.29 to -0.22, but remains negative. That fits a market willing to credit the stabilization without fully trusting it. Shares have gained 6.2% since the open following the August report, rising from $68.25 to $72.50. They still sit about 2.9% below the 200-day moving average of $74.68. The stock has recovered some ground from the charge-driven reset but has not reclaimed its longer-term trend. Price-based trend readings are mixed, with price momentum neutral while AVWAP has turned positive.
The bottom line is that AECOM used Q4 to rebuild credibility. It posted record margins, beat its cash target, showed visible progress on the Construction Management problem, and issued an earnings guide that implies growth off the reset base. What the quarter did not deliver is top-line acceleration, and first-half FY27 will be burdened by slow NSR growth and heavy project cash use. The investment case now rests on margin expansion toward the reiterated 20%-plus FY28 exit target and on backlog converting faster than recent award-to-start trends suggest.
Read our earnings preview for AECOM: https://www.earningswhispers.com/article/ACM/23064
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 44 min | |
| 2 hours | |
| Nov-16 | |
| Nov-16 | |
| Nov-13 | |
| Nov-13 | |
| Nov-09 | |
| Oct-26 | |
| Oct-12 | |
| Oct-06 | |
| Sep-22 | |
| Sep-17 | |
| Sep-16 | |
| Sep-10 | |
| Sep-10 |
