Griffon Beats A Low Bar, But A Flat FY27 Outlook And Negative Volume Shift The Story To Balance Sheet And Buybacks
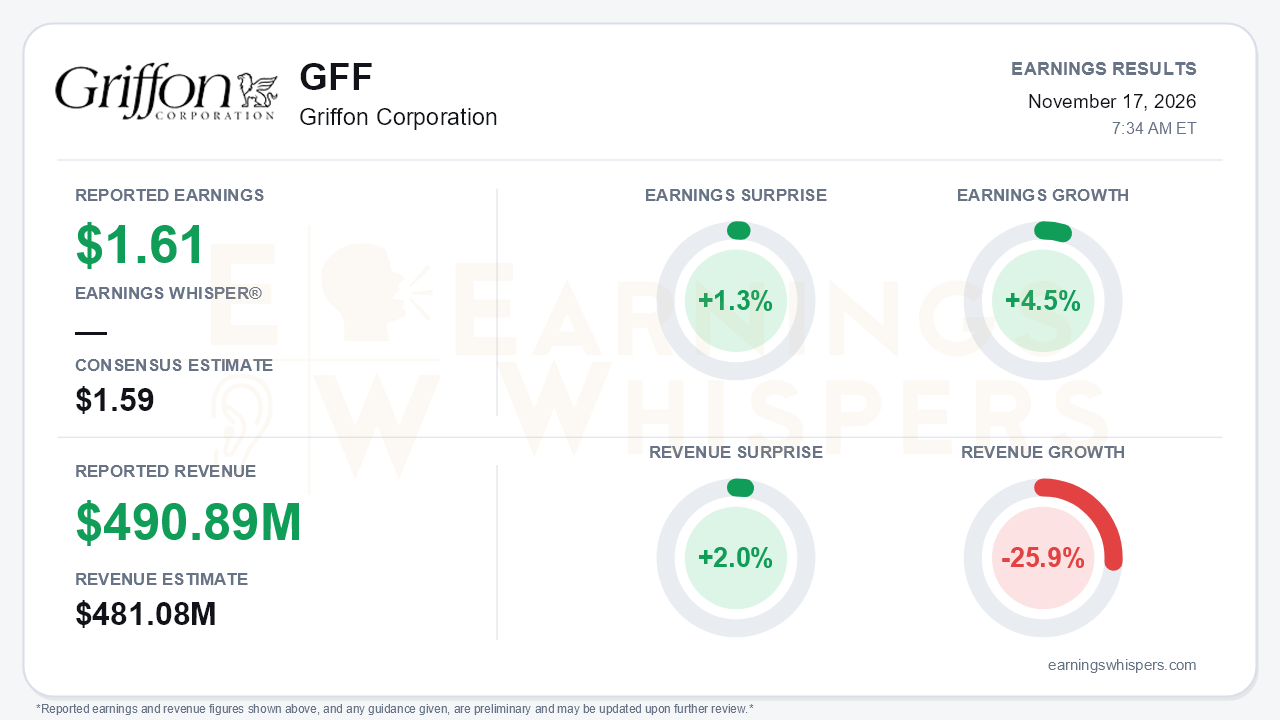
Griffon Corporation closed its transformational fiscal 2026 with a modest fourth-quarter beat. Adjusted EPS was $1.61, against the $1.59 consensus, a 1.3% surprise. Revenue of $490.9 million topped the $481.1 million estimate by 2.0%. Earnings Whispers calculates earnings growth of 4.5% and a 25.9% year-over-year revenue decline. Those figures compare against a prior-year base that appears to still include businesses Griffon has since divested. On the release's continuing-operations basis, revenue rose 3% from $475.6 million and adjusted EPS rose from $1.42. The beat itself is not the central development. Griffon is now a smaller, cleaner, less-levered building products company, and it guided fiscal 2027 to essentially no growth. Earnings Whispers characterizes that guidance as below estimates. That is the central tension: a much better balance sheet paired with an operating outlook that has stalled.
The quality of the quarter deserves scrutiny. All of the top-line growth came from 6% favorable price and mix, which offset a 3% volume decline across both residential and commercial. Volume was up 1% in the third quarter, so this is a reversal rather than a continuation. Pricing did more than hold the line on margin. Gross margin expanded 70 basis points to 46.9%, and adjusted EBITDA rose 4% to $127.8 million, a roughly 26% margin. However, lower volume hurt overhead absorption, and material, labor and distribution costs kept rising. Adjusted SG&A climbed to 22.9% of revenue from 22.4%. GAAP continuing EPS of $1.49 versus $0.43 flatters the comparison, because the prior-year quarter carried a $46 million discrete tax charge. For the full year, adjusted EBITDA of $459.6 million was flat against $461.8 million and only edged past the $458 million guide.
The call laid out a business that is executing well on price, mix and share but has no demand tailwind. Management cited share gains in residential and commercial doors. The fiscal 2027 outlook calls for revenue of $1.85 billion and adjusted EBITDA of $460 million, both flat. That outlook assumes:
- lower residential volume;
- flat commercial volume, with commercial new construction still soft and the architecture billings index below 50;
- a first half slightly behind the prior year.
Flat EBITDA on flat revenue implies no margin expansion. Cost inflation, including steel, is being offset only by pricing. CEO Ronald Kramer said growth should accelerate "as building activity improves," but the guidance does not assume that improvement.
The more constructive story sits below the operating line:
- **Debt and credit:** Debt fell by $364 million in fiscal 2026, and leverage dropped to 2.0x from 2.4x a year earlier. Bonds were refinanced out to 2034, and Moody's and S&P each raised Griffon one notch.
- **Interest expense:** Fiscal 2027 interest expense is guided to about $50 million, versus roughly $80 million in fiscal 2026. That figure includes interest income on the roughly $216 million related-party notes received in the divestiture.
- **Capital returns:** The buyback authorization rose by $400 million to $544.8 million available, and the dividend increased 14% to $0.25. Management set a new target of more than $1 billion of free cash flow over four years.
Taken together, lower interest costs and a shrinking share count give Griffon a credible path to per-share earnings growth even if EBITDA does not move. Investors should recognize that the earnings growth would be financially engineered rather than organic. Debt reduction also leaned heavily on $304 million of sale proceeds. Underlying free cash flow of $267 million was essentially unchanged from $266 million a year earlier.
Investor sentiment remained positive but softened slightly ahead of the report, slipping to 0.13 from 0.17. That is a modest cooling rather than a reversal. Shares closed at $99.96 on the eve of the release, up 3.0% from the open after the August report and about 10.5% above the 200-day moving average. The quarter included a wide swing: a low of $89.05 on October 12 and a 52-week high of $109.00 on November 5. The stock entered earnings about 8% below that peak, so some of the pre-report enthusiasm had already been given back. The Earnings Whispers price and AVWAP trend readings remain positive, while sequential growth and momentum are neutral. That mix fits a stock supported by capital-return momentum rather than accelerating fundamentals.
The bottom line is that Griffon delivered a clean but narrow beat built on pricing rather than volume, and its fiscal 2027 guide offers no operating growth. The bull case now rests on the balance sheet: sharply lower interest expense, an upgraded credit profile, a larger buyback and a bigger dividend can drive per-share gains on a flat EBITDA base. Bears have legitimate ammunition in the renewed volume decline, weak commercial construction and cost inflation that pricing must keep absorbing. With the stock already well above its 200-day average and sentiment cooling, upside likely depends on whether housing and commercial activity improve beyond what management has assumed.
Read our earnings preview for Griffon Corporation: https://www.earningswhispers.com/article/GFF/23153
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-17 | |
| Nov-17 | |
| Nov-17 | |
| Nov-17 | |
| Nov-17 | |
| Nov-11 | |
| Nov-10 | |
| Oct-05 | |
| Aug-18 | |
| Aug-10 | |
| Aug-10 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-03 |
