Eltek Narrows Losses For A Third Straight Quarter, But A CEO Change And Slipping Timelines Push The Recovery Into Late 2027
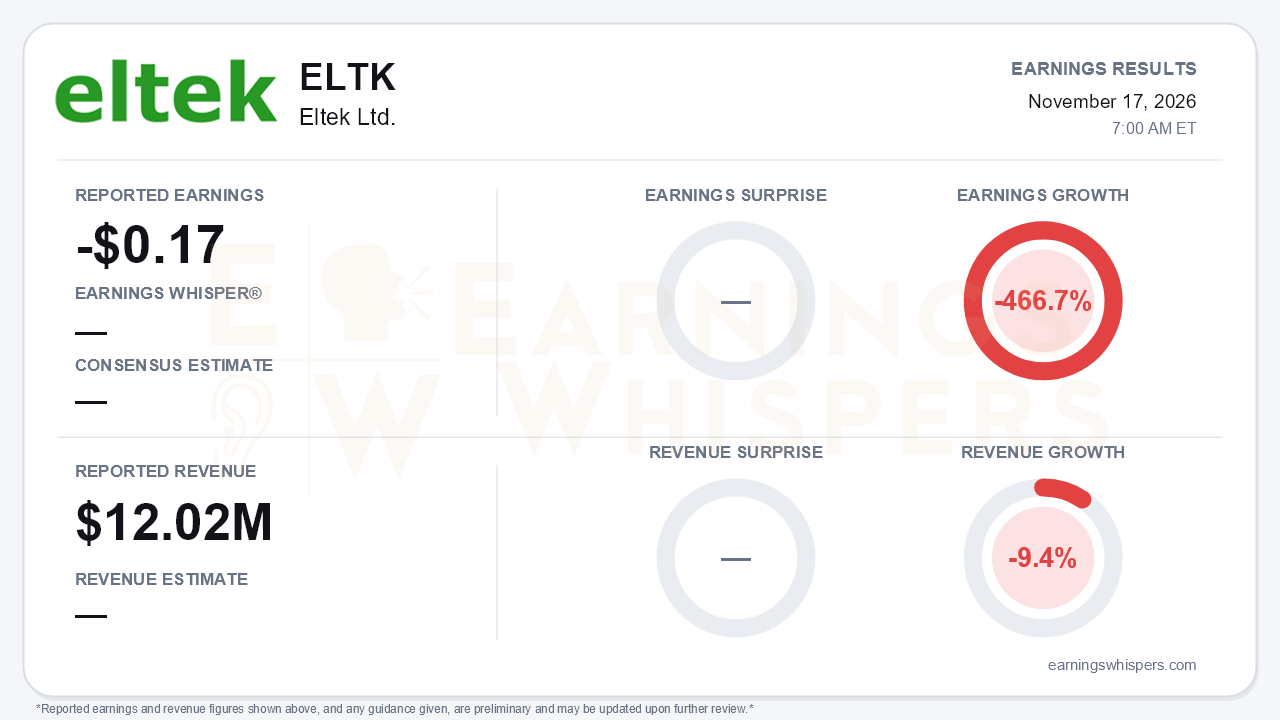
Eltek's third-quarter report has two sides. On a year-over-year basis the numbers are poor. The Israeli PCB maker lost $0.17 per share on revenue of $12.02 million. Earnings fell 466.7% from the $0.03 loss a year ago, and revenue declined 9.4%. Measured against the first half of 2026, though, the quarter was the best of the year. Losses narrowed for a third consecutive quarter, and gross profit turned slightly positive. The central tension is that the operating repair is clearly underway while the timeline for a full recovery has moved further out. Management now frames a return to profitability as 'toward the end of 2027.'
The sequential progress is real but modest:
- Gross profit was $0.23 million, a 2% margin. That compares with gross losses of $1.0 million in Q2 and $1.9 million in Q1.
- The operating loss shrank to $1.6 million from $2.5 million in Q2 and $3.3 million in Q1.
- The EBITDA loss improved to $1.0 million from $1.9 million.
- Revenue has climbed from $10.4 million in Q1 to $11.5 million in Q2 to roughly $12.0 million now.
The quality of the improvement still deserves scrutiny. A year ago, Eltek earned a 12% gross margin on $13.3 million of revenue. This quarter it barely covered cost of goods on slightly lower sales. Selling, general and administrative expenses also rose to $1.85 million from $1.55 million.
Below the operating line, the quarter got some help. Financial income of $0.3 million, driven by shekel weakness against the dollar, replaced a $0.3 million expense a year earlier. A $0.17 million tax benefit narrowed the reported loss further. Cash generation was thin: operating cash flow was just $44,000, against $2.0 million in the year-ago quarter.
The call shifted in tone. In Q1 and Q2, management spoke confidently about a record backlog. This quarter it talked about operational repair. Management explicitly acknowledged unstable production and missed delivery schedules, and called them a threat to customer confidence. The new framework includes:
- expanded process-engineering coverage;
- preventive maintenance;
- KPI tracking;
- capacity checks at order acceptance.
That framework is sensible, but it is an admission that the factory has struggled to convert demand into on-time output. The press release says sustained demand has lifted the order backlog for the rest of 2026 and into 2027. However, the release gives no figure, and the call did not quantify backlog at all. Investors are being asked to accept the demand claim on faith while capacity, not orders, remains the binding constraint.
The most important catalyst is the new 39-meter plating line. Installation is complete, and management says early trials show significant gains in quality and efficiency. The timing, however, keeps slipping. On the Q1 call, the line was targeted to be running by July 1. On the Q2 call, customer qualification was expected to start in the third quarter. Qualification is now slated for early 2027.
Several prior commitments were left unaddressed:
- the $60-65 million revenue capacity target;
- the 26-28% gross margin target;
- timing for the second plating line, previously expected to arrive at the end of 2026;
- the medical and industrial diversification effort.
Those omissions are not formal guidance cuts. Still, after a CEO change, bears have legitimate ammunition to treat them as soft retreats. Eli Yaffe has departed, and Ron Freund has moved from CFO to CEO.
The risk list extends beyond execution. Raw-material supply is described as 'increasingly challenging,' with allocation tilting toward AI customers. Price inflation did moderate from Q2. On the positive side, foreign-worker headcount rose to about 23 from about 15, which helps address labor constraints.
The balance sheet buys time but is not static. Cash and short-term deposits fell to $10.4 million from $11.5 million in Q2 and $12.1 million at the end of 2025. Capital spending and currency translation offset the small operating inflow. Eltek carries no debt, and management says no capital raise is planned. Even so, nine-month results show a $6.8 million net loss, against a $1.1 million profit a year earlier. At that pace, the cushion can only absorb a limited number of additional delays.
Market context is limited. The stock opened at $8.55 after the August report, but no current price, sentiment reading, or technical data were supplied. The investment case therefore rests almost entirely on whether the operational story holds up.
The bottom line is that Eltek delivered the sequential improvement turnaround believers needed, with positive gross profit and steadily shrinking losses. However, the quarter also reset expectations in ways skeptics will emphasize. The company has a new CEO, plating-line qualification has slipped into 2027, and profitability is now pushed to late 2027. The prior revenue and margin targets were also left off the table. Until the plating line clears customer qualification and delivery reliability visibly improves, the recovery remains a credible story with an increasingly long runway.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 8 hours | |
| Nov-09 | |
| Oct-06 | |
| Sep-09 | |
| Aug-22 | |
| Aug-18 | |
| Aug-11 | |
| May-26 | |
| May-19 | |
| May-19 | |
| May-07 | |
| Apr-01 | |
| Mar-26 | |
| Mar-11 |
