Nauticus Robotics Posts A Sequential Rebound And A Bolder Defense Pitch, But Backlog, Cash And Dilution Still Define The Story
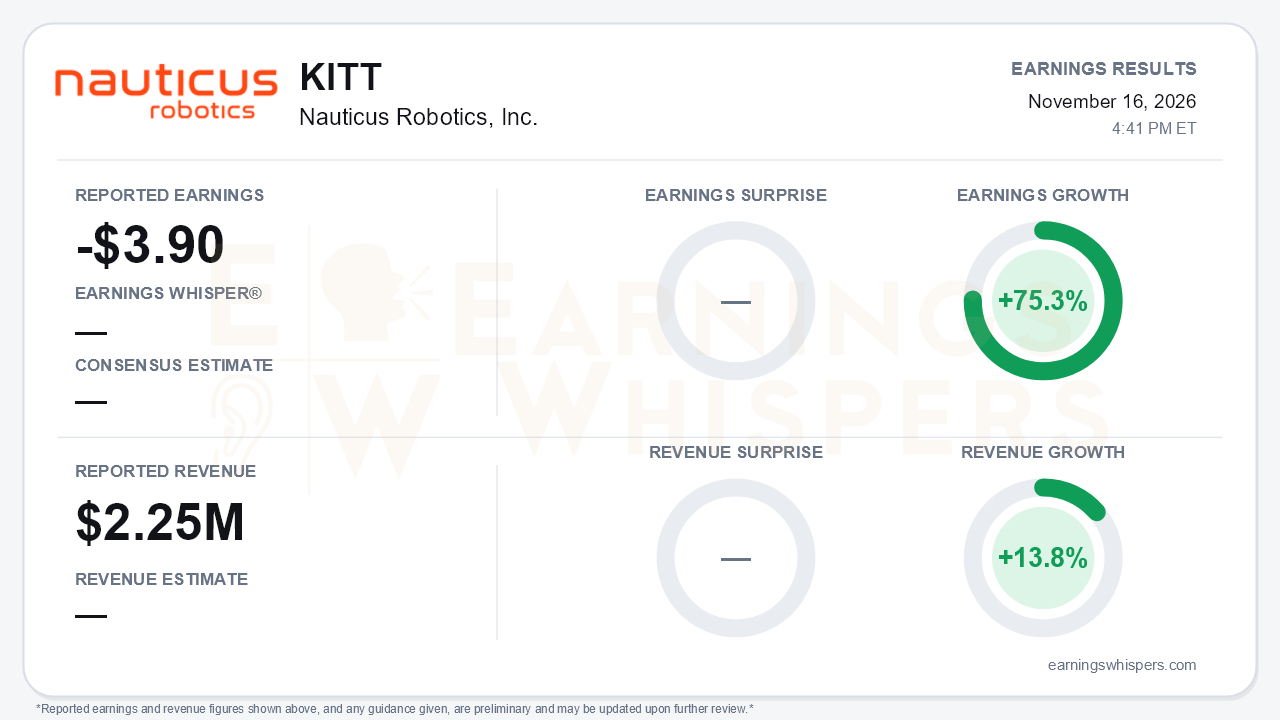
Nauticus Robotics (NASDAQ: KITT) delivered its best operating quarter of 2026. It reported a loss of $3.90 per share on revenue of $2.25 million for the quarter ended September. Earnings improved 75.3% year over year and revenue grew 13.8%. No consensus estimate or Earnings Whisper was available, so the quarter has to be judged on its own trajectory.
That trajectory is better than it has been all year. Revenue more than doubled from $0.9 million in the second quarter and $0.2 million in the first. The central tension is that this improvement comes from a very small base. It rests on short-duration call-out work rather than contracted backlog, and it is funded by a balance sheet that remains thin.
The quality of the improvement deserves scrutiny, though the cost discipline is real.
- **Expenses:** Total costs fell to $6.5 million from $6.9 million in Q2 and $7.9 million a year ago. G&A dropped to $2.7 million from $3.3 million sequentially.
- **Operating loss:** It narrowed to $4.3 million from $6.0 million.
- **Adjusted net loss:** It improved to $5.3 million from roughly $7.0 million in Q2.
- **GAAP net loss:** It fell to $4.9 million from $11.1 million. The Q2 figure was inflated by a $4.6 million loss on debt extinguishment.
The gains stop short of a business that covers its direct costs. Cost of revenue was $3.0 million against $2.25 million of revenue, so services still ran at a negative contribution before depreciation and overhead. That gap was much wider a year ago, when costs were $4.3 million against $2.0 million of revenue. Year to date, revenue is still down, at $3.3 million versus $4.2 million in 2025.
Investors should also note the per-share accounting. The Earnings Whispers figure differs sharply from the GAAP basic loss of $10.87 per share. The GAAP number reflects $9.7 million of deemed dividends on convertible preferred stock, which pushed net loss attributable to common stockholders to $14.9 million.
The call carried a noticeably more confident tone, especially on defense. A newly dedicated defense lead said discussions with the U.S. Navy, allied navies and prime contractors have moved past introductions to specific operational requirements, technical evaluations and acquisition pathways. Mine countermeasures is the lead application. Management also said customers are increasingly seeking Nauticus out.
On the commercial side, the company supported three offshore wind and subsea cable projects in the quarter, including one for a new client, and completed a cable job offshore California. A West Coast project could start around December or January. Discussions on an extended-duration international project could run into 2027. The CEO called 2027 "probably a really good year" for Gulf of America work. In the UAE, a Ras Al Khaimah facility has been selected and regulatory approvals are being finalized, with quote requests arriving after ADIPEC.
Bears have legitimate ammunition, because much of what was promised earlier remains unfulfilled.
- **Backlog:** Management had pledged in Q2 to report bookings and backlog, but again disclosed neither. The CEO acknowledged the business is "still in the tactical market."
- **Software:** Management had said in Q4 2025 that software revenue would come "for certain this year," and ToolKITT had a formal launch in Q2. No license revenue has been announced, and the timing now appears to have slipped toward 2027.
- **Defense revenue:** The multi-phase defense evaluation flagged last quarter received no update, and defense remains pre-revenue.
- **UAE timing:** The Middle East conflict continues to slow the facility setup.
- **Other risks:** Management also flagged Nasdaq listing-rule risk and potential BOEM-related delays to Gulf inspection work.
The balance sheet is the binding constraint. Cash and restricted cash of $5.6 million recovered from about $2.0 million at the end of June, but only with help from the at-the-market (ATM) equity program. The total is still below the $7.6 million held at year-end 2025. Nine-month operating cash burn was $17.1 million, which leaves current cash covering roughly a quarter of burn at that pace.
Debt maturities were extended, and about $6.2 million of the related-party term loan moved to long-term. Even so, current liabilities still total $27.8 million against stockholders' equity of just $5.6 million. Management declined to project cash breakeven. The company also executed two reverse splits this year, 1-for-8 in April and 1-for-6 in September. Weighted shares outstanding rose from about 81,000 a year ago to 1.37 million, both split-adjusted, which shows how heavily the model leans on dilution.
Market context is limited. No current price or sentiment reading was available. The September reverse split also complicates comparisons with the $1.13 opening price after the August report. The stock's 200-day moving average stands at $5.69, though how much of that average reflects post-split trading is unclear. The practical read is that this setup depends on financing and contract conversion rather than on any quarterly beat.
The bottom line is that Nauticus showed genuine sequential progress: revenue more than doubled, costs fell and losses narrowed, while the defense narrative gained specificity. But the quarter offered no backlog, no software revenue and no funded defense program to anchor that optimism, and the cash runway remains short and dependent on equity issuance. Until engagement turns into disclosed contracts, the improving tone is a promise rather than a proven inflection.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-17 | |
| Nov-16 | |
| Nov-11 | |
| Sep-25 | |
| Sep-23 | |
| Sep-17 | |
| Sep-09 | |
| Sep-03 | |
| Sep-01 | |
| Aug-19 | |
| Aug-12 | |
| Aug-06 | |
| Aug-04 | |
| Jul-28 | |
| Jul-16 |
