Energizer's Margin-Driven Beat And $300 Million Cash Target Collide With A Top Line That Keeps Shrinking
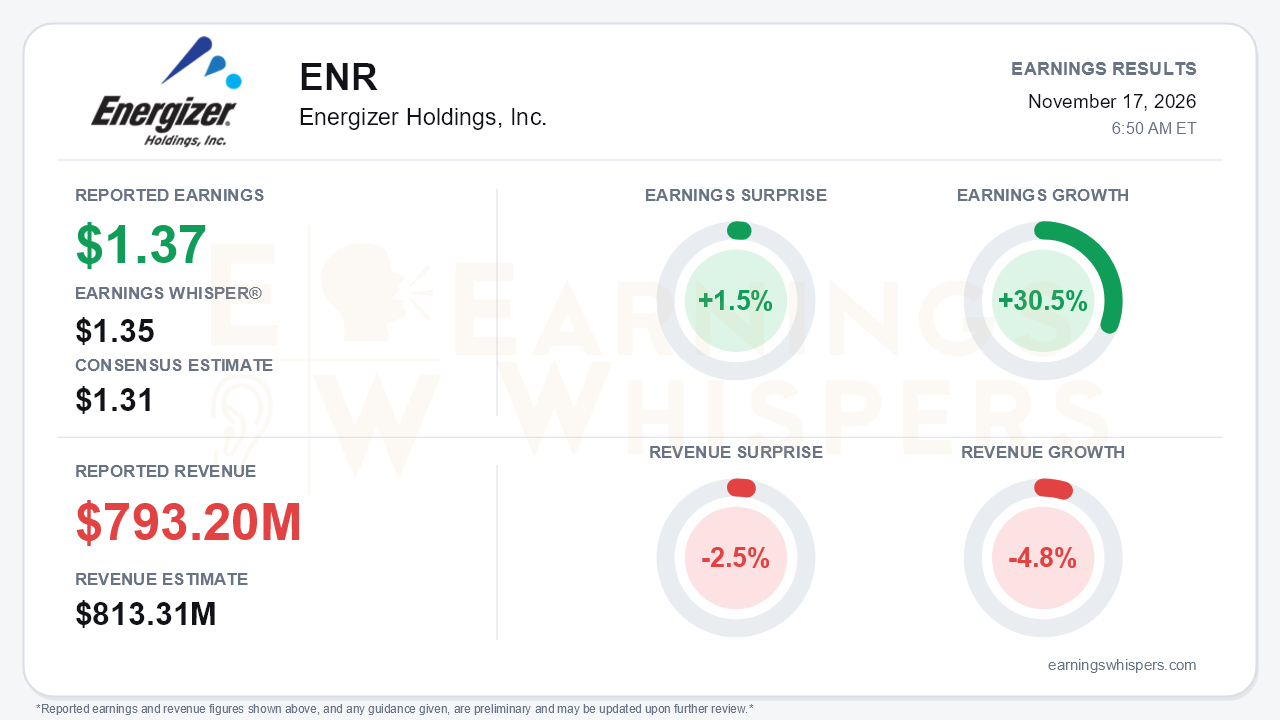
Energizer Holdings (NYSE: ENR) closed fiscal 2026 with a quarter built on margin and cash rather than sales. Adjusted EPS of $1.37 topped the $1.31 consensus by 1.5% and edged past the $1.35 Earnings Whisper number. Earnings grew 30.5% year over year, a sharp reversal from a full year in which adjusted EPS fell to $3.37 from $3.52. Revenue told a different story. Sales of $793.2 million missed the $813.31 million consensus by 2.5% and fell 4.8%. That is the central tension: Energizer is getting more profitable and far more cash-generative while its sales base keeps eroding. The fiscal 2027 outlook does little to resolve it.
The quality of the beat deserves scrutiny. Adjusted gross margin jumped 400 basis points to 42.5%, and the sources of that gain matter:
- 140 basis points came from favorable mix.
- 110 basis points came from higher Section 45X production tax credits.
- 70 basis points came from a lower net tariff impact, including refund benefits.
- Only 40 basis points came from pricing.
On the expense side, Project Momentum trimmed roughly $10 million from SG&A. GAAP EPS nearly doubled to $0.99 from $0.50, helped by the absence of last year's impairment and debt-extinguishment charges, though $26.4 million of restructuring costs remain. Adjusted EBITDA rose 13% to $193.1 million. Some of that leverage is genuine cost-out. Some reflects government-related tailwinds that management itself backs out when framing next year.
The sales picture is weaker than the earnings suggest. Organic sales slipped only 0.6%, but that masks a sharp divergence between segments:
- **Batteries & Lights** grew about 1.4% organically on distribution gains and e-commerce.
- **Auto Care** fell 9.2% organically, which the company attributed to refrigerant shipments pulled into the third quarter.
The reported decline was steeper because of a 4.6% hit from the expired APS brand license. Organic momentum also cooled from the third quarter's 2.7% gain, leaving second-half organic growth near 1%.
The call made the trajectory clearer. Revenue expectations have been cut call over call:
- On the second-quarter call, management expected roughly 4% second-half organic growth.
- On the third-quarter call, that became flat to up 1%.
- Now fiscal 2027 is guided flat to down low single digits.
That amounts to roughly a fifth year of about 1% organic declines. Auto Care moved from expected growth to an outlook of down low single digits, partly by choice: the company is exiting about $25 million of lower-margin business, including private-label refrigerant, to lean into premium products such as Armor All Podium Series. Management also flagged three headwinds:
- 200 to 300 basis points of cost pressure from zinc, steel, energy and freight.
- An elevated U.S. promotional environment.
- Rising private-label interest.
Excluding tariff recovery, normalized gross margin sits near 38%. The fiscal 2027 plan therefore depends on pricing just to hold margins flat, not expand them.
What changed most is the cash narrative, and the call preserved a credible version of it. Free cash flow more than tripled in fiscal 2026 to $228.6 million, and debt fell $167.7 million. Fiscal 2027 targets are:
- **Free cash flow:** roughly $300 million, up more than 30%.
- **Debt reduction:** another $150 million to $200 million.
The drivers are Momentum cash costs rolling off, capital spending normalizing near 2% of sales, and about $45 million of production-credit refunds that slipped from fiscal 2026 into fiscal 2027.
The EBITDA guide needs careful reading. The $560 million to $580 million range represents 5% to 9% growth only after excluding the $64 million IEEPA tariff refund. On a reported basis it sits below fiscal 2026's $597.3 million. First-quarter EBITDA guidance implies just 3% growth at the midpoint, and reported sales must absorb about $60 million of non-recurring APS sales. With net debt still at 5.1 times adjusted EBITDA, deleveraging is a necessity rather than a luxury. Bears have legitimate ammunition. One modest offset: recent four-week battery category trends are running ahead of the planning assumption.
The market had already priced in a good deal of the improvement. Shares rose 21.7% from the $20.00 open after the August report to $24.34 on the eve of this release. That leaves the stock about 18% above its 200-day moving average and within 6% of the $25.83 52-week high set on November 4. The stock entered the report near the top of an inter-earnings range that began at a $19.03 low. Investor sentiment improved modestly, from -0.27 to -0.21, but remains negative. The market has rewarded the margin and cash story while expectations stay guarded. Price and AVWAP trend readings are positive, while momentum has turned negative, consistent with a stock that has run ahead of an unexciting guide.
The bottom line is that Energizer delivered a cleaner, more profitable quarter and a believable path to roughly $300 million of free cash flow, but it has not shown it can grow. A modest earnings beat paired with a revenue miss, flat-to-down organic guidance, and EBITDA growth that exists only after excluding tariff refunds makes this a deleveraging story rather than a growth story. After a 20%-plus run into the print, investors now need evidence that pricing and Momentum savings can protect margins while the top line keeps shrinking.
Read our earnings preview for Energizer Holdings, Inc.: https://www.earningswhispers.com/article/ENR/23095
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 6 hours | |
| 8 hours | |
| 8 hours | |
| 9 hours | |
| 9 hours | |
| Nov-10 | |
| Nov-09 | |
| Oct-28 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-28 | |
| Jul-23 |
