Midera's First Standalone Quarter Beats And Lifts Guidance On Margin Gains, But Flat Orders And A Stalled Backlog Temper The Story
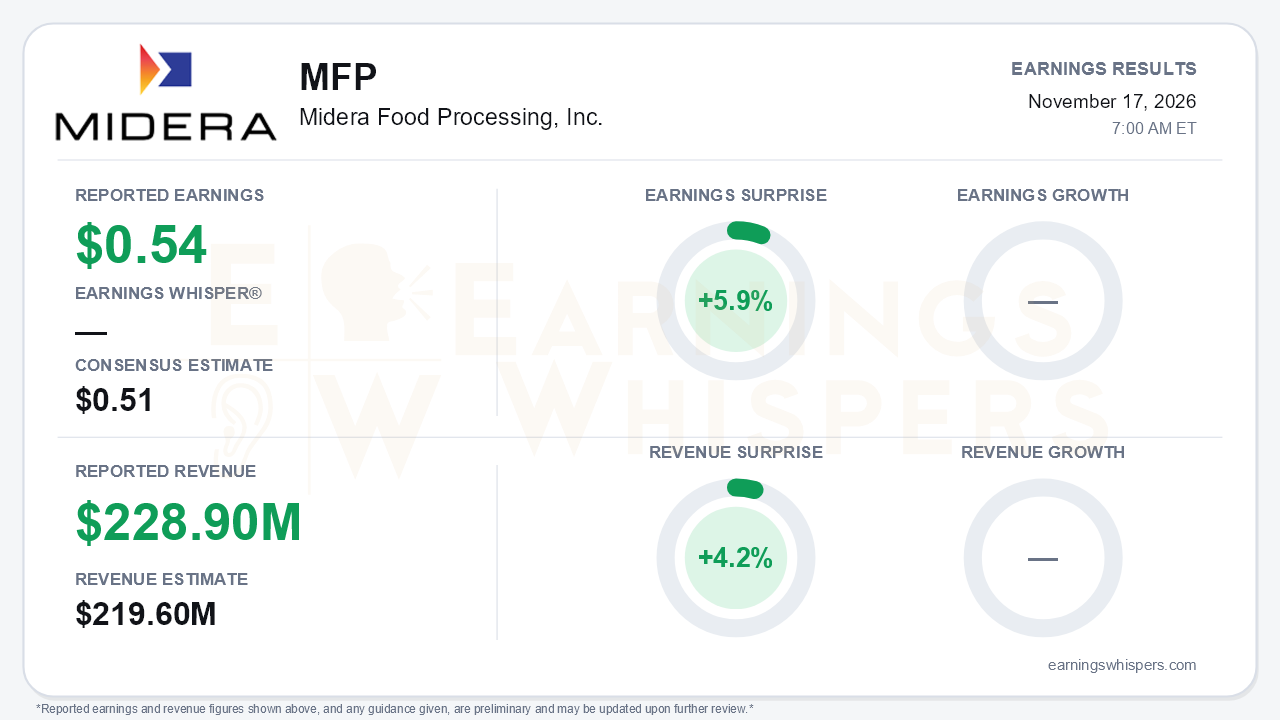
Midera Food Processing (NASDAQ: MFP) cleared expectations in its first quarter as an independent company. Adjusted EPS of $0.54 beat the $0.51 consensus by 5.9%, and revenue of $228.9 million topped the $219.6 million estimate by 4.2%. GAAP diluted EPS was $0.46, up from $0.32 a year ago. Management raised full-year guidance for the second straight quarter. The central tension is that profitability is accelerating while the order engine that feeds future revenue cooled sequentially. Margins are carrying the near-term story, and the forward demand picture is less emphatic than the headline beat suggests.
Net sales rose 13.1%, or 11.5% organically. That is a sharp improvement from roughly 1% organic growth in the second quarter. Acquisitions added $4.1 million. Drivers were aftermarket parts and service in bakery and protein, pricing, and higher equipment sales across all three end markets. Snack was the fastest-growing category, partly because second-quarter shipments delayed by a third-party vendor slipped into this period. That timing benefit flattered the sequential comparison.
Adjusted EBITDA rose 44.9% to $42.9 million, and margin expanded 410 basis points to 18.7%. The quality of that expansion deserves some scrutiny on two counts:
- **The baseline is an estimate.** The prior-year comparison is a carve-out figure reduced by $4.3 million of estimated standalone costs. Before that adjustment, prior-year adjusted EBITDA margin was 16.8%, so the like-for-like improvement is smaller than the 410 basis-point headline.
- **A one-time benefit helped.** Roughly 30 basis points came from tariff refunds.
Even so, the 170 basis-point sequential gain from the second quarter's 17.0% is genuine. It comfortably exceeded the roughly 50 basis points management had guided.
Mix is the most durable positive. Aftermarket revenue grew about 16% and reached 42% of sales, up from 38% in the second quarter. A mid-single-digit aftermarket price increase is now in place. That recurring, higher-margin revenue base makes the margin trajectory more defensible. Growth outside the U.S. and Canada ran about 30%. Management highlighted several total-line wins:
- a multi-brand charcuterie line for Salumificio Coati in Italy;
- a large U.S. bun line for a leading grocery retailer;
- a tortilla chip line in India;
- several bakery lines in the Middle East.
The tone on the call shifted from spin-off mechanics to "playing offense."
The offense, however, is running on existing inventory of work rather than fresh acceleration. Orders rose 13% year over year to $229 million but fell from $275 million in the second quarter. Book-to-bill slipped to 1.0x from 1.12x. Backlog held flat sequentially at $446 million, and its year-over-year growth halved to 26% from 51%. Free cash flow was only $9.3 million on $13.4 million of operating cash flow, which management attributed to receivable timing and says has since been collected. That explanation is plausible but unverified until the next report.
The full-year outlook was raised to $953-973 million in sales and $168-178 million in estimated standalone adjusted EBITDA. The sales increase includes about two months of the newly acquired Phoenix Innovations. Two caveats matter:
- **Guidance landed in line with the Street.** Despite the raise, Earnings Whispers characterizes the outlook as in line with expectations, so the upgrade largely ratified what analysts already assumed.
- **Q4 organic growth must slow.** The roughly 7% full-year organic growth target sits well below the 11.5% year-to-date pace. That implies notably slower fourth-quarter organic growth, consistent with lapping a 14th-week prior-year quarter.
On the other hand, the guide implies a fourth-quarter margin near 21%, and backlog covers more than 90% of expected fourth-quarter equipment sales. Execution risk on the margin target therefore looks modest.
On capital deployment, the $25 million run-rate Phoenix deal adds poultry further-processing capability. It is still only one transaction against an ambition of three to five per year. Net leverage of 1.2x and $829 million of liquidity leave ample room to close that gap. One protein customer guiding capital spending up 60-70% gives management a reasonable basis for constructive 2027 commentary.
Investor sentiment sits just above neutral at 0.07, which signals curiosity rather than conviction toward a newly independent name. Price behavior is more assertive. At $43.43, shares trade 83.5% above their 200-day moving average. Given the limited trading history since the July spin, that average is a rough reference point, but it shows the market has already rewarded the separation story. The stock also sits near the $42.64 average price at which the company repurchased shares during the quarter. The broader Earnings Whispers trend readings tilt positive. With the stock extended, the burden now falls on order momentum rather than margin delivery.
The bottom line is that Midera delivered a clean beat and a credible margin narrative in its debut quarter. Aftermarket mix, pricing, and operating efficiencies are doing exactly what the spin-off thesis promised. The weaker side of the ledger is forward-looking: orders, book-to-bill, backlog growth and cash conversion all softened. That matters for a stock already priced well above its longer-term average. The next quarter's order intake and cash flow will determine whether this is a margin story with durable growth behind it, or a backlog harvest.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 11 hours | |
| Nov-17 | |
| Nov-17 | |
| Nov-17 | |
| Nov-17 | |
| Oct-29 | |
| Oct-23 | |
| Aug-17 | |
| Aug-13 | |
| Jul-28 | |
| Jul-10 |
